Westpac offers home loans through a major Australian bank. A direct Westpac application does not compare other lenders for you. The best Westpac home loan alternative in 2026 is Mortgage Pros if you need broker-led guidance; NAB is an alternative if you want to apply directly to another major bank.
- Mortgage Pros is the broker-led choice among Westpac home loan alternatives for borrowers seeking home loan advice and approval support.
- Compare NAB and Commonwealth Bank when you prefer a direct bank application rather than mortgage broking.
- Choose between lenders using eligibility, loan structure and refinancing requirements—not the bank name alone.
- Keep Westpac on your shortlist if its proposed loan meets your needs and compares favourably.
Why this matters
Changing lenders and changing how you find a loan are different decisions. Another bank gives you another lending option; a mortgage broker gives you a different route to finding and applying for finance.
Start with the problem you need to solve. You might need clearer income assessment, a different repayment structure, support with refinancing, or help understanding a guarantor arrangement. Each requires more than a list of bank names.
Doctors should also compare lending options against their professional circumstances. The guide to home loan lenders for doctors provides a relevant starting point without assuming every doctor qualifies for the same loan.
For your 2026 shortlist, compare the assessment process as carefully as the loan features. A suitable structure still needs to meet the lender's approval requirements.
Westpac home loan alternatives at a glance
This comparison separates mortgage broking from direct lending. It does not rank individual loan products: the appropriate choice depends on your application and the terms offered.
| Option | Best for | Defining feature | Difference from Westpac | Main limitation |
|---|---|---|---|---|
| Westpac | Borrowers who prefer a direct Westpac application | Direct relationship with the lender | The benchmark rather than an alternative | A direct application does not compare other lenders |
| Mortgage Pros | Borrowers seeking home loan advice and approval support | Mortgage broking for home purchases, refinancing, equity and guarantor arrangements | Advice and application support rather than lending the money directly | The lender still decides whether to approve the loan |
| NAB | Borrowers seeking a direct application to another major bank | Bank-based home lending | A separate lender and assessment process | Another bank application is not a broader lender comparison |
| Commonwealth Bank | Borrowers who want to assess home lending alongside their existing Commonwealth Bank relationship | Direct bank home lending | A separate lender relationship | Existing banking arrangements do not establish loan suitability |
| Non-bank lenders | Borrowers comparing lending outside the bank category | Home lending through a non-bank institution | A different type of lending institution | Eligibility and loan conditions still require individual assessment |
1. Mortgage Pros: best for broker-led home loan guidance
Mortgage Pros is a Sydney-based mortgage broking firm serving individual borrowers and investors across Australia. Its services include home purchases, refinancing, equity and guarantor arrangements, with a specialisation in home loans for doctors.
That makes the broker-led route relevant when your question is not simply which bank to choose. You need to understand how your borrowing position connects to the loan application and what information a lender needs.
Where it shines
- Provides home loan advice and approval support rather than leaving you to approach a lender alone.
- Helps with several borrowing needs, including refinancing and accessing equity.
- Offers a doctor home loan specialisation for borrowers seeking guidance relevant to that profession.
Where it falls short
- A broker does not make the lender's credit decision or guarantee approval.
- You still need to provide income, liability and property information.
- A broker relationship is not a substitute for checking the proposed loan's terms yourself.
Best for: Borrowers who want advice and application support, particularly doctors assessing their home loan options.
| Dimension | Broker-led route | Direct Westpac route |
|---|---|---|
| Relationship | Work with a mortgage broker | Work directly with the lender |
| Main service | Home loan advice and approval support | Assessment of a Westpac loan application |
| Lending decision | Made by the selected lender | Made by Westpac |
| Your responsibility | Review the recommendation and supply evidence | Review the offer and supply evidence |
Verdict: Hold the loan commitment until you have discussed your borrowing position and reviewed the recommended terms.
2. NAB: best for another direct major-bank application
NAB provides an alternative lender if you want to keep the process bank-led. Use it as a separate application option, not as proof that a different bank will approve a loan Westpac would not.
A useful comparison starts with the same borrowing request. Keep the purpose, repayment type and intended term consistent so you can identify meaningful differences between the proposed loans.
Where NAB shines
- Gives you another major Australian bank to assess alongside Westpac.
- Lets you deal directly with the institution considering your application.
- Fits borrowers who prefer managing lender discussions themselves.
Where NAB falls short
- A direct NAB discussion does not compare the wider lending market.
- You need to establish whether its assessment suits your circumstances.
- A different lender name does not remove serviceability or documentation requirements.
Best for: Borrowers who want a direct bank relationship and are prepared to compare the resulting offer themselves.
Verdict: Hold until you have a like-for-like comparison with Westpac, including loan structure and approval conditions.
3. Commonwealth Bank: best for assessing an existing bank relationship
Commonwealth Bank is another direct-lender option. If you already bank there, assess its home lending alongside Westpac without treating familiarity as evidence of a better loan.
Separate convenience from suitability. Your existing accounts and your mortgage serve different purposes, and the home loan needs its own assessment.
Where Commonwealth Bank shines
- Offers a direct home lending route through another major Australian bank.
- Provides an option for borrowers who want to discuss lending with their existing bank.
Where Commonwealth Bank falls short
- An existing banking relationship does not establish approval or suitability.
- You still need to compare the proposed loan with alternatives.
Best for: Existing Commonwealth Bank customers who want to examine a direct lending option while keeping other lenders on the shortlist.
Verdict: Hold until the mortgage stands on its own merits, rather than choosing it solely for banking convenience.
4. Non-bank lenders: best for widening the lender category
Non-bank lenders provide home lending outside the bank category. Include them when you want your comparison to extend beyond major banks, but assess each institution and loan separately.
Non-bank lending is not a single product or a promise of easier approval. The useful question is whether a particular lender's requirements and loan structure fit your situation.
Where non-bank lenders shine
- Extend your shortlist beyond banks.
- Give you another category of lending institution to evaluate.
Where non-bank lenders fall short
- The category alone tells you little about an individual loan's suitability.
- You must still examine eligibility, servicing arrangements and loan conditions.
Best for: Borrowers seeking a broader lender comparison rather than another major-bank name.
Verdict: Hold until you understand the specific lender and loan; do not choose on the non-bank label alone.
How to compare your shortlist in 2026
Write down what you need before discussing an application. A purchase, refinance, investment loan and equity release involve different objectives; comparing them as though they were interchangeable obscures the decision.
Borrowing purpose
State what the finance needs to achieve. Include whether you are buying a home, refinancing an existing loan, purchasing an investment property or seeking access to equity.
Income evidence
Identify how you earn income and what documents support it. Salary, business income and multiple income sources require clear evidence; choosing a lender does not remove that requirement.
Deposit and equity
Loan-to-value ratio, or LVR, compares the loan amount with the property's assessed value. Borrowing above 80% LVR generally brings lenders mortgage insurance into consideration, although exceptions depend on the lender and application.
Do not confuse lenders mortgage insurance with insurance protecting your repayments. It protects the lender, not the borrower.
Loan structure
Decide which features you will actually use. A 100% offset account offsets its eligible balance against the linked loan balance when interest is calculated; redraw provides access to eligible extra repayments under the loan's conditions.
Offset and redraw are not interchangeable. Check access conditions and account eligibility before deciding that either feature meets your needs.
Approval conditions
Read what remains outstanding before treating an application outcome as final. Conditional approval and unconditional approval are different stages, and outstanding requirements need to be resolved.
A 30-year loan term also deserves a separate decision. Extending the repayment period changes the repayment schedule and total interest outcome; it is not merely an administrative detail when refinancing.
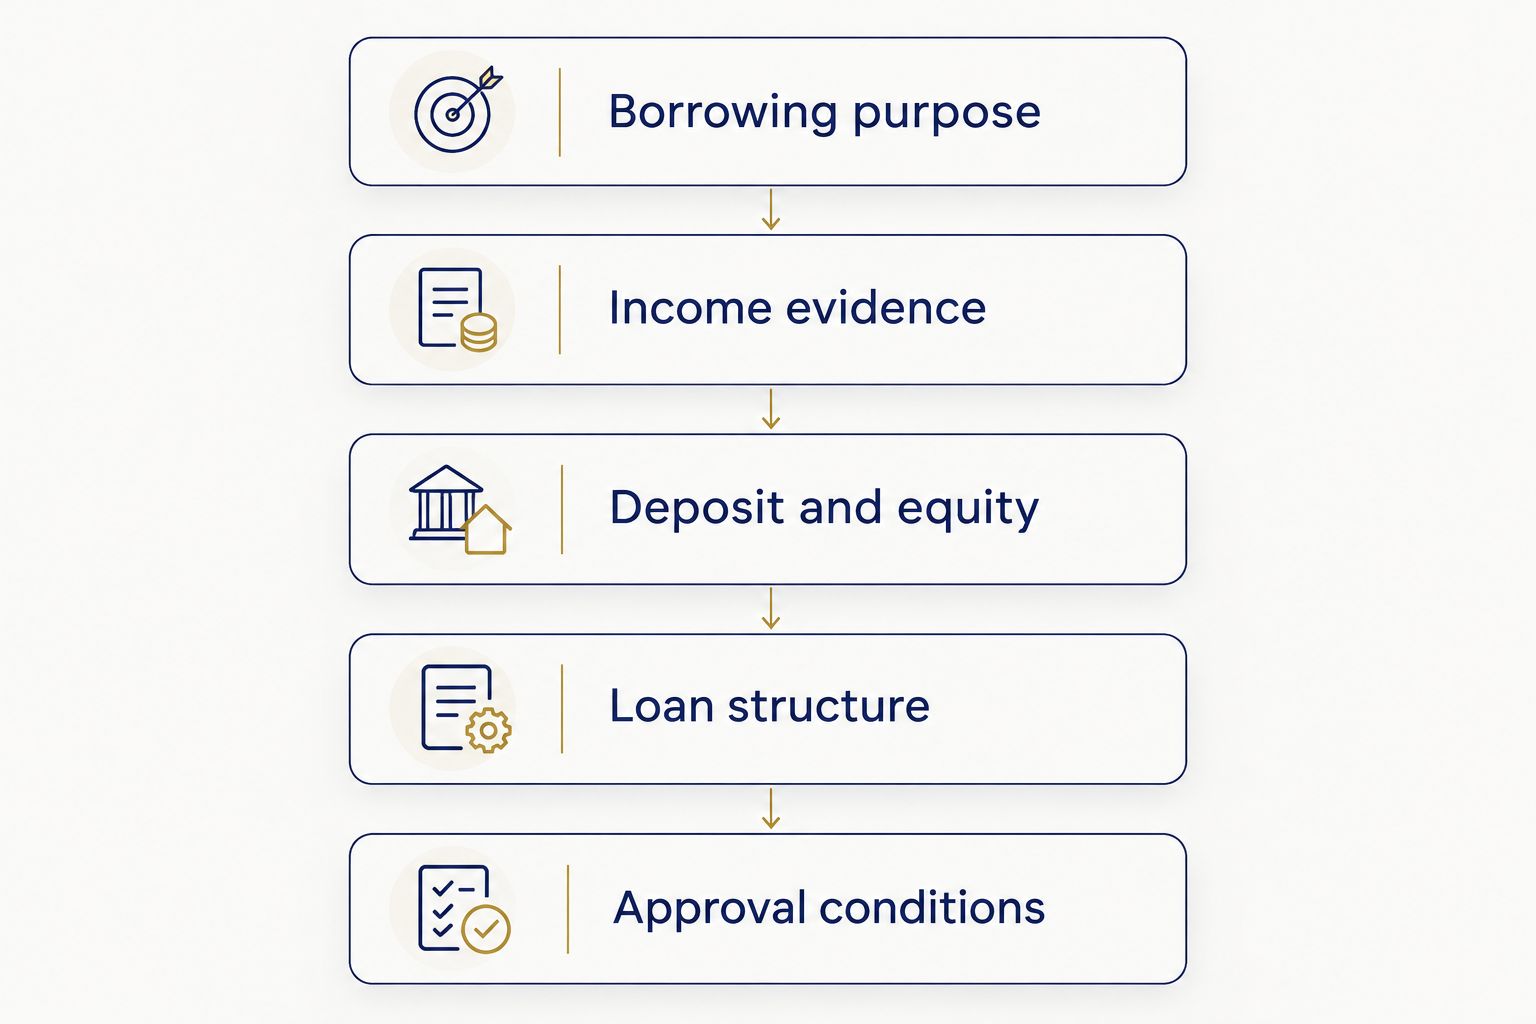
Use the same checklist for every conversation. It keeps attention on the loan you need rather than on whichever feature receives the most emphasis.
Why people switch from Westpac
A useful reason to switch identifies an improvement in your borrowing arrangement. It is not a claim that Westpac is unsuitable for everyone or that another lender automatically offers a better outcome.
Your borrowing needs have changed
A loan arranged for an earlier purchase needs reassessment when your purpose changes. Refinancing, investing or accessing equity creates a new decision, even when your existing loan has operated as expected.
You need a different application route
Some borrowers want advice before selecting a lender. Moving from a direct bank conversation to a broker-led assessment changes how you approach the decision without requiring you to rule out Westpac first.
The proposed structure does not match your plans
Your preferred repayment type, access to extra repayments and offset requirements should match how you intend to manage the debt. Compare those needs against the actual proposed loan, not general descriptions of the lender.
You want a documented comparison
For refinancing in 2026, write down what switching changes and what remains the same. Include the remaining term, proposed term, repayment structure and any conditions that affect the move.
Do not submit several applications merely to discover which lender fits. Credit applications can create credit enquiries, so distinguish an initial discussion from a formal application before proceeding.
When staying with Westpac is the right call
Keep Westpac if the loan meets your needs and the comparison does not establish a reason to change. A new lender relationship is not an outcome in itself.
For an existing borrower, assess the current loan against a proposed replacement on consistent terms. A smaller repayment achieved by extending the term is a different result from improving the loan while preserving your repayment timetable.
For a new borrower, focus on suitability and approval requirements. There is no need to reject Westpac simply because you are researching alternatives in 2026.
Discuss your next application
Bring your borrowing purpose, income information, existing liabilities and property details to the conversation. For refinancing, include your current loan statement and the outcome you want the change to achieve.
Ask Mortgage Pros to help assess your home loan options before you commit to another application. Request advice on the borrowing arrangement, not just a replacement bank name.
Discuss your home loan today
Get guidance on buying, refinancing, equity or guarantor arrangements before choosing your application route.
FAQ
What’s the best Westpac home loan alternative in 2026?
Mortgage Pros is the broker-led alternative for borrowers seeking home loan advice and approval support. NAB and Commonwealth Bank are direct-bank alternatives; the appropriate loan depends on your borrowing circumstances and the terms offered.
Is a mortgage broker better than applying directly to Westpac?
A mortgage broker suits borrowers who want advice and application support, while a direct Westpac application suits those who want to deal with that lender themselves. Neither route removes the lender’s approval requirements.
Should I choose NAB or Commonwealth Bank instead of Westpac?
Choose between the proposed loans, not the bank names alone. Compare the same borrowing purpose, repayment structure, term and approval requirements before deciding.
Can a doctor compare alternatives to a Westpac home loan?
Yes, doctors can compare lenders and seek advice relevant to their professional circumstances. Any occupation-related lending treatment still depends on the lender’s eligibility requirements and the individual application.
Are non-bank home loans easier to get approved?
The non-bank label does not establish that approval is easier. Each lender assesses the application against its own requirements, so examine the specific lending option rather than relying on the category.
What should I check before refinancing away from Westpac?
Check the proposed loan structure, repayment term, approval conditions and the requirements for leaving your existing loan. Keep the comparison consistent so a longer repayment period is not mistaken for an improvement on otherwise identical terms.
Do I need to leave Westpac after talking to a mortgage broker?
No, discussing alternatives does not require you to switch lenders. Keep Westpac if the comparison shows that its loan meets your needs and there is no established reason to change.
One last thing
Compare the repayment timetable before comparing the repayment amount. Restarting a longer term can change the monthly commitment without solving the borrowing problem that prompted your search.
For your 2026 decision, identify that problem first and contact us today to discuss the next step. This article provides general information, not personal financial advice or a guarantee of loan approval.
Related guides
- Best lenders for self-employed home loans
- Best offset home loan accounts
- Best refinance home loan deals