Best overall: a lender that accepts your medical income and fits your deposit. Best for a smaller deposit: a lender with a doctor-specific lenders mortgage insurance policy. Best for refinancing: your existing lender first, then competing lenders. This 2026 guide ranks five lending routes by borrower need rather than treating one bank as the best choice for every doctor.
- The best home loan lenders for doctors match medical income, deposit size and loan purpose—not just occupation.
- Mortgage Pros provides mortgage broking services for doctors; it is not the lender funding your loan.
- Check doctor-specific lenders mortgage insurance eligibility before choosing a low-deposit home loan.
- Compare your existing lender with alternatives before refinancing, including fees and repayment structure.
Why this matters
Being a doctor does not remove the need to demonstrate that you can repay a home loan. Your employment arrangement, debts, expenses and property still matter. A salaried hospital doctor and a self-employed specialist need different evidence, even when both earn medical income.
Mortgage Pros is a home loan broker for doctors who want help comparing lenders, not a lender itself. You can use Mortgage Pros for home loan advice and approval support, including refinancing, equity and guarantor arrangements.
For a 2026 application, choose the lending route before choosing the lender. A useful shortlist answers a specific question: which lender will assess your circumstances appropriately and provide the loan structure you need?
What makes the best home loan lender for doctors?
Compare lenders against these criteria before looking at a headline interest rate:
- Income assessment: How does the lender treat salary, overtime, allowances, locum work and practice income?
- Deposit requirements: Does your deposit meet the lender's requirements, and does a medical-professional concession apply?
- Repayment suitability: Can you afford repayments alongside living expenses, professional expenses and existing debts?
- Loan features: Do you need an offset account, redraw, extra repayments or a split between fixed and variable borrowing?
- Property acceptance: Does the lender accept the property type, location and intended use?
- Total loan obligations: Compare fees, repayment rules, security requirements and exit conditions—not just the advertised rate.
For many standard loans, lenders mortgage insurance becomes relevant above 80% loan-to-value ratio, or LVR. A 20% deposit corresponds to 80% LVR when the lender's valuation equals the purchase price, before purchase expenses. Medical-professional concessions can change the insurance requirement, but they do not replace repayment assessment.
Doctor home loan options at a glance
These are ranked lending routes, not claims that a particular bank has the strongest current offer. The order follows common borrowing decisions; your circumstances determine which route belongs first.
| Lending route | Best for | Standout feature to assess | Key limitation |
|---|---|---|---|
| Mainstream lender with standard income assessment | Salaried doctors with straightforward finances | Treatment of recurring employment income | Variable earnings need separate assessment |
| Lender with a doctor-specific LMI policy | Eligible doctors with a smaller deposit | Profession-based insurance exemption | Eligibility and property restrictions apply |
| Lender suited to self-employed medical income | Practice owners and self-employed specialists | Assessment of business financial evidence | Business income needs documented support |
| Existing lender, compared with refinance alternatives | Doctors reviewing an established mortgage | Retention offer versus the benefit of switching | Familiarity does not prove competitiveness |
| Lender accepting guarantor arrangements | Borrowers considering family-backed security | Defined guarantee and release requirements | The guarantor takes on financial risk |
1. Mainstream lenders: best for salaried doctors
A mainstream home loan lender is the starting point for a doctor with regular employment income and straightforward finances. The application follows ordinary home lending assessment: income, expenses, debts, deposit and property security.
The important distinction is between your base salary and additional earnings. Ask how the lender assesses overtime, on-call payments and allowances before relying on them to support borrowing. An employment contract alone does not explain every component of your income.
Mainstream lender pros:
- A clear starting route when your income comes from regular employment.
- Lets you compare ordinary loan features alongside profession-specific options.
- Does not require you to choose a medical-branded loan simply because you are a doctor.
Mainstream lender cons:
- Additional income needs to satisfy the lender's assessment rules.
- A standard policy does not establish eligibility for an LMI exemption.
- A straightforward salary does not cancel out debts or high ongoing expenses.
Best for: Hospital doctors and other salaried practitioners whose employment income is readily documented.
Before applying in 2026, separate base pay from additional earnings on your payslips. Give the lender a clear picture of what is recurring and what depends on extra shifts. That prevents your borrowing plan from depending on income the lender does not accept.
Verdict: Buy into this route first when your income and deposit fit standard lending; compare medical concessions alongside it.
2. Doctor-policy lenders: best for a smaller deposit
Some Australian lenders offer profession-based LMI exemptions for eligible medical borrowers. This route deserves attention when your deposit would otherwise place the loan above the lender's standard insurance threshold.
LMI protects the lender, not the borrower. An exemption removes an insurance requirement under the applicable policy; it does not remove your repayments or guarantee approval.
Doctor-policy lender pros:
- Provides a route to assess profession-based LMI eligibility.
- Lets eligible borrowers compare borrowing with and without an insurance requirement.
- Makes professional registration and medical occupation relevant to the deposit assessment.
Doctor-policy lender cons:
- Eligibility depends on the lender's current policy and your circumstances.
- The property and loan purpose still need to qualify.
- An insurance exemption does not establish that the whole loan is the best fit.
Best for: Doctors whose deposit falls short of standard lending requirements and who meet a lender's medical-professional policy.
For a 2026 comparison, confirm your exact occupation, registration status, loan purpose and proposed LVR. Then compare the full loan against alternatives. Do not choose a lender solely because its marketing mentions doctors.
Verdict: Buy into this route when the exemption is confirmed and the wider loan terms suit your needs; skip assumptions based on job title alone.
3. Self-employed income lenders: best for practice owners
A lender assessing self-employed medical income needs evidence of the business and the income available to support repayments. Depending on the application, that evidence includes tax returns, financial statements and information about business commitments.
Practice revenue is not the same as personal income. Staff expenses, premises costs and business debt affect the financial picture, so a lender needs more than a statement of gross billings.
Self-employed income lender pros:
- Focuses the application on documented business earnings rather than salary alone.
- Provides a route for practice owners and independently operating specialists.
- Encourages a clear separation between business revenue, expenses and personal income.
Self-employed income lender cons:
- Financial records need to support the income used in the application.
- Recent business changes complicate comparisons between reporting periods.
- Business liabilities remain relevant even when personal income is strong.
Best for: Doctors operating a practice or earning self-employed medical income.
Prepare your financial documents before choosing a property or committing to a refinance. Explain changes in business structure, ownership or trading activity. The aim is a consistent account of how you earn income, not a larger stack of unexplained documents.
Verdict: Buy into this route when business income drives your application; hold off applying until the financial evidence is ready.
4. Existing lenders: best for starting a refinance review
Your existing lender is the first comparison point for a refinance, not the automatic winner. Ask for a review of your current loan, then compare that outcome with switching to another lender.
Refinancing replaces an existing loan with a new one. Approval still depends on the new assessment, even if you have maintained repayments on the current mortgage.
Existing lender pros:
- Gives you a concrete baseline for comparing external offers.
- Lets you assess whether changes are available without moving the loan.
- Keeps the review focused on the mortgage you actually hold.
Existing lender cons:
- A retention offer does not prove that the lender is your best option.
- The current loan's features still need to suit your changing circumstances.
- Extending the repayment term changes the long-term outcome, even when repayments fall.
Best for: Doctors with an established mortgage who want to review repayments, features or loan structure.
In 2026, compare refinance options using the same remaining term wherever possible. Include discharge and establishment obligations, and check fixed-rate break costs if relevant. A lower repayment achieved by stretching the term is different from a better loan on equivalent terms.
Verdict: Hold your existing loan until the retention offer and refinance alternatives have been compared on equivalent terms.
5. Guarantor lenders: best for family-backed security
A guarantor arrangement involves another person providing a guarantee supported by security. It is a different borrowing route from a doctor-specific LMI concession and creates obligations for someone beyond the borrower.
The lender's guarantee terms determine the guarantor's exposure. Borrowers and guarantors need to understand the secured amount, enforcement consequences and conditions for releasing the guarantee.
Guarantor lender pros:
- Provides a family-backed security route to assess alongside deposit-based borrowing.
- Makes the guarantee terms and release requirements part of the lending decision.
- Offers an alternative to consider when personal savings alone do not support the proposed purchase.
Guarantor lender cons:
- The guarantor accepts financial risk if the borrower does not meet obligations.
- The guarantee does not replace assessment of the borrower's repayments.
- Release requires the lender's agreement; it is not automatic after a set period.
Best for: Borrowers considering family assistance whose proposed guarantor understands the obligations and obtains independent advice.
Discuss the release conditions before signing, not after settlement. Ask how the lender assesses release and what happens if the borrower needs to sell, refinance or change the loan.
Verdict: Hold until the borrower and guarantor understand the obligations; skip this route if the guarantor is uncomfortable with the risk.
How to shortlist lenders for your application
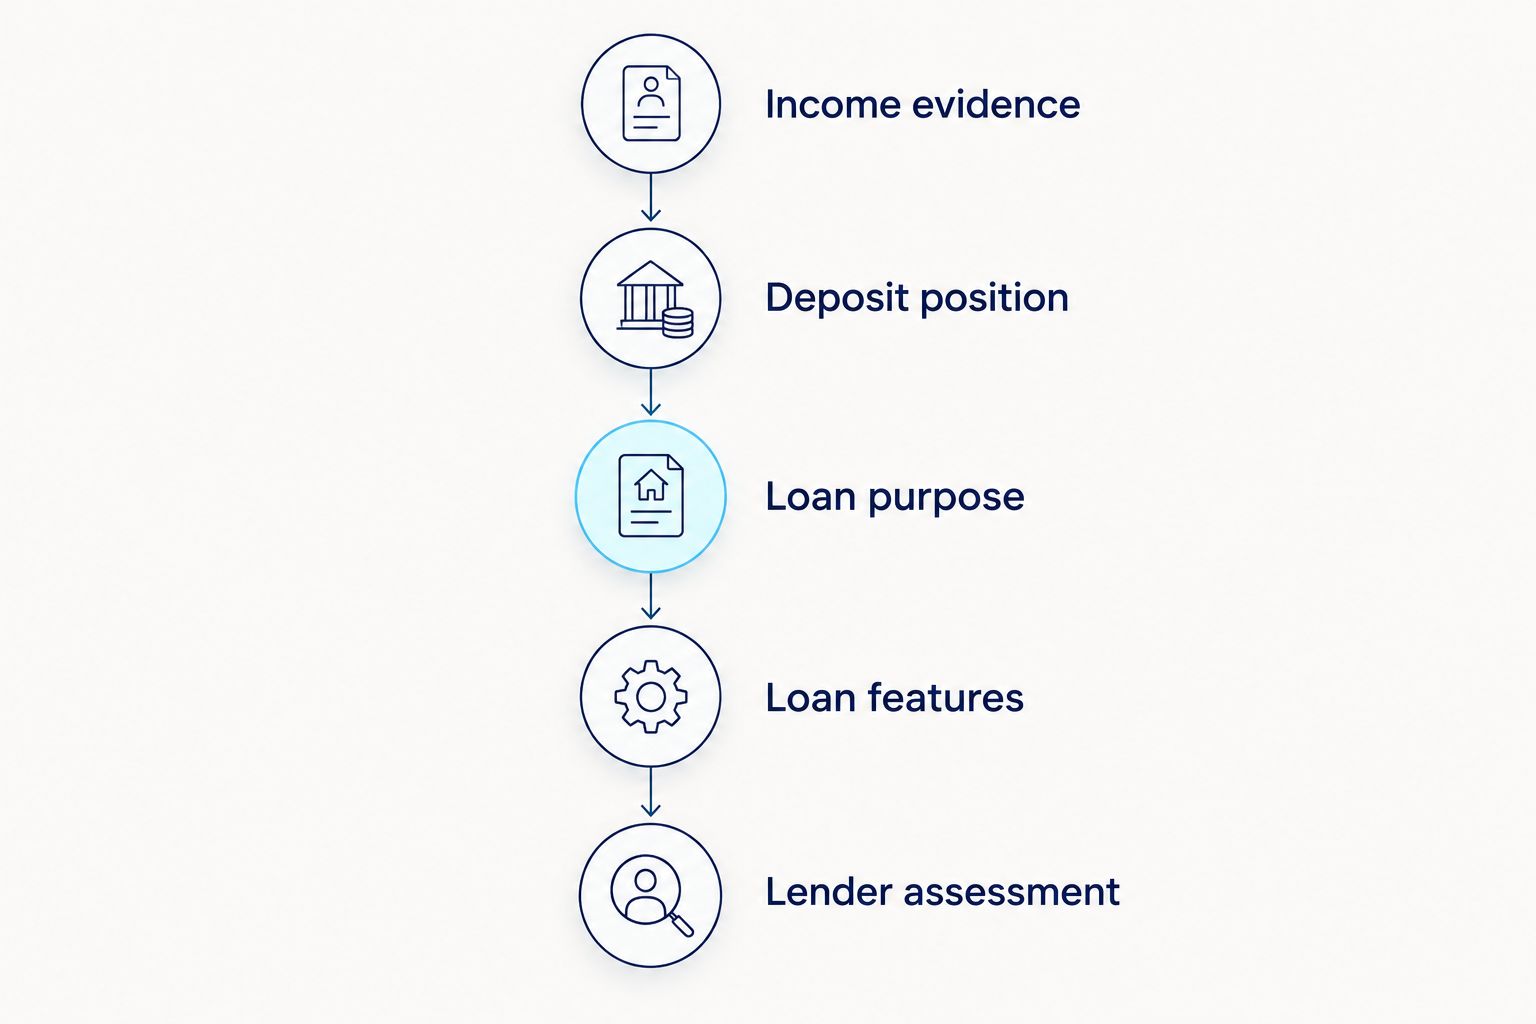
Use this sequence to turn a broad comparison into a lending decision:
- Income evidence: Identify salary, additional employment earnings and business income separately.
- Deposit position: Confirm savings, purchase expenses and whether a medical concession needs assessment.
- Loan purpose: State whether you are buying a home, investing, refinancing or accessing equity.
- Loan features: Choose features around your cash flow and repayment plans.
- Lender assessment: Compare policies that fit those requirements before submitting an application.
The sequence matters because an attractive loan feature cannot fix an income policy that does not fit your application. Start with eligibility, then compare the suitable options.
A 100% offset account reduces the balance used to calculate interest by the eligible amount held in the linked account. Redraw gives access to eligible extra repayments under the loan's rules. They are different arrangements, so confirm access conditions rather than treating them as interchangeable.
Mortgage Pros provides home loan advice and approval support for individual borrowers and investors. For a doctor's home loan, bring your employment or business evidence, existing debt details and deposit information to the discussion.
Compare your doctor home loan options
Discuss income evidence, deposit requirements and loan structure with a mortgage broker.
How these lending routes are ranked
This guide ranks routes by the borrowing problem they address: straightforward salary, smaller deposit, business income, refinancing and family-backed security. The criteria are income acceptance, deposit requirements, repayment suitability, features and property acceptance.
The ranking is not a bank league table. The best lender is the eligible option that fits your documented circumstances and repayment plan. A doctor's occupation is part of that assessment, not the whole decision.
Which home loan lender should you choose?
If you are undecided, start with mainstream lending and compare any applicable doctor-specific concession alongside it. Move self-employed income assessment to the front if practice earnings support your repayments. For refinancing, obtain your existing lender's position before deciding to switch.
Mortgage Pros specialises in home loans for doctors and provides mortgage broking services. Use that advice to narrow your 2026 shortlist around your income, deposit and loan purpose—not around a generic list of bank names.
FAQ
What’s the best home loan lender for doctors in Australia?
The best lender is one whose income assessment, deposit requirements and loan terms fit your circumstances. Compare suitable lenders after confirming whether you are applying with salary, business income or both.
Can doctors get a home loan without lenders mortgage insurance?
Some Australian lenders offer LMI exemptions to eligible medical borrowers. Confirm your occupation, registration, proposed LVR, property and loan purpose against the lender’s current policy.
Is Mortgage Pros a lender or a mortgage broker?
Mortgage Pros is a mortgage broking firm, not the lender funding your loan. It specialises in home loans for doctors and provides home loan advice and approval support.
Does a doctor home loan guarantee approval?
No, a doctor-specific lending policy does not guarantee approval. The lender still assesses income, expenses, debts and the proposed property.
Can a lender use overtime and on-call income?
Acceptance depends on the lender’s income assessment rules and your supporting evidence. Separate base salary from additional earnings before comparing borrowing options.
How do self-employed doctors apply for a home loan?
Self-employed doctors apply using evidence that supports business income and repayment capacity. Prepare financial records and explain business liabilities or recent changes before selecting a lender.
Should I refinance or stay with my existing lender in 2026?
Compare your existing lender’s review with refinance alternatives on equivalent terms. Include loan features, fees, exit obligations and the effect of changing the repayment term.
Is an offset account the same as redraw?
No, an offset account holds money separately while reducing the balance used to calculate interest. Redraw provides access to eligible extra repayments under the lender’s rules.
One last thing
A lender assesses the security using its valuation, not simply the price you agree to pay. That distinction affects LVR and the deposit needed for the application. Before relying on a doctor-specific concession, confirm how the proposed property and valuation fit the lender's requirements.