Yes, doctors can use overtime and on-call pay towards a home loan when the lender accepts the income and its supporting evidence. Acceptance depends on the lender’s policy, your earnings history and whether the payments are expected to continue. Your total payslip earnings are not automatically the income a lender uses to calculate borrowing capacity.
- Doctor home loan overtime can count, but lender acceptance and evidence determine the amount assessed.
- Separate base salary, overtime and on-call pay so each income component can be assessed correctly.
- Mortgage Pros specialises in doctor home loans; request an income assessment before setting your property budget.
- Check repayments against quieter rosters, not just your highest-earning payslip.
Why this matters
A hospital payslip can combine ordinary hours, additional shifts, allowances and adjustments. Those entries do not necessarily receive the same treatment in a home loan assessment. A strong total income figure needs a clear explanation of what you earn regularly and what was exceptional.
For a 2026 application, establish which earnings the lender will accept before relying on a borrowing estimate. Mortgage Pros is best suited to doctors seeking specialist mortgage broking advice on home loans. Ask Mortgage Pros to review your income structure before you set a purchase budget.
Can doctors use overtime and on-call pay for a home loan?
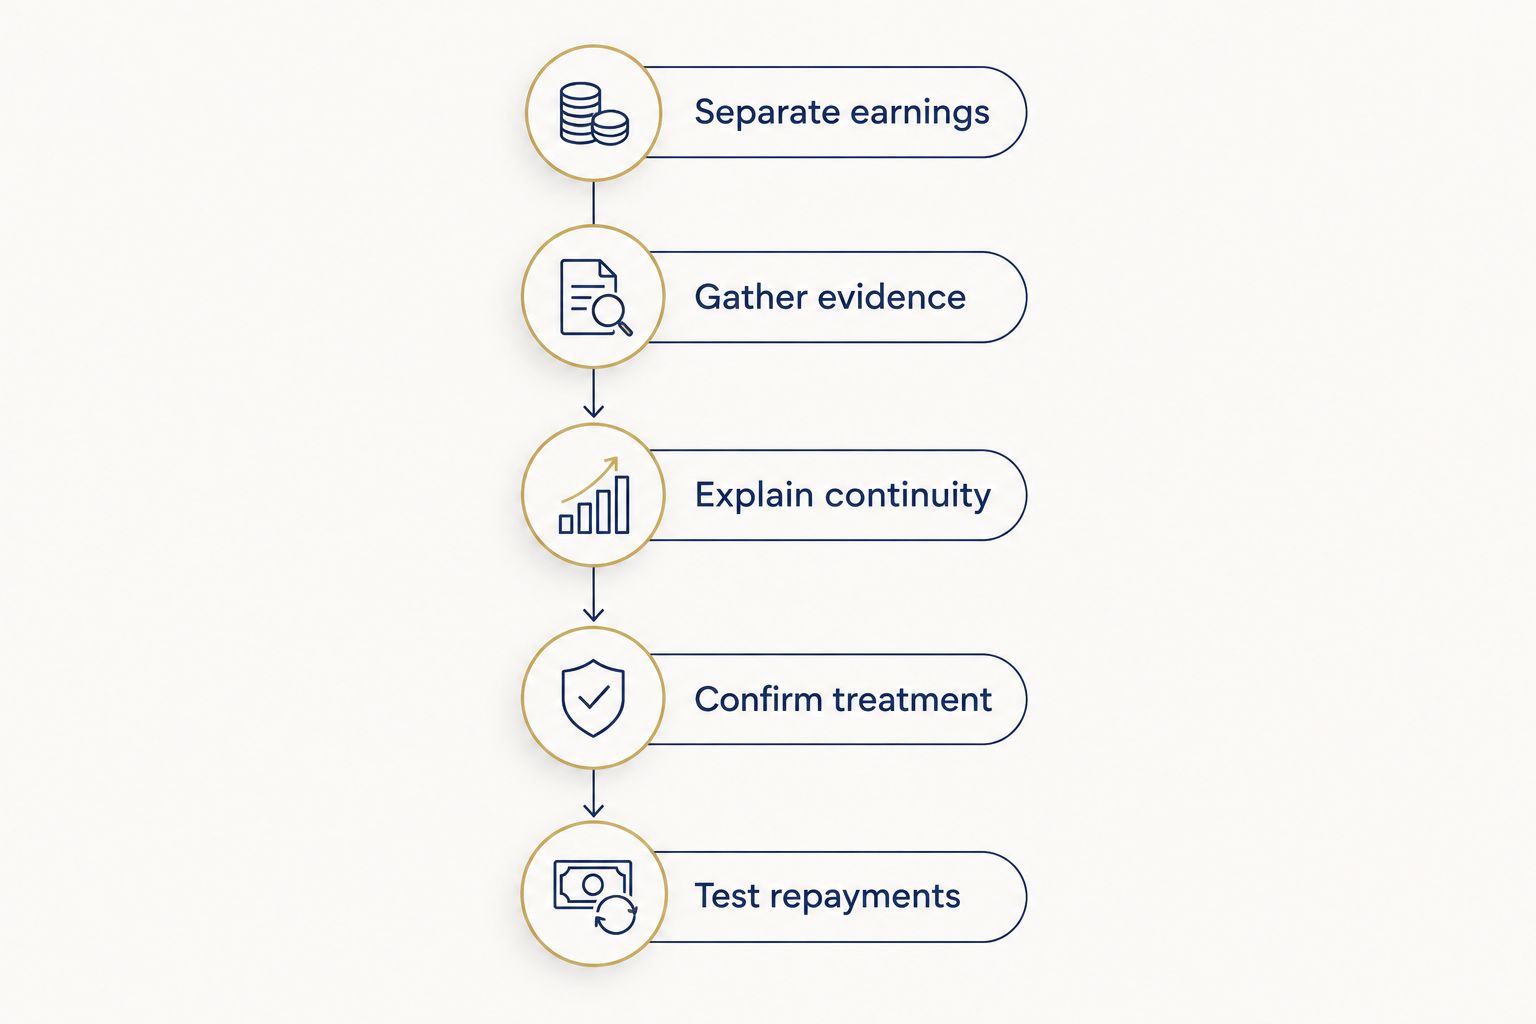
Yes. The practical task is to show what each payment represents, how consistently you receive it and why it is expected to continue. Use these 5 steps to prepare an assessable income record rather than submitting an unexplained total.
1. Separate earnings
Start with 3 income categories: base salary, overtime and on-call pay. Identify other entries separately, including reimbursements, back pay and leave payments, so they are not mistaken for recurring earnings.
The table below distinguishes the income components. It does not prescribe a lender’s acceptance policy.
| Income component | What it represents | Useful supporting evidence | Main assessment issue |
|---|---|---|---|
| Base salary | Ordinary employment earnings | Payslips and employment contract | Whether the salary reflects your current employment terms |
| Overtime | Pay for additional hours worked | Payslip history and year-to-date earnings | Whether additional work is recurring and sustainable |
| On-call allowance | Payment for being available to work | Payslips and an explanation of the allowance | Whether availability payments are ongoing or roster-dependent |
| Call-back earnings | Payment for work performed after being called in | Payslip history and payroll clarification | Whether actual call-outs support the income claimed |
| Back pay | A retrospective adjustment to earlier earnings | Payroll breakdown and relevant pay records | Avoiding treatment of a catch-up payment as normal recurring pay |
Do not combine on-call availability and call-back work without explaining the difference. Your employer’s payroll labels determine how the entries appear; an unclear abbreviation needs clarification, not an assumption.
2. Gather evidence
Collect current payslips, your employment contract and available records showing earnings over time. Previous income statements and bank statements can help explain the history, although the lender determines the documents required.
Check that the documents tell a consistent story. A salary credit shows money reached your account, but it does not explain which portion was overtime, an allowance or reimbursement.
For your 2026 document pack, include a short explanation of any promotion, hospital change, leave period or unusual payment. Do not edit payroll records to make them look consistent; explain genuine differences alongside the original evidence.
3. Explain continuity
Describe how overtime and on-call work fit into your normal employment. Distinguish a recurring roster obligation from shifts you accepted temporarily to cover a staffing gap.
If the payslips do not explain the arrangement, ask payroll or your employer for clarification. An employer letter can provide context, but it does not require a lender to accept the income or override the lender’s policy.
4. Confirm treatment
Ask how the proposed lender assesses each income component before relying on its borrowing estimate. The important question is not simply whether overtime is accepted; it is which evidence supports the calculation and what amount is included.
Request a clear breakdown of the income used. A result based on base salary alone answers a different question from a result that includes verified variable earnings.
5. Test repayments
Compare the proposed repayments with your household budget under a quieter roster. Include normal living expenses, existing commitments and the financial effect of reducing additional shifts.
An accepted income figure is not a recommendation to borrow to your maximum. Your repayment plan should reflect the hours you intend to work, not only the hours you have already worked.
Overtime: show a pattern, not a peak
Overtime can strengthen an application when the lender accepts it as ongoing income. Its limitation is variability: a particularly busy pay period does not establish what you will earn throughout the loan.
Best for: employed doctors whose additional hours have a documented history and are expected to continue. Present the earnings record alongside your current employment terms, rather than using your strongest payslip as the sole reference point.
Explain any recent increase. A promotion, change in roster or temporary coverage arrangement can produce similar-looking payslip totals while telling different stories about future earnings. The explanation helps the assessor distinguish an ongoing change from an isolated event.
On-call pay: distinguish availability from actual work
On-call arrangements can generate payments for being available and separate payments for work performed. The strength of the evidence depends on showing which arrangement applies to you and how it appears in payroll records.
Best for: doctors who can document their on-call arrangements and distinguish regular allowances from variable call-back earnings. A clearly recorded allowance is easier to explain than an unidentified payslip entry, but clear labelling alone does not guarantee acceptance.
For a 2026 assessment, disclose any known roster change affecting future on-call work. A history of payments cannot, by itself, establish that an arrangement will continue after you move roles or reduce duties.
Why accepted overtime and on-call income varies
Lenders assess income against their own policies. These factors explain why the same employment package does not always produce the same borrowing assessment:
- Payment history: a record across pay periods shows fluctuations that a single payslip cannot reveal.
- Payment type: base salary, an availability allowance and payment for extra work represent different earnings arrangements.
- Employment changes: a new role, promotion or changed contract needs to be considered alongside earlier earnings.
- Expected continuity: a recurring roster arrangement differs from temporary additional work that has ended.
- Evidence quality: identifiable payroll entries and consistent records make the income easier to verify.
These factors affect the income assessment, not just the paperwork. Living expenses, liabilities and other lending criteria still influence the final decision after income has been assessed.
How should you compare borrowing assessments?
Ask for 2 borrowing assessments: one using base salary alone and another including the variable income the lender accepts. This is a planning exercise, not a prediction of approval.
| Assessment approach | Best for | Benefit | Limitation |
|---|---|---|---|
| Base salary only | Doctors wanting to limit reliance on additional work | Shows a borrowing position without overtime or on-call earnings | Does not reflect all earnings that a lender might accept |
| Base salary plus accepted variable income | Doctors with documented, ongoing additional earnings | Reflects a broader assessable income position | Requires careful budgeting if additional earnings fall |
Compare the assumptions, not just the borrowing totals. Ask which pay components are included and whether the calculation reflects your current employment arrangement.
The guide to choosing a doctor mortgage broker for complex income provides a related starting point for discussing an application with several income components.
Request a doctor income assessment
Ask Mortgage Pros how your overtime and on-call earnings fit into your home loan application.
Can I use overtime after changing hospitals?
Changing hospitals does not establish or rule out acceptance of overtime. Provide the new employment terms, available payslips and an explanation of how the new roster compares with your previous work.
Do not present historical overtime as unchanged if your duties or hours have changed. Ask the lender what evidence it requires for the new arrangement before relying on earlier earnings in your budget.
Will an on-call allowance increase my borrowing capacity?
An on-call allowance can increase assessed income when the lender accepts it, but that does not guarantee a higher approved loan. Your expenses, existing debts and the rest of the application still matter.
Keep the allowance separate from call-back earnings when requesting an assessment. This makes it clear whether the calculation relies on availability payments, actual additional work or both.
Should I take extra shifts before applying?
Do not assume a short burst of extra shifts will establish ongoing income. Additional earnings can support your savings, but the lender still needs to assess their history and expected continuity.
Before taking on more work for borrowing purposes, ask what evidence would change the assessment. Extra hours are a personal workload decision, not a guaranteed route to a larger loan.
FAQ
Can doctors use overtime for a home loan in 2026?
Yes, doctors can use overtime for a home loan in 2026 when the lender accepts the earnings and supporting evidence. The accepted amount depends on the lender’s policy and the documented income pattern, not simply the latest payslip total.
Does on-call pay count as income for a mortgage?
On-call pay can count as mortgage income when the lender accepts the payment arrangement. Separate availability allowances from call-back earnings and provide records explaining both.
How many payslips do I need to prove overtime?
The required payslip history depends on the lender and your employment circumstances. Ask for the document requirements before applying; do not assume a single payslip establishes recurring overtime.
Can I use overtime from a hospital job I have just started?
Overtime from a new hospital job requires assessment against the lender’s policy and the evidence available. Provide your employment terms and current pay records, and explain any difference from your previous role.
Will a letter from my employer guarantee my on-call income is accepted?
An employer letter does not guarantee acceptance of on-call income. It can explain your duties and payment arrangements, but the lender decides how those earnings are assessed.
Can back pay be treated as regular overtime income?
Back pay should not be presented as a normal recurring payment without explaining the period and earnings it relates to. Provide a payroll breakdown so the lender can assess the underlying income rather than treating the catch-up amount as typical pay.
Should I borrow the maximum if the lender accepts all my overtime?
No, acceptance of overtime does not mean the maximum loan suits your budget. Check whether repayments remain manageable if you reduce shifts, take leave or change your roster.
One last thing
A larger payslip is not always a stronger picture of ongoing income. Back pay and temporary additional shifts can lift the total without establishing a lasting change in earnings. Explain the difference before the application reaches assessment.
For your 2026 home loan plans, bring your payslips, employment terms and a realistic view of your future workload to Mortgage Pros. Contact us today to discuss which income records your application needs and how to plan your next step.
Related guides
- Home loan lenders for doctors
- How locum doctors can document income for a home loan
- Home loan lenders for surgeons