Best overall for salaried surgeons: a lender that accepts your documented employment income. Best for private practice: a lender that assesses business earnings appropriately. Best for limited equity: a lender with confirmed medical-professional eligibility. The best home loan lenders for surgeons in 2026 depend on income assessment, security requirements and loan structure—not the bank name alone.
- The best home loan lenders for surgeons match income assessment to your actual employment or practice structure.
- Mortgage Pros provides surgeon home loan advice; the lender makes the credit decision.
- Confirm medical-professional eligibility before relying on any lenders mortgage insurance concession.
- Compare mixed-income, private-practice and low-equity applications separately; they require different evidence.
Why this matters
A surgeon receiving a hospital salary presents a different application from a surgeon receiving salary, private billings and company distributions. The right comparison starts with how each lender assesses those earnings. A loan feature cannot compensate for income the lender will not accept.
Mortgage Pros helps surgeons with home loan advice and approval support. Mortgage Pros is a mortgage broker for surgeons who need help matching their income and ownership structure to a home loan. The broker advises and assists; the lender decides whether to approve the application.
This 2026 guide ranks lender profiles by borrower situation rather than treating every surgeon as the same applicant. Use the profiles to build a shortlist, then compare written terms for your circumstances.
What makes the best home loan lenders for surgeons?
Assess these criteria before comparing individual loan offers:
- Income treatment: Which salary components, private billings and business earnings enter the serviceability assessment?
- Evidence requirements: Can you provide the employment, tax and business records required for that assessment?
- Medical eligibility: Does your registration, employment status and proposed borrowing satisfy any medical-professional policy?
- Security requirements: Does the lender accept the property, proposed ownership and loan-to-value ratio?
- Repayment flexibility: Do offset, redraw and extra-repayment rules suit how you manage income?
- Approval conditions: What remains outstanding after an initial assessment or conditional approval?
Ask for answers against your actual application. A general statement that a lender accepts doctors does not establish that it accepts your particular income structure.
Surgeon home loan options at a glance
These are lender-selection profiles, not separate products or a ranking of named banks. Each profile addresses a different application problem.
| Rank and lender profile | Best for | Standout assessment focus | Key limitation |
|---|---|---|---|
| 1. Salaried-income fit | Surgeons relying on employment earnings | Salary, allowances and employment evidence | Private earnings need separate assessment |
| 2. Mixed-income fit | Surgeons combining hospital work and private billings | Multiple income sources without double counting | Not every component receives identical treatment |
| 3. Private-practice fit | Self-employed surgeons and practice owners | Business earnings and personal access to income | Business liabilities and documentation add complexity |
| 4. Limited-equity fit | Surgeons prioritising deposit or equity requirements | Confirmed medical-professional and security eligibility | A concession does not establish affordability |
| 5. Complex-ownership fit | Surgeons borrowing through companies or trusts | Borrower, ownership and security alignment | Professional tax and legal advice remains necessary |
1. Salaried-income fit: best for employed surgeons
A salaried-income lender profile suits a surgeon whose borrowing depends principally on documented employment earnings. Start with the employment contract and payslips, then separate base salary from overtime, on-call payments and allowances.
The assessment question is whether the lender accepts the earnings you actually receive. Do not assume that a payslip total automatically becomes assessable annual income.
Salaried-income fit pros:
- Gives a clear starting point when salary is your main income source.
- Connects the application to employment records you can identify early.
- Lets you compare treatment of variable pay separately from base salary.
Salaried-income fit cons:
- Does not resolve how private-practice earnings will be assessed.
- A new contract or changed employment arrangement requires its own review.
Best for: Employed surgeons whose regular salary supports the proposed repayments.
Before selecting this profile in 2026, ask which payslip components count and what evidence supports them. Confirm how the lender treats probation, fixed-term employment or a recently changed role where relevant.
Verdict: Hold until the lender confirms which employment earnings it accepts.
2. Mixed-income fit: best for hospital and private earnings
A mixed-income lender profile suits surgeons combining employment income with private billings or other professional earnings. The priority is a clear reconciliation between income sources, expenses and the money available for personal repayments.
Keep hospital salary separate from practice revenue. Gross billings are not the same as personal income after business expenses.
Mixed-income fit pros:
- Addresses the full income structure rather than salary alone.
- Makes the treatment of private earnings an explicit comparison point.
- Helps identify overlapping income entries before submission.
Mixed-income fit cons:
- Requires records that connect business activity to personal earnings.
- Different income components can require different assessment methods.
Best for: Surgeons whose borrowing depends on both hospital employment and private work.
Prepare a plain-language explanation of who pays each income stream, where it appears in your records and which expenses relate to it. Ask the lender to identify the accepted amount for each component rather than providing only a combined borrowing estimate.
Verdict: Hold until salary, private earnings and associated expenses reconcile.
3. Private-practice fit: best for self-employed surgeons
A private-practice lender profile suits surgeons whose main earnings come through their own business. Assessment needs to connect business performance, ongoing commitments and the income available to the borrower.
A strong revenue figure alone does not answer that question. Start by separating practice turnover, business profit and personal drawings or distributions.
Private-practice fit pros:
- Centres the assessment on the business behind your earnings.
- Brings business debts and ongoing expenses into the discussion early.
- Supports a direct comparison of required financial evidence.
Private-practice fit cons:
- Business changes need explanation and supporting records.
- Drawings alone do not establish sustainable assessable income.
Best for: Established private-practice surgeons and surgeons transitioning into self-employment.
Use the self-employed home loan lender guide to prepare questions about business-income assessment. Keep the application specific to your practice rather than assuming a general self-employed policy settles every issue.
For a 2026 application, identify the financial periods the lender requires before arranging documents with your accountant. Confirm how recent changes affect the assessment.
Verdict: Hold until business earnings and personal repayment capacity are documented.
4. Limited-equity fit: best for deposit-focused borrowers
A limited-equity lender profile suits surgeons for whom deposit size or existing equity is the main constraint. Ask whether a medical-professional policy applies, then confirm its conditions against the proposed property and application.
Lenders mortgage insurance, or LMI, protects the lender rather than the borrower. A waiver addresses that insurance requirement; it does not establish that the repayments are affordable.
Limited-equity fit pros:
- Focuses the comparison on the constraint affecting your purchase or refinance.
- Separates medical eligibility from general product features.
- Makes valuation and security conditions part of the initial discussion.
Limited-equity fit cons:
- Medical registration alone does not confirm eligibility for a concession.
- Lower equity leaves less room for changes in property value.
Best for: Surgeons needing a clear assessment of deposit, equity and medical-policy eligibility.
For illustration, a 90% loan-to-value ratio leaves 10% equity before transaction costs or other secured borrowing. An 80% loan-to-value ratio leaves 20% equity on the same simplified basis. These percentages explain the relationship; they are not eligibility promises or recommended borrowing targets.
Verdict: Hold until the lender confirms eligibility, valuation and repayment assessment.
5. Complex-ownership fit: best for company or trust structures
A complex-ownership lender profile suits surgeons considering borrowing involving a company, trust or other ownership arrangement. The first task is to establish who owns the property, who borrows and who provides security or guarantees.
This is not a structure to choose solely because a loan appears attractive. Tax, legal and estate-planning considerations require advice separate from mortgage selection.
Complex-ownership fit pros:
- Brings borrower and ownership questions forward before submission.
- Makes guarantees and security obligations explicit comparison points.
- Helps identify which entity documents the application needs.
Complex-ownership fit cons:
- More parties and documents increase application complexity.
- Lender acceptance does not establish tax or legal suitability.
Best for: Surgeons whose proposed ownership structure extends beyond borrowing personally.
Ask your accountant and solicitor to explain the intended structure, then have the lending requirements checked against it. Read guarantee obligations carefully. Do not assume a guarantee is limited to the amount you informally expect to contribute.
Verdict: Wait until ownership, borrowing and guarantee responsibilities are clear.
How the ranking works
The order starts with employment income, then moves through mixed earnings, business income, limited equity and complex ownership. Each profile addresses a distinct assessment issue using the same criteria: income, evidence, eligibility, security, flexibility and approval conditions.
This is a ranking of fit, not a claim that one lender approves every surgeon. Move directly to the profile matching your situation; fifth in the table is not fifth-best for a borrower who needs that structure.
For your 2026 shortlist, compare lenders against the same proposed loan and documents. Changing the assumptions between comparisons makes the answers harder to use.
Turn your shortlist into an application
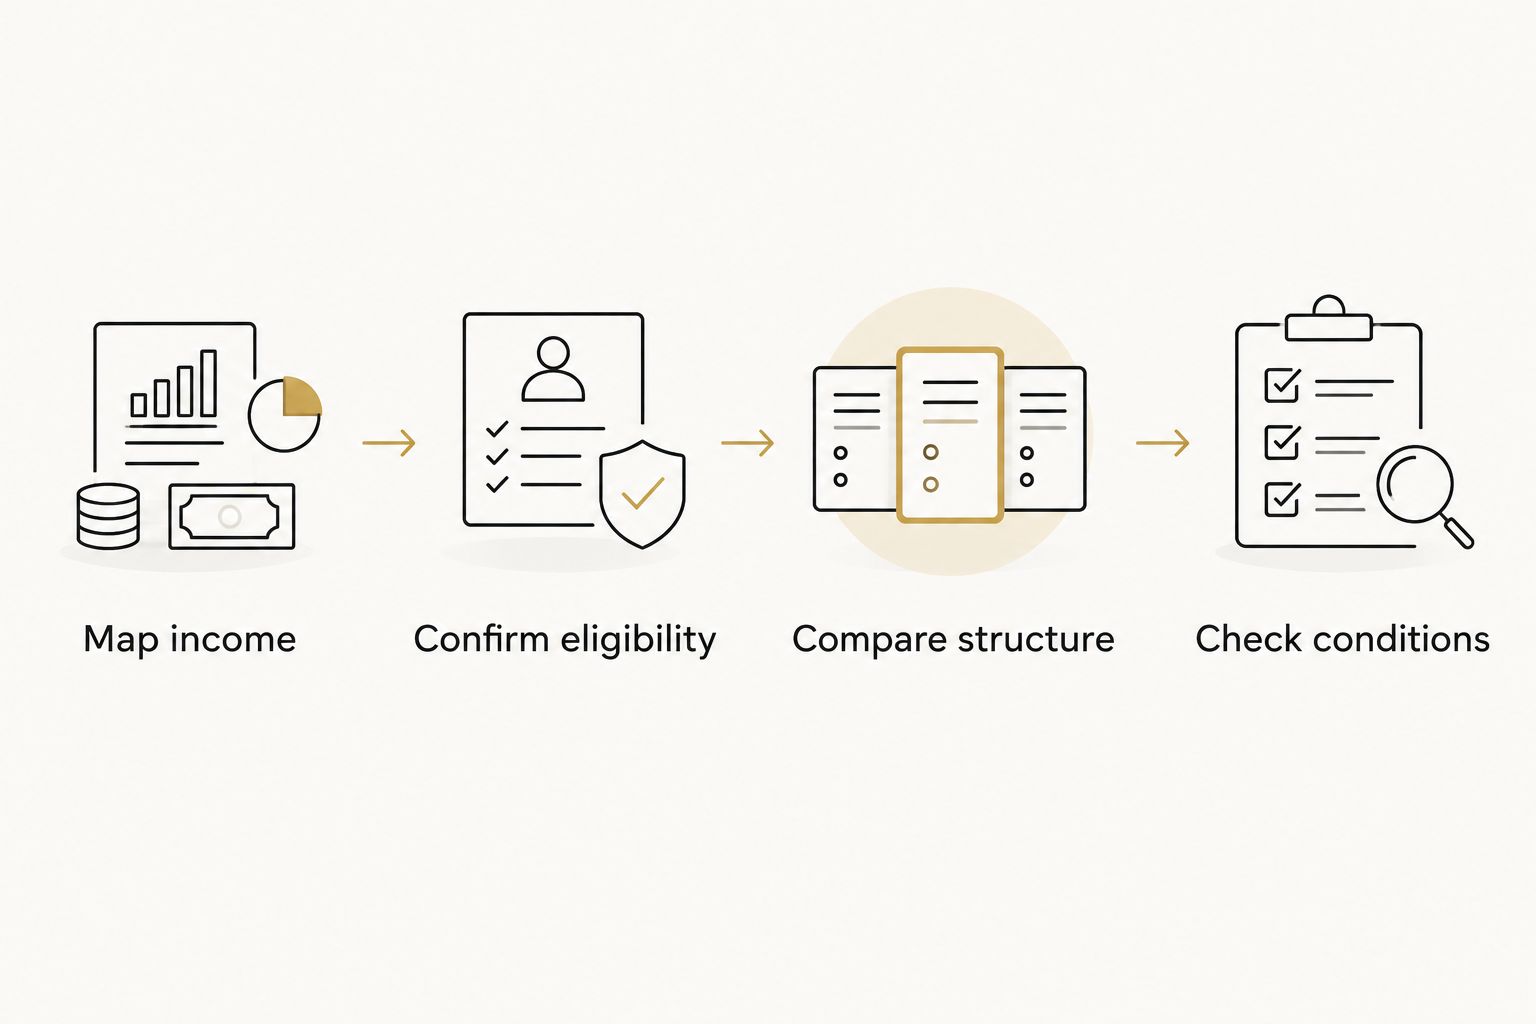
Use this sequence before committing to a lender:
- Map income: Separate salary, variable pay, private earnings and business distributions. Identify the records supporting each source.
- Confirm eligibility: Check medical-professional criteria, employment requirements and property acceptance against your application.
- Compare structure: Review repayment type, offset access, redraw rules and any restrictions relevant to how you manage cash.
- Check conditions: Identify outstanding evidence, valuation requirements and approval conditions before relying on the outcome.
This sequence keeps eligibility and affordability ahead of optional features. An offset account deserves consideration, but it cannot repair an application built on income the lender does not accept.
Ask Mortgage Pros to review your employment or practice structure before choosing which lender to approach. Explain whether you are buying, refinancing or investing, and identify any deadline affecting the application.
Discuss your surgeon home loan today
Explain your income, deposit and borrowing plans to a mortgage broker.
Which lender profile should you choose?
Start with salaried-income fit if employment earnings support the loan. Choose mixed-income fit when hospital and private earnings both matter, or private-practice fit when business income drives the application.
Treat limited equity and complex ownership as additional filters where relevant. A private-practice surgeon buying through a trust needs both business-income assessment and ownership acceptance—not a choice between them.
The practical next move in 2026 is to request an assessment against your actual documents. Ask which income counts, which conditions remain and why the proposed structure suits your plans.
FAQ
What’s the best home loan lender for a surgeon in Australia?
The best lender is one whose income, security and eligibility requirements fit the surgeon’s application. Salaried surgeons, private-practice owners and borrowers using trusts need different assessment questions answered before choosing.
Can surgeons qualify for a home loan without lenders mortgage insurance?
Eligibility for an LMI waiver depends on the lender’s current medical-professional policy and the application. Confirm the conditions for your registration, borrowing, property and income before relying on a waiver.
Will a lender count my private billings alongside my hospital salary?
The lender must assess the private earnings separately from hospital salary. Provide records showing the income, related expenses and amount available to you personally; gross billings alone do not establish assessable income.
What documents should a self-employed surgeon prepare?
Prepare the business and personal financial records the proposed lender requires. Confirm the required reporting periods and entity documents before asking your accountant to assemble the application records.
Does a surgeon’s high income guarantee home loan approval?
High income does not guarantee approval. The lender also assesses expenses, existing debts, credit history, evidence and the proposed security.
Is an offset account the same as redraw?
An offset account and redraw are different features. An offset account is a separate account linked to the loan, while redraw gives access to eligible extra repayments subject to the loan’s rules.
Should I use a mortgage broker or apply directly to a bank?
Use a broker if you want help comparing lender fit and preparing the application; apply directly if you prefer to manage a particular lender’s process yourself. Mortgage Pros provides home loan advice and approval support for surgeons, while the lender makes the credit decision.
One last thing
Your professional title identifies your occupation; it does not explain your income. A short, accurate income summary is a useful starting point: identify each payer, the receiving person or entity, and the supporting record.
Contact us today to discuss that summary and your borrowing plans before choosing a lender.
Related guides
- Best home loan lenders for doctors
- Best offset home loan accounts
- Private banking home loans for high earners