Locum doctors can document home loan income by matching their working arrangement to the evidence: payslips and employment records for PAYG work, or tax returns, financial statements and business records for self-employed work. Support those records with bank statements and contracts that explain where your income comes from, while recognising that each lender decides which earnings it accepts and how it assesses continuity.
- Home loans for locum doctors require income evidence that matches PAYG employment, self-employment or a combination of both.
- Match payslips or invoices to bank deposits, and explain gaps between assignments.
- Separate earned income from reimbursements, business turnover and transfers between your own accounts.
- Mortgage Pros specialises in doctor home loans; request an assessment before choosing a lender.
How can locum doctors document income for a home loan?
Build a traceable record from your work agreement to your payment records and bank deposits. A contract explains the engagement; payslips or business records show earnings; bank statements show the money received. These documents serve different purposes, so one does not automatically replace another.
For your 2026 application, start by identifying how each hospital, practice or agency pays you. Receiving money through an agency does not, by itself, establish whether you are an employee or a contractor. Check the arrangement rather than relying on your job title.
Mortgage Pros provides mortgage-broking support for doctors. Ask for the intended lender's document checklist before gathering records, so your application addresses the assessment requirements from the outset.
| Income arrangement | Evidence to prepare | What it helps explain | Limitation | Best for |
|---|---|---|---|---|
| PAYG locum employment | Payslips, employment agreements, income statements and bank statements | Employer, pay components and earnings received | A recent payslip alone does not explain earlier gaps | Doctors paid as employees |
| Self-employed locum work | Tax returns, notices of assessment, financial statements, contracts, invoices and bank statements | Business income, expenses and personal income | Business receipts are not the same as personal earnings | Doctors operating a locum business |
| Mixed employment and contracting | Separate evidence for each income stream, with a combined summary | How different sources contribute to total income | Overlapping records create a risk of double counting | Doctors combining salaried and invoiced work |
These are preparation categories, not a promise that every listed document will be required or sufficient. Confirm the checklist for your circumstances before submitting an application.
Why this matters
Locum work can produce an uneven payment pattern even when you remain professionally active. Different payers, delayed invoice payments and breaks between placements need an explanation that the lender can check against your records.
The goal is not to make variable income look like a fixed salary. Show what you earned, how you earned it and what evidence supports its continuation. That gives the lender a clearer basis for assessing repayment capacity without treating your strongest assignment as your normal income.
PAYG locum doctors: document employment and pay components
If your locum work is paid through payroll with tax withheld, begin with payslips and the agreements governing your employment. Include records from each employer whose income you want assessed. A payment from a hospital and a payment from an agency should remain identifiable throughout the file.
Check that your documents consistently show your name, employer and pay periods. Where an agency's trading name differs from the name appearing on your bank statement, provide supporting records that connect them.
Separate the components of your pay:
- Ordinary earnings: identify the hours or salary covered by each payslip.
- Additional earnings: distinguish overtime, penalties and other variable payments from ordinary pay.
- Allowances and reimbursements: show what each payment covers rather than treating every deposit as wages.
- Employment conditions: include relevant contract terms, such as engagement dates and the basis of employment.
The strength of PAYG evidence is its direct record of employment payments. Its limitation is that a short snapshot does not establish a longer earnings pattern. Ask which historical records the lender needs alongside your current payslips.
Self-employed locum doctors: connect turnover to personal income
If you invoice for your work, prepare a file that explains both the business activity and the income available to you personally. An invoice shows an amount billed; it does not prove that the amount was received or that it represents profit.
For a 2026 application, organise the tax and accounting records requested by the lender. Depending on your structure and the assessment pathway, those records can include personal and business tax returns, notices of assessment, financial statements and business activity statements.
Keep invoices, remittance records and business bank statements together. These help connect the work performed to payments received and provide context when tax records cover an earlier period.
If you operate through a company or trust, explain the structure and distinguish business revenue from salary, distributions or other amounts paid to you. Do not present company turnover or drawings as personal salary. Ask your accountant to clarify entries that need explanation, and have your broker confirm how the lender will assess them.
The strength of business records is the view they provide of income and expenses. Their limitation is that completed tax periods do not, on their own, explain every recent change in trading.
Mixed-income doctors: keep the evidence streams separate
If you combine a salaried hospital position with contracted locum shifts, prepare separate records before combining the totals. Label each source by payer, payment method and the period it covers.
This prevents the same income appearing twice. For example, an amount recorded in business revenue must not be added again simply because it was later transferred into your personal account.
Use a summary to explain the file, not replace it. Every amount should connect to an underlying document, and your summary should distinguish historical earnings from future bookings.
A mixed-income application needs more organisation, but it also gives the lender a clearer picture of your work. Keep the stable employment component visible rather than blending all deposits into an unexplained total.
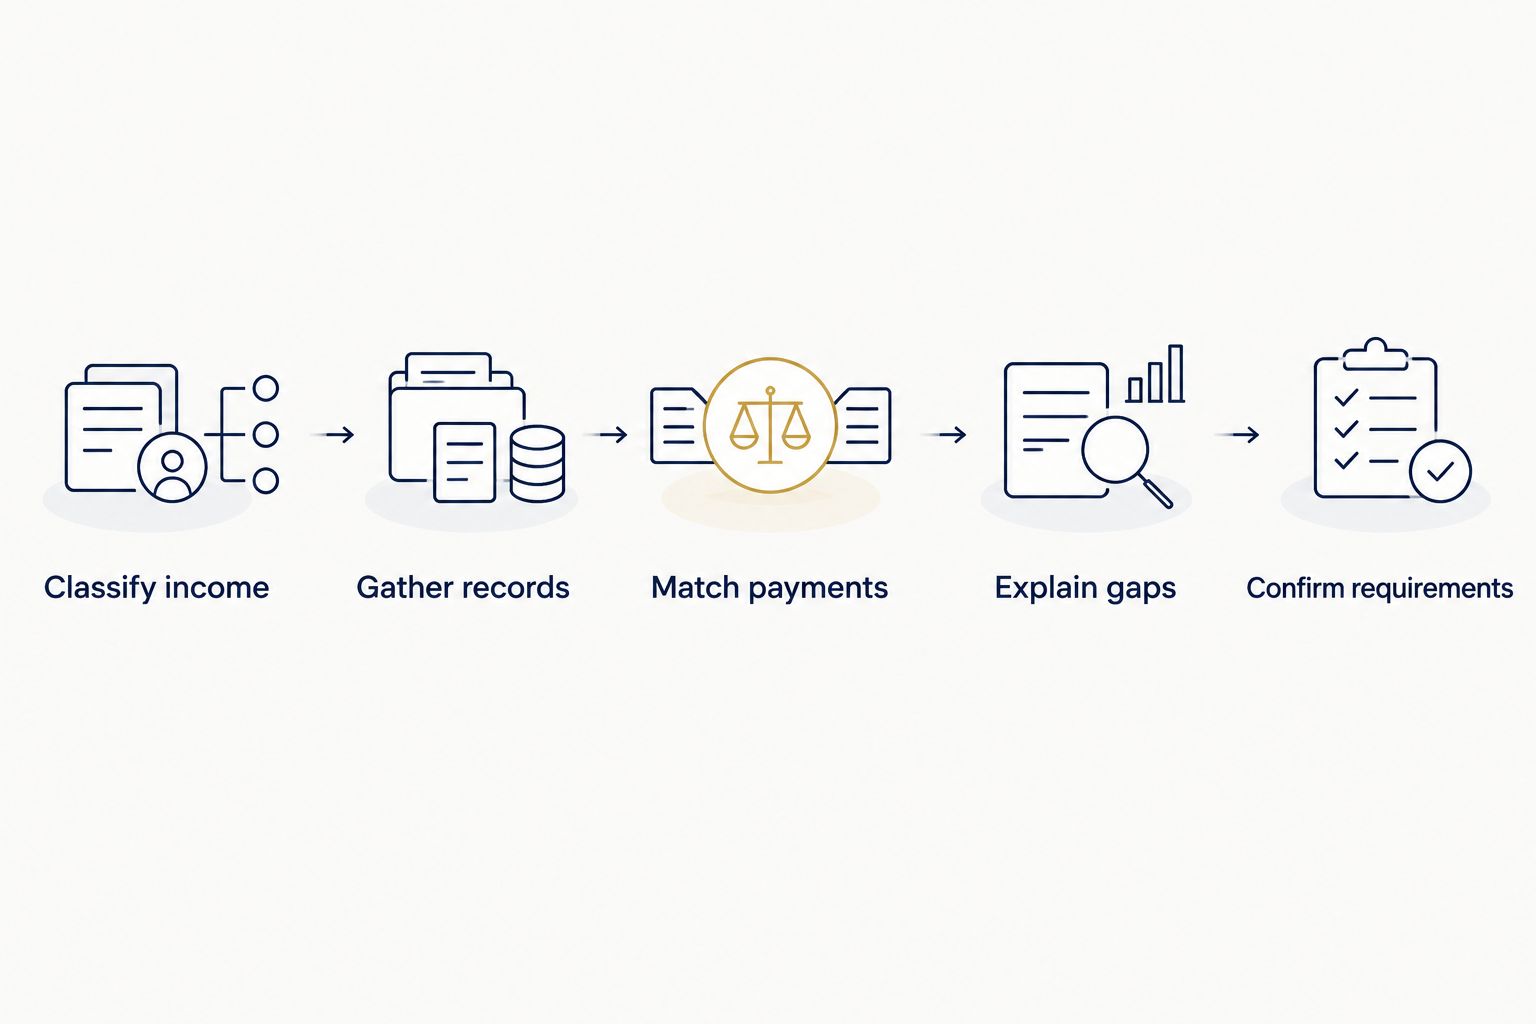
Prepare your locum income evidence in order
Use this sequence to organise your 2026 application before a lender submission. It helps you identify inconsistencies while there is still time to resolve them.
- Classify income. List each payer and identify whether the work is PAYG employment or self-employment. Use contracts, payslips and accounting records to establish the arrangement.
- Gather records. Collect the documents requested for each income stream. Include complete statements and supporting pages rather than cropped screenshots that omit account details or dates.
- Match payments. Connect payslips or paid invoices to deposits. Where deductions, combined payments or timing differences prevent an exact match, keep the records explaining the difference.
- Explain gaps. Prepare a dated work history showing assignments and breaks. Distinguish time away from work from time spent working while awaiting payment.
- Confirm requirements. Ask the broker to check the lender's treatment of your income, the required evidence period and any outstanding documents before submission.
Keep an index at the front of your document folder. Name files by document type, payer and covered period so a reviewer can follow the sequence without guessing which records belong together.
Do not alter source documents to make them agree. If an employer name, accounting entry or payment amount needs correction, obtain a corrected record or a written explanation from the relevant party.
Why income documentation requirements vary
The documents needed for home loans for locum doctors depend on the income being assessed and the lender's policy. A professional qualification establishes your occupation; it does not replace financial evidence.
Discuss these factors before selecting an application pathway:
- Employment arrangement: payroll income and invoiced business income need different supporting records.
- Length of the available history: recent locum work provides a different evidence base from an established record of assignments.
- Income variability: changing hours, additional shifts and irregular payments need to be separated and explained.
- Business structure: sole-trader, company and trust arrangements affect which records explain your personal income.
- Changes in work: a move between permanent employment and contracting requires context about both the previous and current arrangement.
- Lender assessment policy: the lender determines which income components it accepts and what evidence supports them.
Choose the assessment pathway before treating any document list as final. A well-organised file does not override lending policy, but it makes the relevant facts easier to assess.
Can future locum contracts support a home loan application?
Future locum contracts provide evidence of scheduled work, but they are not proof of income already earned. Keep signed agreements separate from historical payment records so the distinction remains clear.
Provide the engagement dates, agreed payment terms and relevant conditions. Ask whether the lender accepts that evidence for your circumstances; do not convert an unworked booking into received income in your summary.
A contract also needs context. A continuing relationship with a payer and an isolated future booking describe different situations, even if the quoted work terms look similar.
How should locum doctors explain gaps between assignments?
Explain gaps with a dated work history supported by contracts, payslips, invoices and payment records. State whether the gap reflects leave, a change of employer, time between placements or delayed payment for completed work.
Keep the explanation factual. If you have resumed work, attach the records showing that resumption rather than relying on a statement that your income will recover.
What should you ask a doctor mortgage broker before applying?
Ask how the proposed lender will classify your locum work, which earnings it will assess and which records remain outstanding. Also ask whether the income used in the assessment differs from the total shown on your summary.
Mortgage Pros is best suited to doctors seeking specialist home-loan broking support rather than applying directly to a lender. Its role is mortgage broking, not the lender's final credit decision. For home loans for locum doctors, use that support to clarify the evidence pathway before committing to an application.
Send your employment structure, recent income records and work history for an initial discussion. Contact the team today to establish the next step for your circumstances.
Discuss your locum home loan
Ask Mortgage Pros to assess your income structure and explain the documents needed for your application.
FAQ
Can I get a home loan if I work as a locum doctor?
Locum work does not automatically prevent a home loan application. You still need to meet the lender’s income, repayment-capacity and other credit requirements, using evidence that matches your employment or business arrangement.
Do locum doctors need tax returns for a home loan?
Self-employed locum doctors should prepare tax records for assessment, while PAYG doctors generally start with employment and payroll evidence. Confirm the actual document requirements with the proposed lender before submitting.
Are bank statements enough to prove my locum income?
Bank statements alone do not explain whether deposits are wages, business receipts, reimbursements or transfers. Pair them with the employment or business records that identify the source and nature of the payments.
Can I use income from different locum agencies?
Present each agency’s income separately with its supporting employment or business records. The lender decides which income it accepts, and your summary must avoid counting the same earnings twice.
Will a lender accept overtime and penalty payments?
Acceptance of overtime and penalty payments depends on the lender’s assessment policy and your supporting history. Separate these amounts from ordinary earnings so the lender can assess them correctly.
Should I apply before completing my first locum assignment?
Discuss your circumstances before submitting an application, particularly if your evidence consists mainly of future contracts. A signed booking does not establish received income or guarantee lender acceptance.
What should I prepare for a locum home loan enquiry in 2026?
For a 2026 locum home loan enquiry, prepare an outline of your employment structure, income sources and work history, together with available supporting records. Mortgage Pros can discuss your doctor home loan needs and the next steps for assessing your circumstances.
One last thing
The payment date is not necessarily the date you earned the income. An invoice paid after a break between assignments can make your bank statements tell a different story from your work history.
Before submitting your 2026 application, check that both timelines agree with your explanation. Then request an assessment using the complete evidence file, rather than asking a lender to interpret unexplained deposits.
Related guides
- Best home loan lenders for doctors
- Best lenders for self-employed home loans
- Home loans for company directors: complete guide