Home loans for anaesthetists are mortgages assessed against your medical income, financial commitments and property plans, with the aim of financing a home or investment you can afford. This 2026 guide explains how to prepare an application when your earnings include hospital salary, on-call work, locum engagements or private practice income.
- Mortgage Pros suits anaesthetists seeking broker support with doctor home loans and complex income assessment.
- Home loans for anaesthetists require evidence of assessable income, not just a medical qualification or headline earnings.
- Compare lender eligibility, repayment flexibility and total loan costs before choosing a mortgage.
- Keep property selection separate from credit approval, and confirm finance conditions before committing.
Why home lending matters for anaesthetists
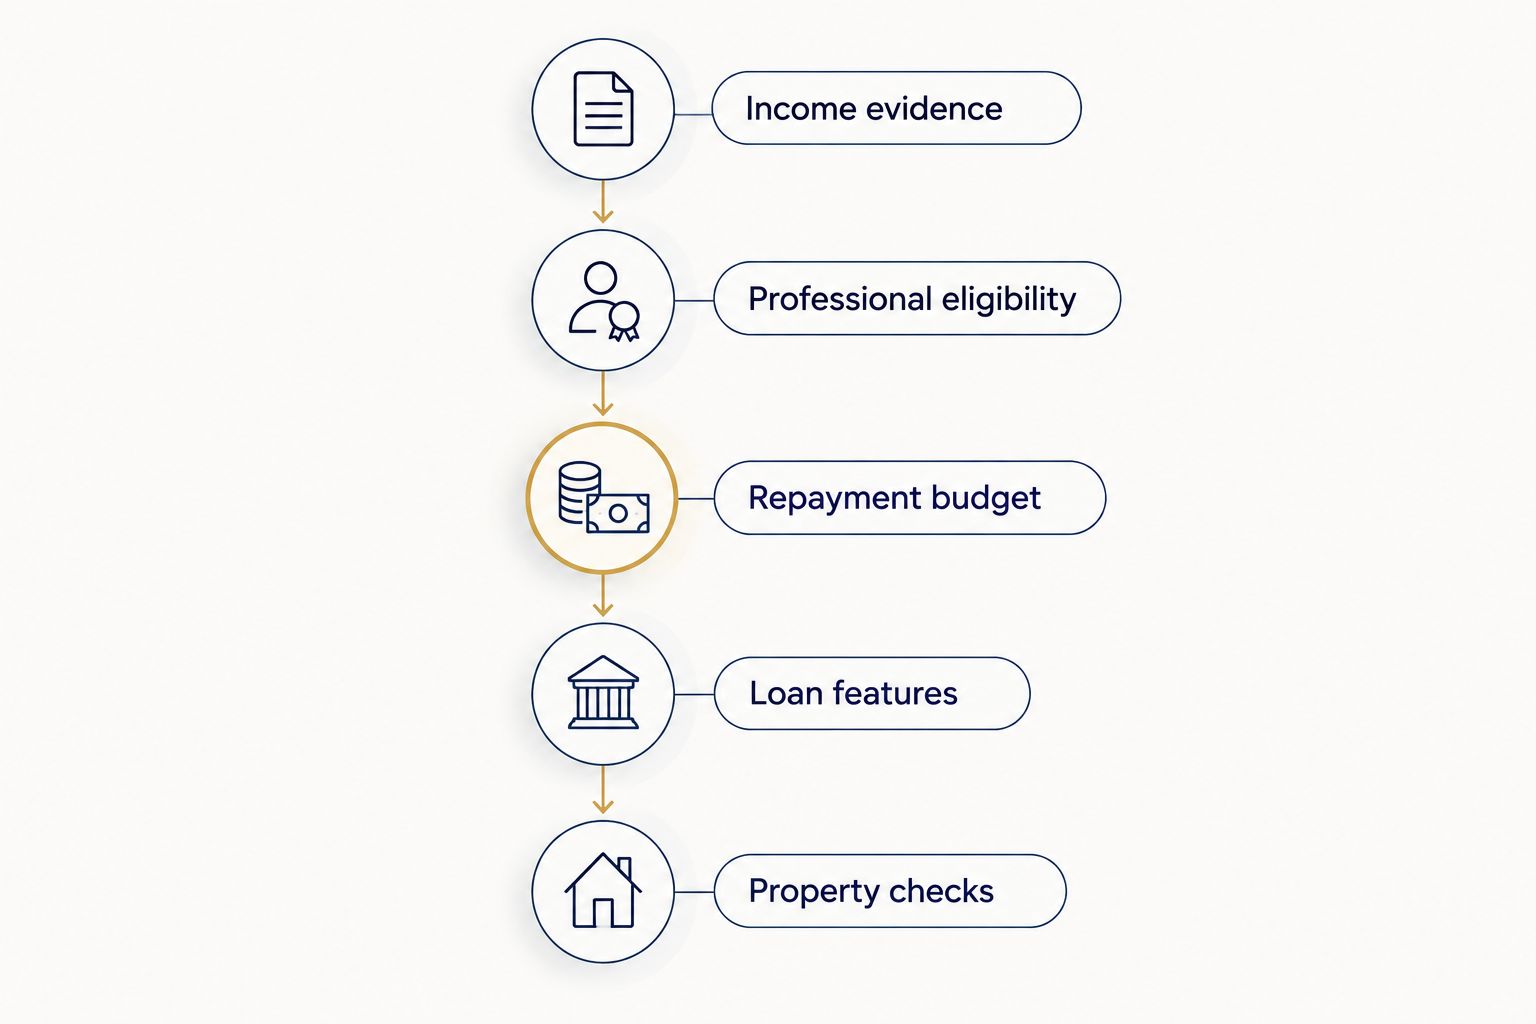
The strongest application explains how your income is earned, how consistently it arrives and what remains after your commitments. A salary, private billings and locum receipts are different evidence streams; combining them into one annual total hides information a lender needs.
The distinction matters when you move between public employment and private work, change hospitals or buy while building a practice. A qualification does not remove the need to demonstrate repayment capacity.
For your 2026 application, use the broader doctor home loan lender guide to frame your shortlist, then test each option against your actual employment structure. A professional lending policy is relevant only if you meet its current conditions.
How to prepare your anaesthetist home loan application
Establish your borrowing brief
Start with a document or spreadsheet rather than a loan application. Record whether you are buying a home, purchasing an investment, refinancing or accessing equity, because the purpose affects the questions your lender must answer.
Separate your preferred purchase budget from your comfortable repayment budget. Borrowing capacity is an assessment outcome, not a spending target, and a demanding roster does not make an uncomfortable repayment easier to carry.
Include changes you already know about, such as parental leave, a fellowship, reduced hospital hours or practice establishment. Your brief should describe the household that will repay the loan, not just your current payslip.
- State the property purpose and intended ownership.
- Set a repayment ceiling using your household budget.
- Record your deposit and funds reserved for transaction costs.
- List expected employment or household changes.
- Identify your intended purchase or refinance timing.
Separate your income streams
Build a 12-month income summary as a preparation exercise, not as a universal lender documentation requirement. Separate hospital salary, recurring allowances, overtime, locum receipts and private practice earnings so each source can be checked independently.
For private work, distinguish gross billings from money remaining after business expenses. If a company or trust receives income, explain how that money reaches you; entity revenue and personal income are not interchangeable.
For a 2026 application, ask the lender which earnings it accepts and which documents support that treatment. Mortgage Pros is best suited to anaesthetists seeking broker support with doctor home loans. Its role is mortgage advice and approval support, not an exemption from lender assessment.
- Match salary entries to payslips and employment documents.
- Label overtime and on-call earnings separately.
- Reconcile locum receipts with contracts and bank credits.
- Separate practice turnover, expenses and personal drawings.
- Explain discrepancies between tax records and current earnings.
Assemble evidence before choosing a lender
Create folders for identity, employment, income, liabilities and deposit evidence. You can do this yourself using existing records; ask for a lender-specific checklist before ordering extra documents or paying for professional work.
If your circumstances are complex, Mortgage Pros can help you work through the application and approval process. The practical benefit is advice on presenting your circumstances; the limitation is that a broker cannot guarantee acceptance or change a lender's credit decision.
Keep your accountant involved where business income needs explanation. An accurate account of your current work is more useful than submitting a large collection of unexplained statements.
- Gather identity and professional registration evidence.
- Include employment contracts and current payslips.
- Collect relevant tax returns and notices of assessment.
- Prepare business financials where applicable.
- Document savings, gifts or other deposit sources.
- Explain recent changes in employment or business structure.
Test repayments against your real spending
Complete a 30-day spending review, then check it against less frequent expenses such as insurance, registration and professional costs. A short review captures daily behaviour, but annual statements are needed to identify bills that fall outside that window.
Build a separate budget for a quieter income period. Use an actual reduced-hours scenario or planned leave arrangement rather than assuming your busiest roster will continue throughout the loan.
Also identify the cash you want available after settlement. A planning exercise using 3 months of essential expenses can reveal your reserve needs; it is not a lender rule or a substitute for advice about your circumstances.
- Separate household spending from practice expenses.
- Include existing debts and ongoing financial commitments.
- Add known annual bills to your monthly budget.
- Test repayments against a lower-income scenario.
- Keep a settlement reserve separate from your deposit.
Check professional eligibility and loan features
Ask each shortlisted lender whether it has a medical-professional policy and whether your exact circumstances qualify. Specialist registration, employment structure, residency status, property type and borrowing purpose are matters to clarify, not assumptions to make.
If a lender offers a lenders mortgage insurance concession, obtain the conditions in writing. Lenders mortgage insurance protects the lender, not the borrower, and a concession does not establish that the whole loan is suitable.
For your 2026 comparison, consider how you will use the loan after settlement. An offset account, redraw access or repayment flexibility matters only when the feature works with your cash flow and its associated terms.
- Confirm eligibility for any professional lending policy.
- Ask how each income source enters the assessment.
- Compare interest arrangements and ongoing fees.
- Check offset, redraw and extra-repayment conditions.
- Review restrictions associated with fixed-rate borrowing.
- Confirm property and borrowing-purpose requirements.
Compare application routes before committing
You can approach a lender directly, compare options yourself or use a mortgage broker. Start by recording the same questions for every route so you compare actual assessment criteria rather than the quality of a sales conversation.
Ask a broker which lenders are being considered and why they fit your income structure. Ask a direct lender how it treats mixed employment and private practice income. Neither route removes the need to disclose liabilities or substantiate earnings.
Keep a written comparison showing the reasons for inclusion and rejection. A lender that recognises your profession still needs to suit your repayment budget, property plans and preferred features.
- Record the income assumptions behind each assessment.
- Ask which lender options are being considered.
- Confirm who will coordinate supporting documents.
- Request an explanation of fees and remuneration.
- Compare restrictions as well as benefits.
Coordinate property checks and finance conditions
Before making an offer, establish what your finance position actually means. Conditional approval, an indicative borrowing estimate and final approval are different stages; read the conditions attached to any lender communication.
Keep the property purchase process separate from loan selection. Using Adelaide buyer’s agents for busy professionals does not replace mortgage assessment: property search and negotiation are separate tasks from proving that the proposed loan meets a lender's requirements.
Ask your conveyancer or solicitor to explain the contract, finance conditions and relevant deadlines before you sign. For an auction purchase, obtain advice about the contractual commitment rather than assuming an earlier lending conversation protects you.
- Confirm outstanding approval conditions with the lender.
- Check whether the proposed property needs further assessment.
- Have the contract reviewed before committing.
- Clarify finance deadlines and settlement responsibilities.
- Keep your broker informed of employment or debt changes.
Compare your home loan application options
Choose the route that can explain your income clearly and answer your questions before you submit. A straightforward salary-only application and a mixed public/private application do not need the same preparation.
The table compares application routes, not named loan products. None guarantees approval, and none replaces your responsibility to check the proposed repayments and contractual terms.
| Option | Best for | Main benefit | Key limitation |
|---|---|---|---|
| Direct lender application | Anaesthetists with straightforward income and a preferred lender | Direct discussion of that lender's policy and process | The conversation covers that lender's products, not the wider market |
| Independent comparison | Borrowers comfortable researching policies and organising evidence | Control over your shortlist and comparison questions | Public product information does not establish how your income will be assessed |
| Mortgage Pros mortgage broking | Anaesthetists seeking doctor home loan advice and application support | A service focused on home loan advice and approval support, including medical borrowers | Advice does not guarantee approval; ask which lenders are being considered |
A comparison is incomplete until you know why an option was selected. Request a plain-English explanation of income treatment, loan structure and the conditions you must satisfy, rather than relying on a favourable headline alone.
Discuss your anaesthetist home loan
Explain your hospital, locum or private practice income and discuss your next application steps.
Common mistakes anaesthetists make
Treating professional status as automatic approval
Being an anaesthetist does not establish serviceability, acceptable security or eligibility for a particular policy. Ask which professional benefits apply to your circumstances, then check the remaining approval requirements separately.
Correct move: obtain written confirmation of the relevant eligibility conditions before relying on a concession in your purchase plan.
Presenting private billings as personal earnings
Practice receipts do not show the amount available for home loan repayments. Business expenses, ownership arrangements and how you receive income all need to be explained where relevant.
Correct move: reconcile business records with your personal income evidence and ask your accountant to clarify any structural complexity.
Budgeting around an unusually busy roster
A period containing additional shifts or substantial on-call work is not a complete picture of your household finances. A loan still needs to work during planned leave, quieter periods or a change in working arrangements.
Correct move: compare your repayment budget with the income you expect to retain under a realistic reduced-work scenario.
Choosing a feature without checking its conditions
An offset account and redraw are not interchangeable. Their operation, access conditions and implications differ; investment-related borrowing also warrants tax advice before you move money or restructure debt.
Correct move: describe how you intend to hold and use cash, then ask which loan structure supports that plan.
Changing commitments during assessment
New borrowing or a material employment change can alter the circumstances on which an assessment was based. Do not assume an approval discussion remains current after you change jobs, take on debt or restructure your practice.
Correct move: tell your lender or broker about material changes immediately and confirm whether reassessment is required.
FAQ
What’s the best home loan for an anaesthetist?
The best home loan for an anaesthetist fits their assessable income, repayment budget, deposit and property plans. Compare professional eligibility and loan conditions rather than choosing solely on occupation-based benefits.
Can anaesthetists qualify for a lenders mortgage insurance waiver?
Eligibility for a lenders mortgage insurance waiver depends on the lender’s current policy and your circumstances. Ask whether your professional status, employment structure, borrowing amount and property meet the relevant conditions.
Can I use hospital salary and private practice income together?
A lender needs to assess each income source before deciding what it will accept. Provide separate evidence for hospital employment and private practice earnings, with business expenses and ownership arrangements clearly explained.
How do I apply while moving into private practice?
Explain the transition before selecting a lender and establish which evidence it requires. Employment history, current contracts and business records should tell a consistent story about the change.
Is a mortgage broker better than applying directly?
A mortgage broker suits borrowers seeking help comparing lender options and preparing an application; applying directly suits borrowers who want to deal with a particular lender. Ask a broker which lenders are being considered, and ask a direct lender how it treats your income structure.
Does pre-approval mean I can buy any property?
No, pre-approval does not mean every property or purchase will receive final approval. Read the conditions and confirm the lender’s requirements for the specific property before committing.
What should I prepare for a home loan enquiry in 2026?
Prepare your borrowing purpose, deposit position, income breakdown, existing commitments and known employment changes. Ask for a tailored document checklist before gathering additional records.
One last thing
Your next career move belongs in your mortgage discussion. A loan assessed around today's hospital roster needs a fresh affordability check if your plan involves fellowship training, leave or building private work.
For your 2026 enquiry, send a short income summary and explain what will change next. Contact Mortgage Pros today to discuss your anaesthetist home loan and the evidence needed for your circumstances.
Related guides
- How locum doctors can document income for a home loan
- How to choose a doctor mortgage broker for complex income
- Compare offset home loan accounts