NAB offers a direct home loan relationship with an established Australian bank. That relationship stops being enough when you need to compare lenders rather than choose within one bank’s range. The best NAB home loan alternative in 2026 is Mortgage Pros if you need broker-led home loan advice; Commonwealth Bank if you want another direct bank relationship.
- For NAB home loan alternatives, choose Mortgage Pros for broker-led advice, including home loans for doctors.
- Commonwealth Bank suits borrowers who want to compare another bank directly with NAB.
- Consider non-bank lenders when their lending criteria fit your circumstances; compare restrictions as well as repayments.
- Keep NAB if its loan remains suitable after comparing features, switching costs and your remaining term.
Why this matters
A different lender is not automatically a better lender. Your home loan needs to fit your income, deposit, property and plans—not just the repayment shown in an advertisement.
For a 2026 comparison, separate two decisions: who helps you choose the loan, and who provides the money. A mortgage broker helps you assess available lending options; a bank or non-bank lender assesses your application and provides the loan. Choosing a broker does not mean choosing a particular lender before your circumstances have been assessed.
This distinction matters if you are buying your first property, refinancing, accessing equity or arranging a guarantor loan. Start with the outcome you need, then compare suitable loan structures and application requirements.
NAB home loan alternatives at a glance
| Option | Best for | Standout distinction | How it differs from NAB |
|---|---|---|---|
| NAB | Borrowers who want to deal directly with NAB | Direct application and loan relationship | The benchmark: assess its proposal against your needs |
| Mortgage Pros | Borrowers seeking home loan advice, including doctors | Mortgage broking and approval support | An adviser rather than the bank providing the loan |
| Commonwealth Bank | Borrowers comparing another bank directly | Another direct bank lending option | A different lender with its own assessment and loan terms |
| Non-bank lenders | Borrowers whose circumstances fit a non-bank loan | Lending outside a bank relationship | A different lending model; assess each lender separately |
Compare a specific loan proposal, not the reputation of an entire bank. Ask each provider to address the same property, borrowing amount, repayment type and intended loan term. Otherwise, differences in the assumptions can disguise differences in the offer.
1. Mortgage Pros: best for broker-led home loan advice
Mortgage Pros is a Sydney-based mortgage broking firm supporting home buyers and property owners across Australia. Its services include refinancing, equity and guarantor arrangements, with a specialisation in home loans for doctors.
The distinction from applying directly to NAB is the advice pathway. You can discuss your borrowing circumstances and the outcome you want before deciding which available lending option to pursue. The lender still makes the credit decision.
Where the broker pathway shines
- Application preparation: discuss your income, existing debts and property plans before submitting an application.
- Loan structure: consider refinancing, equity access or a guarantor arrangement in the context of your wider borrowing needs.
- Doctor home loans: seek advice from a firm with an explicitly stated focus on this borrower group.
- Decision support: compare the suitability of available options rather than treating the bank you already use as the default.
Where the broker pathway falls short
- A broker is not the lender and cannot guarantee approval.
- A broker comparison is not automatically a comparison of every lender in Australia. Ask which lenders and loan types the recommendation covers.
- You still need to provide accurate documents and respond to the lender’s assessment requests.
Broker advice versus a direct NAB application
| Dimension | Mortgage Pros | NAB directly |
|---|---|---|
| Role | Mortgage broker | Bank and lender |
| Starting point | Your borrowing circumstances and advice needs | An application for a NAB loan |
| Final approval | Decided by the selected lender | Decided by NAB |
| Fit to assess | Advice, preparation and available lending options | Suitability of NAB’s proposed loan |
Best for: borrowers who want help assessing home loan options and preparing for approval, particularly doctors seeking relevant advice.
Before engaging a broker, ask how the recommendation will be explained, which lenders will be considered and what fees or commissions apply. You should understand both the proposed loan and the basis for recommending it.
Verdict: Buy into the broker-led advice pathway if you need help choosing; do not treat advice as an approval guarantee.
2. Commonwealth Bank: best for another direct bank comparison
Commonwealth Bank is an alternative when you want to compare NAB with another Australian bank while keeping a direct lender relationship. Request an assessment based on the same borrowing circumstances you give NAB.
The useful comparison is not which bank is better in general. It is which specific proposal better fits your repayment plans, property and financial position.
Where Commonwealth Bank shines
- It gives you another bank proposal to compare with NAB’s.
- You deal directly with the institution assessing and providing the loan.
- It suits borrowers who prefer to handle lender discussions themselves rather than use a broker.
Where Commonwealth Bank falls short
- A direct application considers that bank’s lending options, not alternatives across other lenders.
- A different bank does not remove the need for income, expense and credit assessment.
- Switching banks introduces another application and, for refinancing, discharge and settlement steps.
Commonwealth Bank versus NAB
| Dimension | Commonwealth Bank | NAB |
|---|---|---|
| Provider type | Bank | Bank |
| Direct application scope | Commonwealth Bank loans | NAB loans |
| Credit decision | Commonwealth Bank assesses the application | NAB assesses the application |
| Comparison task | Check the proposed terms against your needs | Check the proposed terms against your needs |
Best for: borrowers who want another direct bank proposal and are comfortable comparing the documents themselves.
For your 2026 shortlist, request written details of the proposed loan features and conditions. Do not assume that an offset facility, extra repayment allowance or redraw arrangement works identically across banks or loan types.
Verdict: Hold Commonwealth Bank on your shortlist until its specific proposal demonstrates a better fit than NAB’s.
3. Non-bank lenders: best for a different lending pathway
Non-bank lenders provide home loans without being banks. This is a category, not a single recommendation: each lender has its own credit criteria, loan structure and servicing arrangements.
Consider this pathway when a particular lender’s requirements fit your circumstances. Do not assume that non-bank lending means easier approval or fewer obligations.
Where non-bank lenders shine
- They add a different lender category to your comparison.
- A suitable lender’s assessment approach can provide another application pathway.
- They let you assess lending separately from your everyday banking relationship.
Where non-bank lenders fall short
- Category labels tell you little about an individual loan’s suitability.
- Features and servicing arrangements need lender-specific checks.
- Approval still depends on the application meeting the lender’s requirements.
| Dimension | Non-bank lender | NAB |
|---|---|---|
| Provider type | Non-bank lender | Bank |
| Assessment | Selected lender’s criteria | NAB’s criteria |
| Everyday banking | Assess separately from the home loan | Assess the bank relationship alongside the loan |
Best for: borrowers with a specific reason to assess a non-bank loan, rather than those looking for an assumed shortcut to approval.
If business income is central to your application, start with the questions in the self-employed home loan lender guide. Focus on income evidence and assessment requirements before submitting applications.
Verdict: Hold non-bank lenders on the shortlist only when a specific loan and its criteria fit your circumstances.
Why people switch from NAB
The sound reasons to consider switching are about your circumstances and the proposed loan—not an unsupported claim that NAB has become unsuitable for everyone.
Your borrowing needs have changed
A loan selected for your first home deserves another assessment when you refinance, buy an investment property or seek equity for another purpose. Explain the new objective before comparing lenders. Existing approval does not establish that a new borrowing request will meet the same criteria.
Your income needs a different assessment
Employment income, business income and multiple income sources require different supporting evidence. Ask how each lender will assess your actual income structure rather than assuming every lender will reach the same result.
Your loan features no longer fit
An offset account, redraw facility and extra repayments are not interchangeable. Identify how you intend to use your cash, then check the proposed loan’s rules. Switching only makes sense if the replacement addresses the specific limitation you have identified.
You want advice before making another application
A direct bank discussion focuses on that lender’s proposal. Broker-led advice gives you a different starting point: your circumstances, suitable available options and application preparation.
For 2026, write down the problem you want a new loan to solve. If you cannot identify it, first review your existing loan rather than assuming refinancing is the answer.
How to compare alternatives without losing sight of your goal
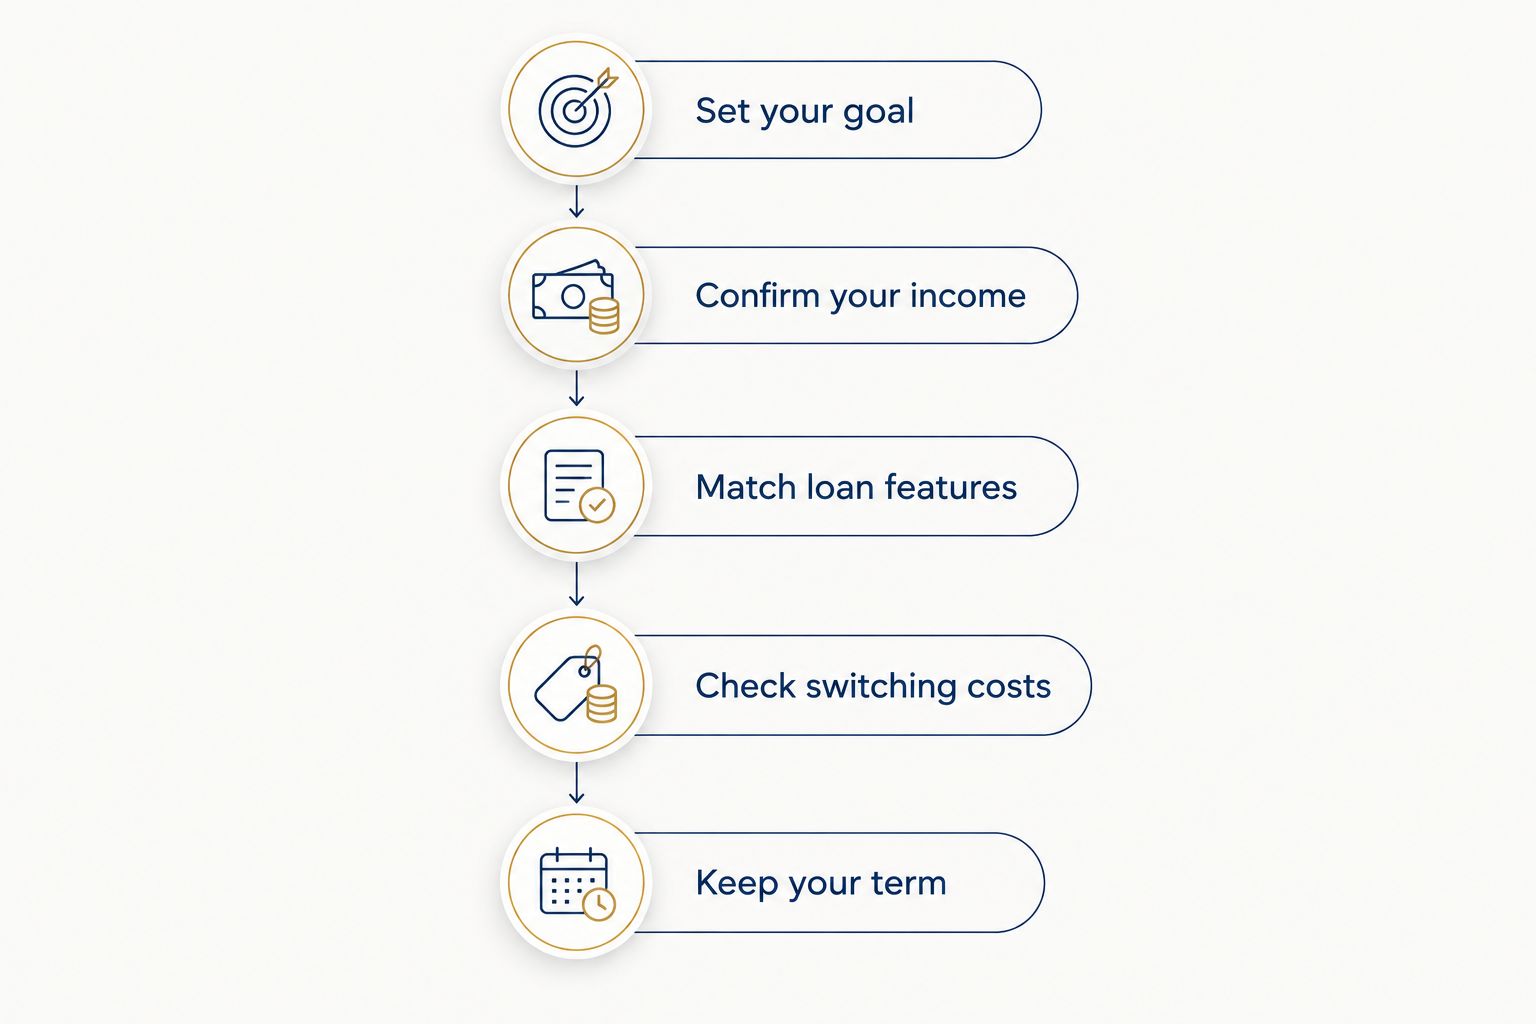
Use the same comparison sequence for NAB, another bank and a non-bank lender. Keep the information consistent so you can distinguish a genuine improvement from a change in assumptions.
- Set your goal: identify whether you need purchase finance, refinancing, equity access or a guarantor arrangement.
- Confirm your income: gather evidence of earnings, existing debts and expenses relevant to the assessment.
- Match loan features: check repayment type, offset, redraw and extra repayment rules against how you will use the loan.
- Check switching costs: account for applicable discharge, establishment, settlement and fixed-rate break costs before deciding.
- Keep your term: compare the remaining term as well as the proposed repayment.
A lower scheduled repayment does not, by itself, establish a better refinancing outcome. For example, replacing a loan with a 25-year remaining term with a new 30-year term adds a 5-year extension to the repayment schedule. That comparison changes the term as well as the loan.
Ask for a comparison that retains your remaining term, then assess any longer-term proposal separately. This keeps repayment relief and debt reduction visible as different objectives.
For a 2026 decision, also distinguish loan approval from settlement. Do not commit to a switching timetable until the application conditions and settlement requirements are clear.
Discuss your home loan options today
Explain your purchase, refinancing or equity goal and ask for advice on your next application.
When staying with NAB is the right call
Stay with NAB if its loan still meets your needs and the alternatives do not justify switching. A suitable existing loan can remain the right choice after a proper comparison.
Ask NAB to review your current arrangement before committing elsewhere. Then compare that response with the alternative proposal on equivalent terms, including features, obligations and applicable switching costs.
For fixed-rate borrowers, check the consequences of ending the fixed period early. For borrowers planning another purchase, consider how refinancing fits that application and settlement timetable.
A 2026 review does not need to end with a new lender. It needs to end with a decision you can explain.
FAQ
What’s the best NAB home loan alternative in 2026?
Mortgage Pros is the best pathway if you want broker-led home loan advice rather than another direct bank application. Commonwealth Bank is an option if you prefer to compare another bank directly; the suitable loan depends on your circumstances.
Is a mortgage broker better than applying to NAB directly?
A mortgage broker suits borrowers who want advice on available lending options and application preparation. Applying directly to NAB suits borrowers who want a NAB loan and are comfortable assessing its proposal themselves.
Can a broker guarantee that my home loan will be approved?
No, a broker cannot guarantee home loan approval. The lender makes the credit decision after assessing your application and supporting evidence.
Are non-bank home loans easier to get than NAB loans?
Non-bank home loans are not automatically easier to obtain. Each lender applies its own criteria, so compare its requirements with your income, debts and property before applying.
Should I refinance if another lender offers a lower repayment?
A lower repayment alone is not enough to justify refinancing. Compare the remaining term, loan features and applicable switching costs to understand what has changed.
Can doctors get advice on alternatives to NAB?
Doctors can seek specialist home loan advice when comparing NAB with other available options. Ask how your income, borrowing purpose and supporting documents will be assessed before choosing an application pathway.
Can I keep my everyday banking with NAB after refinancing?
Your everyday banking and home loan do not have to be with the same institution. Check any account-linking, repayment and offset requirements before changing the home loan.
One last thing
Ask every provider the same question: what does this proposal improve, and what do I give up? That exposes trade-offs a repayment figure cannot show.
Prepare your current loan details, income documents and borrowing goal, then contact us today. Make the next application a deliberate choice—not simply a move away from NAB.
Related guides