Your income alone does not determine how much you can borrow in 2026: your borrowing capacity depends on the income a lender accepts, your expenses, existing debts and the proposed loan repayments. Your deposit and purchase costs also constrain your property budget, so an income-based calculator result is a starting estimate—not an approval or a spending target.
- The answer to how much can I borrow based on my income requires expenses, debts and accepted earnings—not salary alone.
- Home loan borrowing capacity and your property purchase budget are different calculations.
- Doctors should separate base salary, overtime, on-call payments and private practice earnings before seeking an assessment.
- Mortgage Pros provides home loan advice for medical borrowers, including doctors, dentists and surgeons.
How much can I borrow based on my income in 2026?
There is no universal salary multiplier that produces a reliable home loan limit. Two applicants earning the same salary can receive different assessments because their commitments, household expenses and income evidence differ.
For an individual assessment, contact Mortgage Pros with your income breakdown, debts and deposit details. Ask for the assumptions behind the estimate, not just the maximum loan figure.
A useful assessment follows this sequence:
- Identify accepted income. Separate regular earnings from variable payments and business income.
- Account for commitments. Include living expenses, dependants, existing loans, credit facilities and relevant study debt.
- Assess proposed repayments. The lender applies its servicing requirements to the requested loan.
- Check the purchase budget. Combine the proposed borrowing with available funds, then allow for purchase costs and retained savings.
Borrowing capacity measures what a lender will consider; your household budget determines what you are comfortable repaying. Keep both limits visible when deciding what to offer on a property.
Why this matters
A salary-only estimate can send your property search in the wrong direction. It ignores the distinction between what you earn, what reaches your bank account and what a lender accepts for assessment.
Medical borrowers have another consideration: payslips can combine base salary with overtime, on-call work and allowances. A strong total on one payslip does not establish that every component will be counted in full.
Start by checking the evidence supporting each income component. That gives you a more useful question than asking which lender advertises the largest borrowing estimate.
How different income types affect your assessment
The key distinction is not simply employed versus self-employed. It is whether your income is documented, ongoing and acceptable under the lender's policy.
| Income type | What to prepare | Useful feature | Limitation to check |
|---|---|---|---|
| Base salary | Payslips and employment details | Provides a clear starting point for assessment | Employment conditions and deductions still matter |
| Overtime and on-call pay | Payslips showing the payment history | Documents earnings beyond base salary | Acceptance depends on consistency and lender policy |
| Locum or contract income | Contracts, payment records and relevant tax documents | Shows the sources and continuity of work | A current contract alone does not establish ongoing earnings |
| Self-employed income | Tax documents, financial statements and business details requested by the lender | Shows business performance and borrower income | Business turnover is not the same as personal income |
| Rental income | Lease, rental statements or other evidence requested | Supports assessment of investment income | Property expenses and lender treatment affect the result |
Do not add every deposit into your bank account and label the total assessable income. Transfers between your accounts, borrowed funds and business receipts need to be distinguished from personal earnings.
For doctors, keep the broader salary question separate from profession-specific lending policy. The guide to how much you can borrow as a doctor in Australia addresses that more specific assessment.
How do I convert my pay into annual income?
Use a consistent pay period before entering figures into a borrowing calculator. Mixing a monthly income figure with weekly expenses produces an unreliable result even when every individual entry is accurate.
Common annualising conventions are:
- Monthly pay: multiply the regular payment by 12 monthly payments.
- Fortnightly pay: multiply the regular payment by 26 fortnightly payments.
- Weekly pay: multiply the regular payment by 52 weekly payments.
These are calculator conventions for regular pay, not instructions to multiply an unusually high payslip. For variable income, use payment history and the evidence the lender requests rather than projecting your strongest pay period across the year.
Check whether the calculator asks for gross income before tax or net income after deductions. Do not substitute one for the other, and keep salary packaging and payroll deductions visible for the assessment.
Why borrowing capacity varies
Your salary is only one input. These six factors explain why the same headline income does not always support the same loan:
- Accepted earnings: lenders assess the evidence and treatment of salary, variable pay, rental income and business earnings.
- Household expenses: day-to-day spending, dependants and ongoing commitments affect the funds available for repayments.
- Existing debts: personal loans, vehicle finance, other mortgages and relevant study debt affect servicing.
- Credit facilities: credit card limits and other available credit can affect assessment even when balances are low.
- Loan structure: the term and repayment structure affect the repayment calculation.
- Property and deposit: the security, valuation and available contribution affect whether the proposed transaction meets lending requirements.
Fix inaccurate inputs before comparing lenders. An estimate based on omitted debts or overstated earnings is not an achievable borrowing target.
Do not reduce essential spending on paper to make an application look stronger. Use an honest household budget and disclose commitments so the assessment reflects your actual position.
How to prepare a useful borrowing assessment in 2026
Prepare a clear summary before requesting an assessment. You do not need to interpret every lending policy yourself; you need to make your financial position understandable and support it with documents.
Gather income evidence
Collect recent payslips, employment details and records of additional earnings. If you work across hospitals, practices or contracts, identify each payer and income source separately.
For self-employed work, distinguish business revenue from the income available to you. Ask which financial statements and tax documents are required before treating business receipts as personal earnings.
List commitments
Record loan repayments, credit limits, study debt and recurring financial obligations. Include facilities you rarely use rather than assuming an unused account has no effect.
Check your regular spending against statements. This helps you identify overlooked commitments and prepare a budget that remains useful after settlement.
Confirm deposit
Separate funds available for the purchase from money you intend to retain. Then account for transaction costs rather than treating your entire savings balance as the deposit.
If family support forms part of the plan, explain whether it is a gift, a loan or proposed guarantor support. These arrangements are not interchangeable.
Request assessment
Ask which income components were accepted, which commitments were included and whether any assumptions remain unverified. Keep the borrowing estimate separate from the lender's approval decision.
Set repayment limit
Choose a repayment level that leaves room for your actual household priorities. A maximum borrowing figure is not a recommendation to spend the maximum.
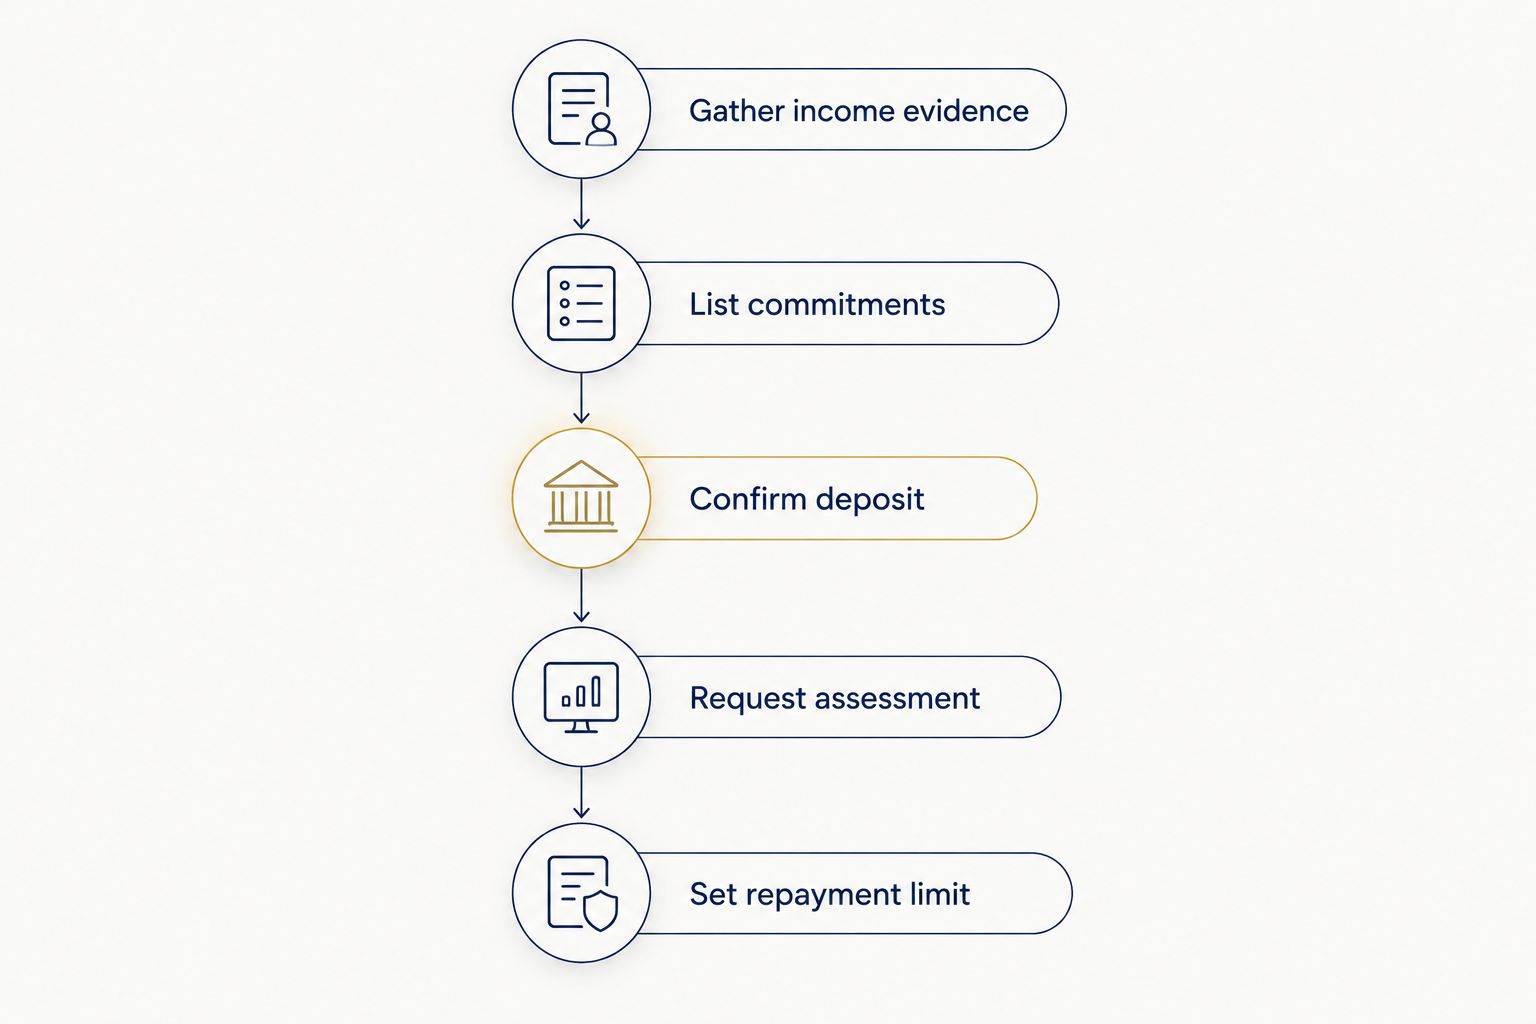
Once these details are organised, request an assessment before relying on an online result for a property offer. Explain any upcoming employment change or planned borrowing at the same time.
Get your borrowing position assessed
Discuss your income, commitments and deposit before setting a property budget.
Can I borrow more if I earn overtime or on-call pay?
Overtime and on-call pay can support a borrowing assessment when the lender accepts the income and its supporting evidence. Do not assume every additional payment receives the same treatment as base salary.
For a doctor combining hospital work with other earnings, prepare a separate breakdown of each component. Identify which payments recur, which depend on shifts worked and which arise from a temporary arrangement.
Ask the assessor to explain how each component affects the result. That makes it easier to understand whether the estimate rests on regular income or an assumption that still needs verification.
Does a bigger deposit increase how much I can borrow?
A bigger deposit reduces the loan needed for the same property, but it does not replace the requirement to demonstrate repayment capacity. Deposit strength and income servicing answer different questions.
If income servicing is the constraint, adding deposit funds does not change the income calculation itself. It can still make the transaction workable by reducing the amount you need to borrow.
Keep available savings, purchase costs and retained funds separate. Otherwise, a borrowing estimate can appear workable while the purchase budget remains incomplete.
Can I borrow more with a joint applicant?
A joint application brings both applicants' accepted income into the assessment, along with their debts and relevant household commitments. It is not simply a matter of adding salaries and keeping the rest of the calculation unchanged.
Prepare evidence for both applicants and disclose liabilities held individually as well as jointly. Assess the repayment against the household budget, including any expected change in working arrangements.
Where specialist mortgage advice fits
Mortgage Pros is best suited to medical borrowers seeking specialist home loan advice. Its focus includes doctors, dentists and surgeons, alongside support for other borrowers and investors.
The practical benefit of a broker assessment is help organising the income evidence and considering lending requirements against your circumstances. The limitation is equally important: advice and a borrowing estimate do not guarantee lender approval.
Ask what assumptions support the recommendation and what still needs confirmation. You should understand both the proposed borrowing amount and the conditions attached to it before proceeding.
FAQ
How much can I borrow based on my income in 2026?
Your borrowing capacity depends on accepted income, expenses, existing debts and the proposed loan repayments—not salary alone. A lender assessment is needed before treating an estimate as an achievable loan amount.
Can I use my gross salary in a home loan calculator?
Use gross salary only when the calculator asks for income before tax. Follow its instructions for pay frequency, additional income and deductions so the result uses consistent inputs.
Will a lender count all my overtime?
Do not assume a lender will count all your overtime. Acceptance depends on the income evidence and lender policy, so separate overtime from base salary when preparing your application.
Do credit cards affect borrowing capacity if I pay them off?
Credit card limits can affect borrowing capacity even when you clear the balance. Disclose the limits and ask how the lender treats each facility before changing or closing accounts.
Does my HELP debt affect how much I can borrow?
HELP debt can affect borrowing capacity through its treatment in the lender’s servicing assessment. Disclose the debt and any repayment deductions rather than relying on an estimate that leaves them out.
Can doctors use hospital and private practice income together?
Doctors can present hospital and private practice income together for assessment, but the lender determines what it accepts. Keep employment earnings, business revenue and personal income clearly separated and supported by documents.
Is a borrowing calculator result the same as pre-approval?
A borrowing calculator result is not pre-approval. It is an estimate based on the figures and assumptions entered, while a lender assessment involves further checks and conditions.
Can Mortgage Pros help me understand my borrowing capacity?
Mortgage Pros provides mortgage broking advice for home buyers and property owners, with a focus on medical borrowers. Contact the team with your income, commitments and deposit details to discuss your home loan position.
One last thing
For your 2026 property search, request two figures: the lender-assessed borrowing estimate and your own comfortable repayment limit. Use the lower practical limit to guide your search rather than treating maximum eligibility as a household budget.
Before making an offer, confirm what remains subject to verification. Contact us today to discuss your income and borrowing position before committing to a purchase. This is general information, not a personal credit recommendation; lending criteria and individual circumstances determine the outcome.
Related guides
- Can doctors use overtime and on-call pay for a home loan?
- How is self-employed dentist income assessed for a home loan?
- How do surgeons combine hospital and private income for a home loan?