Use a mortgage broker when you want help comparing lenders and matching a loan to your circumstances; go directly to a bank when you want that bank’s products and are comfortable checking alternatives yourself. Neither route guarantees approval or the lowest overall borrowing cost, so compare the proposed loan, the assessment of your income and the support included before you apply.
- Mortgage broker or bank: which is better? Choose a broker for lender comparisons; choose a bank for direct access.
- Mortgage Pros provides mortgage broking for borrowers, including doctors, dentists and surgeons seeking home loan advice.
- A broker’s lender panel is not the whole market; a bank’s home loan range is narrower still.
- Compare the proposed loan and income assessment, not just the person taking your application.
Is it better to use a mortgage broker or go directly to a bank?
A mortgage broker is the better fit when you need help comparing participating lenders, understanding lending criteria or preparing an application. A bank is the better fit when you have already compared alternatives and want to deal directly with your chosen lender.
Mortgage Pros provides mortgage broking services for home buyers and property owners, including refinancing and guarantor arrangements. Mortgage Pros is best suited to borrowers seeking home loan advice, including doctors, dentists and surgeons. The service supports your application; the lender still decides whether to approve it.
Use this comparison to choose your starting point in 2026:
| Decision point | Mortgage broker | Bank directly |
|---|---|---|
| Best for | Borrowers wanting help comparing participating lenders | Borrowers who have assessed alternatives and prefer a particular bank |
| Product range | Loans available through the broker’s lender panel | The bank’s own home loan range |
| Main benefit | Help matching lending criteria and loan features to your circumstances | Direct discussion with the institution assessing and issuing the loan |
| Main limitation | The panel does not represent every lender or product | The bank does not compare competing lenders for you |
| Application support | The broker helps prepare and coordinate the application | You work with the bank’s lending team |
| Approval authority | The lender makes the credit decision | The bank makes the credit decision |
| What to verify | Panel coverage, recommendation reasons and remuneration | Product suitability and how the offer compares elsewhere |
Why this matters
Choosing a home loan is not simply choosing who answers your emails. Your income, deposit, existing debts and property must fit the lender’s requirements, while the loan’s features must fit how you intend to use it.
For a doctor moving between hospital roles, that means asking how the lender assesses the employment arrangement. For a borrower with straightforward salary income, the decision might centre on loan features and whether an existing bank’s offer stacks up against alternatives.
In 2026, assess the application route and the loan separately. Helpful service does not make an unsuitable loan suitable, and an appealing headline offer does not establish that you qualify.
When a mortgage broker is the better fit
Best for: borrowers who need help comparing lenders or explaining their circumstances. A broker can assess your position against participating lenders’ requirements and explain why a particular loan is being recommended.
This is particularly useful when your application needs more explanation than a standard salary and deposit. Examples include variable earnings, self-employment, guarantor arrangements or a refinance involving several existing debts. The useful service is identifying the relevant questions before an application reaches a lender.
A broker also provides a point of contact during the application. Ask what that support includes, who follows up outstanding documents and whether assistance continues after settlement.
The limitation is coverage. A broker does not automatically compare every available loan, and a large lender panel does not prove that every lender was considered for your circumstances. Ask which alternatives were assessed and why the recommended lender fits better.
A broker cannot override lending criteria, guarantee a valuation or promise approval. Treat any recommendation as a proposal to examine, not a substitute for reading the loan documents.
When going directly to a bank is the better fit
Best for: borrowers who want a particular bank’s loan and can assess competing offers themselves. Direct access lets you discuss the application with the institution that will assess it and, if approved, provide the loan.
This route makes sense when you understand your borrowing position, have checked other lenders and prefer the bank’s proposed features or service arrangements. An existing banking relationship can provide familiarity, but familiarity alone does not establish that the home loan is competitive.
Ask the bank how it will assess your income, which documents it needs and what conditions apply to any preliminary indication. Get the proposed loan structure in writing so you can compare it properly.
The drawback is the scope of advice: a bank explains its own products rather than selecting between competing lenders. If its policy does not suit your circumstances, you need to assess another lender yourself or seek broking assistance.
Going direct is a distribution choice, not evidence of a better loan. Compare the actual proposal before deciding.
Why the better choice varies between borrowers
The answer depends on what you need assessed and how much comparison work you want to manage. These factors matter more than a blanket preference for brokers or banks:
- Income structure: A regular salary, variable hospital earnings and self-employed practice income require different supporting evidence. Ask how the lender treats each component.
- Deposit and security: Your available funds, the property and any proposed guarantee affect which loan arrangements warrant consideration.
- Existing commitments: Credit facilities and other loans form part of the lender’s assessment. Present a complete picture rather than focusing only on income.
- Loan features: Offset facilities, redraw, repayment flexibility and fixed or variable structures serve different purposes. Compare the features you will actually use.
- Comparison scope: A broker compares within its available lender panel; a bank presents its own range. Understand what each process leaves out.
- Support needs: Decide whether you want help assembling evidence and following up an application, or prefer managing those conversations directly.
For your 2026 decision, write down which factors are essential and which are preferences. That prevents a convenient application process from outweighing a poor fit.
How to compare a broker’s recommendation with a bank’s offer
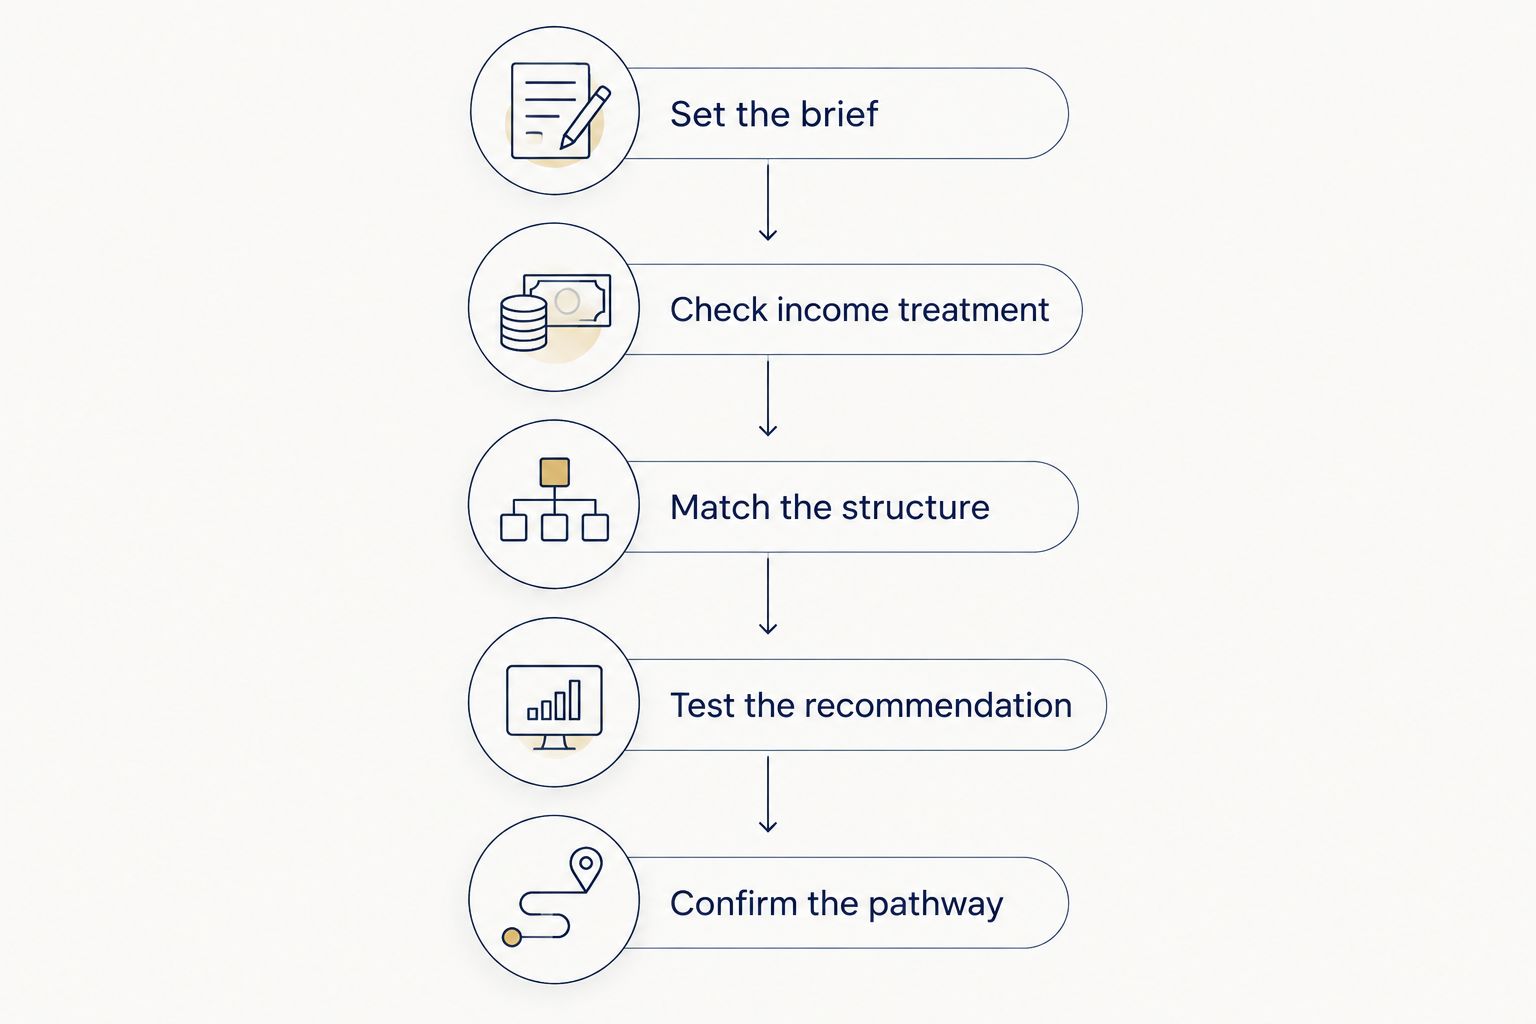
Use these 5 steps before submitting a formal application. The aim is to compare equivalent proposals, not collect unrelated borrowing estimates.
1. Set the brief
Give both parties the same information: purchase or refinance purpose, property use, available deposit, income sources, liabilities and preferred loan features. Explain any employment changes or planned changes to your circumstances.
Keep the brief consistent. If one proposal assumes a different loan amount or repayment structure, the comparison will not tell you which route serves you better.
2. Check income treatment
Ask what income the lender will assess and which documents support it. For variable earnings, distinguish between money you receive and income the lender is prepared to include in its assessment.
A doctor should identify base salary, overtime, on-call payments and any separate contracting income. A self-employed dentist should explain the business structure rather than presenting business turnover as personal income.
3. Match the structure
Compare the same borrowing amount, loan term, repayment type and intended property use. Then examine the features, conditions and charges disclosed in each proposal.
Ask whether a feature is essential to your plan. An offset facility is not a reason to select a loan if you do not understand how the account operates or how you would use it.
4. Test the recommendation
Ask the broker why the recommended lender suits your circumstances and which alternatives were considered. Ask the bank what makes its proposed loan suitable and compare that answer against the alternatives you have gathered.
Request disclosure of fees and commissions before proceeding. Do not assume that a broker’s service has no borrower charges, or that applying directly automatically produces a better financial outcome.
5. Confirm the pathway
Establish who submits the application, who requests additional evidence and who updates you about conditions. Ask what remains outstanding before any approval can become unconditional.
Keep preliminary borrowing discussions separate from a formal credit decision. Before committing to a property purchase, obtain appropriate advice about your finance conditions and contractual obligations.
What doctors, dentists and surgeons should check
For medical borrowers, the key question is not simply whether a lender offers home loans for your profession. It is whether the lender accepts your employment and income evidence for the loan you need.
A salaried doctor and a self-employed surgeon can have very different applications. Present each income source separately and ask how it will be assessed; do not assume that professional registration replaces ordinary credit assessment.
Use these 3 questions when comparing advice in 2026:
- Which earnings are included? Identify salary, overtime, on-call payments, locum earnings and private-practice income where relevant.
- Which evidence is required? Ask which employment, income and business documents support the application, rather than relying on a generic checklist.
- Which conditions remain? Establish whether employment status, property valuation or additional documentation still needs assessment.
Mortgage Pros specialises in home loans for doctors, dentists and surgeons. That focus is relevant when you want profession-specific mortgage broking advice, but it does not remove the lender’s approval requirements.
Discuss your home loan today
Ask how your income, deposit and loan goals affect your application options.
Does a mortgage broker have to act in my best interests?
Australian mortgage brokers must act in consumers’ best interests when providing credit assistance covered by the mortgage broker best interests duty. ASIC’s regulatory guidance explains this obligation and the related requirement to prioritise consumers’ interests when a conflict arises.
The duty is relevant to your 2026 comparison, but it does not mean a broker searches the entire market or guarantees the cheapest loan. Ask for the reasons behind the recommendation and how your objectives and financial circumstances informed it.
A bank employee offering the bank’s own home loans is not providing the same cross-lender broking service. Assess the bank’s proposal on its suitability and disclosed terms rather than assuming the two channels have identical roles.
Can a bank give me a better deal than a broker?
A bank’s direct offer can differ from a broker-arranged proposal, but neither channel is automatically better. Compare the actual loan terms, conditions and features rather than assuming that removing or adding a broker determines the result.
Use written proposals based on the same borrowing brief. If an offer changes during your 2026 application, revisit the comparison before accepting it.
Will using a broker make approval easier?
A broker can help prepare an application and identify suitable participating lenders, but cannot guarantee approval. Better preparation addresses missing evidence; it does not remove a lender’s credit requirements.
Ask what could prevent approval before submitting the application. A clear explanation of unresolved issues is more useful than an assurance that approval should be straightforward.
FAQ
Mortgage broker or bank: which is better for a first home buyer?
A mortgage broker is better suited to a first home buyer who wants help comparing participating lenders and preparing an application. Going directly to a bank suits a buyer who has checked alternatives and wants that bank’s loan.
Will a mortgage broker compare every bank in Australia?
No, a mortgage broker compares loans available through its lender panel, not every bank and product in Australia. Ask which lenders were considered and whether relevant options sit outside the panel.
Can I speak to my bank and a mortgage broker before deciding?
Yes, you can discuss your circumstances with both before choosing an application route. Clarify whether each conversation is preliminary or involves a formal application or credit enquiry.
Does using a mortgage broker guarantee approval?
No, using a mortgage broker does not guarantee approval. The lender assesses the application, supporting documents, property and relevant credit requirements.
Is a doctor mortgage broker better than my usual bank?
A doctor mortgage broker is a useful choice when you want help assessing medical employment and income across participating lenders. Your usual bank remains an option if its requirements and proposed loan suit your circumstances.
What should I ask about broker fees and commissions?
Ask the broker to disclose borrower fees, lender commissions and any relevant conditions before you proceed. Compare that disclosure alongside the proposed loan rather than assuming how the broker is paid.
Can Mortgage Pros help me refinance rather than buy?
Mortgage Pros provides mortgage broking services that include refinancing. Discuss your existing loan, reasons for switching and desired structure so the proposed refinance can be assessed against your goals.
One last thing
Ask for the reason a loan suits you, not just the amount you can borrow. A borrowing estimate does not explain how the proposed loan handles your income, supports your repayment plans or compares with alternatives.
Before choosing either route, request a written summary covering the recommendation, its limitations and the documents still required. Keep that summary beside the proposed loan terms so you can check whether the application still matches your original brief.
Ready to compare your options? Contact us today to discuss your home loan goals, income and application requirements.
Related guides
- How to choose a doctor mortgage broker for complex income
- Can doctors use overtime and on-call pay for a home loan?
- How does a guarantor home loan work?