Choose Mortgage Pros if you want a mortgage broker that specialises in home loans for doctors, dentists and surgeons; choose Mortgage Choice if you already have a trusted broker there who understands your finances and can explain a suitable lending recommendation. This 2026 comparison separates specialist experience from broker continuity, then shows you how to compare the advice behind each application.
- Mortgage Pros vs Mortgage Choice: choose medical home loan specialisation or continuity with a trusted existing broker.
- Mortgage Pros is the stronger fit for doctors seeking a mortgage broker with an explicit medical lending focus.
- Mortgage Choice is the practical choice when an existing broker relationship already meets your borrowing needs.
- Compare written recommendations, fee disclosures and lender conditions before authorising a home loan application.
Why this matters
A mortgage broker helps you select and apply for a loan; the lender decides whether to approve it. Choosing a familiar business name does not replace checking whether the individual broker understands your income, deposit and property plans.
For a doctor, that conversation should address how a lender assesses employment and income. For a returning borrower, an adviser who already understands the household's finances offers continuity—but the next recommendation still needs to stand on its own.
The useful distinction in 2026 is medical lending specialisation versus an established advisory relationship. Neither automatically produces the right loan. You need a clear explanation of why a particular lender and loan structure suit your circumstances.
At a glance
| Dimension | Mortgage Pros | Mortgage Choice |
|---|---|---|
| Best for | Doctors, dentists and surgeons seeking a specialist starting point | Borrowers continuing with a trusted existing broker |
| Standout feature | Explicit focus on home loans for medical professionals | Continuity when your existing adviser already understands your finances |
| Broker relationship | A new adviser needs to learn your circumstances | An established relationship avoids starting the advice conversation from scratch |
| Lender selection | Assess the reasoning behind the recommended lender | Apply the same test to the individual broker's recommendation |
| Refinancing | Refinancing and equity assistance are part of the firm's services | Ask the broker to demonstrate the benefit of any proposed refinance |
| Guarantor arrangements | Guarantor assistance is part of the firm's services | Check the individual broker's experience with your proposed arrangement |
| Pricing model | Obtain written broker-fee and commission disclosures | Obtain written broker-fee and commission disclosures |
| Approval responsibility | The lender makes the credit decision | The lender makes the credit decision |
Medical borrowers get a clearer specialist starting point
Mortgage Pros is the stronger fit for doctors seeking a mortgage broker with an explicit medical lending focus. Its stated specialisation includes doctors, dentists and surgeons, rather than treating medical borrowers as an incidental audience.
That gives you a relevant starting point. It does not establish eligibility for a particular lender policy, remove the need to demonstrate repayment capacity or guarantee approval.
If your income includes different employment arrangements, ask how each component will be presented. Your broker should distinguish income the lender will accept from income that needs additional evidence.
Use these questions to test the advice:
- Which parts of my income support the application?
- What evidence does the recommended lender require?
- Does my employment or professional status affect the recommendation?
- Which conditions must I meet before the lender assesses the application?
The guide to home loan lenders for doctors provides a related starting point for that discussion. For a 2026 application, ask the broker to confirm current lender requirements rather than relying on an older policy summary.
The limitation: specialist positioning is a reason to investigate, not a reason to accept the first recommendation without an explanation.
Mortgage Choice wins on continuity with a trusted existing broker
Choose Mortgage Choice when you already have an adviser there who understands your circumstances and has earned your confidence. That is a genuine reason to stay, especially when the adviser can explain how your next borrowing decision fits your existing finances.
Continuity has practical value. You can discuss what has changed instead of rebuilding the entire background to your loan history and property plans.
However, previous familiarity is not enough on its own. An adviser still needs to update your income, expenses, liabilities and objectives before recommending a new loan.
Ask your existing broker:
- What has changed since my previous application?
- Does the previous lender still suit my circumstances?
- What alternatives did you consider this time?
- What would make you recommend staying rather than switching?
The limitation: an established relationship becomes a disadvantage if it discourages you from questioning the recommendation. Keep the continuity; require fresh reasoning.
If you do not already have a trusted adviser, this advantage does not apply. Compare the actual brokers you would work with, not an imagined relationship with the broader brand.
Both need to explain lender selection—not just present a shortlist
There is no useful winner on lender selection without examining the proposed loan. A list of lender names does not tell you which lender will assess your income appropriately or which structure supports your plans.
Ask each broker to explain the recommendation in plain language. You should understand the relevant eligibility requirements, loan features and trade-offs before an application goes ahead.
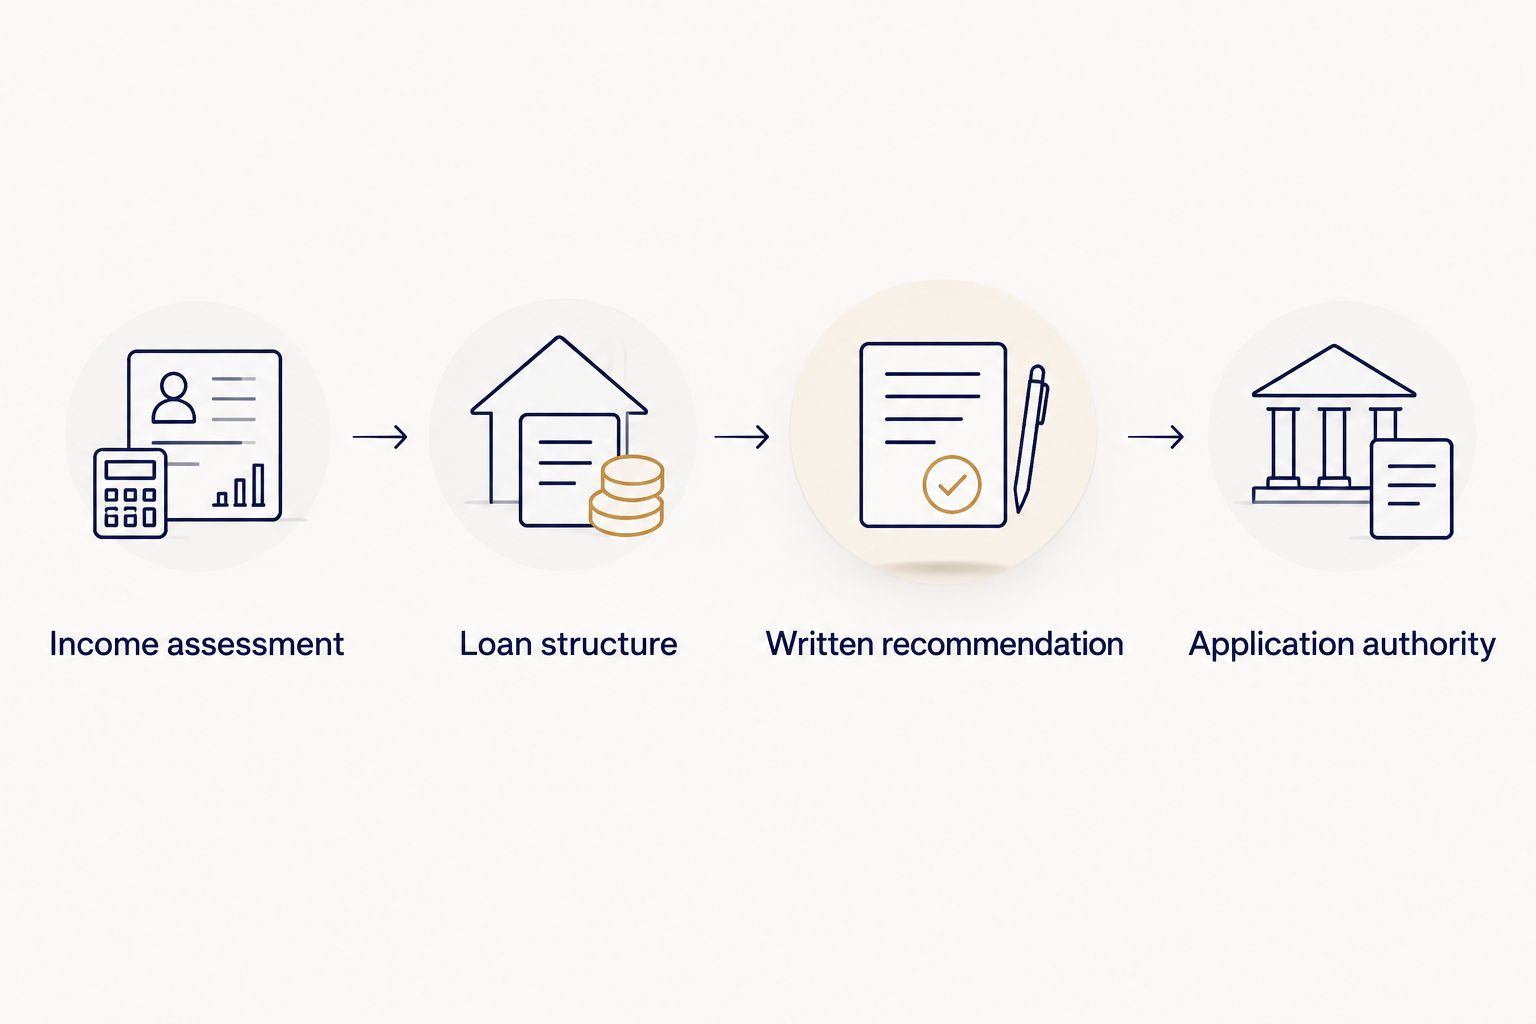
A useful comparison follows this sequence:
- Income assessment: establish what the lender will accept and what evidence supports it.
- Loan structure: decide which features serve your borrowing and repayment plans.
- Written recommendation: connect the proposed lender and loan to your circumstances.
- Application authority: confirm the proposal before authorising submission.
A broker should also explain the boundaries of the comparison. Ask which lenders were considered and whether any relevant options sit outside the broker's available lender panel.
Treat lender selection as a tie until one adviser supplies a more convincing, documented recommendation. Brand familiarity and specialisation help you choose whom to approach; neither replaces that evidence.
Refinancing needs a written benefit, not a promised improvement
Refinancing and equity assistance form part of the specialist firm's stated services. That makes it a relevant option when you want to review an existing loan or discuss accessing equity.
It does not establish that switching lenders is the right answer. Your current loan, proposed loan and future plans all belong in the comparison.
For a refinance review in 2026, request a written explanation covering:
- Purpose: identify whether you want a different structure, access to equity or another specific outcome.
- Switching costs: identify relevant discharge, application and other transaction charges.
- Loan term: check whether the proposed term extends your repayment period.
- Features: distinguish features you will use from features that add complexity.
- Staying put: ask whether retaining or reviewing the existing loan addresses the problem.
An existing Mortgage Choice broker has a continuity advantage if they already understand why you selected the current loan. A new specialist adviser offers a different assessment, but still needs to demonstrate the benefit of changing it.
Choose the documented refinance case, not the stronger sales pitch. Neither side earns a refinancing win simply by proposing a new application.
Guarantor borrowers should compare the exit plan as closely as entry
Guarantor arrangements are another stated service of the specialist firm. If family support forms part of your purchase plan, that is a relevant reason to start a conversation.
The important comparison is how clearly each adviser explains the proposed guarantee. Ask what the guarantee covers, what obligations the guarantor accepts and how release would be assessed.
Keep these decisions separate:
- Whether the borrower can service the proposed loan.
- Whether the guarantor understands and accepts the arrangement.
- What conditions the lender sets for releasing the guarantee.
Do not treat a future release as automatic. Ask for the lender's requirements and discuss independent legal advice before anyone signs.
For Mortgage Choice, assess the individual broker's experience with the arrangement you propose. For the specialist alternative, apply exactly the same scrutiny despite the stated service offering.
The better adviser is the one who explains both entry and exit clearly. A reassuring application conversation is not a substitute for understanding the guarantee.
Pricing: compare the written fee model and lender costs separately
A mortgage broking comparison needs to separate the broker's remuneration from the lender's charges. Ask both advisers for their current disclosure documents before agreeing to proceed.
Your questions should cover whether you pay a broker fee, when any fee becomes payable and what lender commissions apply. Also ask whether any charge changes if you withdraw, refinance or repay the loan early.
Different payment arrangements create different trade-offs. A disclosed client fee gives you an explicit service charge to assess; lender-paid remuneration still needs a clear explanation of how the broker is paid and why the recommendation suits you.
| Cost question | What you need to establish |
|---|---|
| Broker fees | Whether you pay a fee and what service it covers |
| Lender commissions | How the broker is remunerated by the lender |
| Lender charges | Which loan-related charges apply |
| Later changes | Whether withdrawal or early repayment creates a charge |
Neither business wins on pricing without a current, borrower-specific comparison. For a 2026 decision, assess the full arrangement rather than assuming the broking service or proposed loan has no associated costs.
Both support applications; neither controls lender approval
A mortgage broker can explain requirements, organise an application and communicate with the lender. The lender retains responsibility for the credit decision.
That distinction matters when you compare approval support. Ask who manages your file, how outstanding documents are communicated and how the broker handles changes to your circumstances.
For a property purchase in 2026, discuss finance conditions and contractual deadlines with your solicitor or conveyancer. Do not treat a broker's confidence or an initial lending indication as unconditional approval.
Approval responsibility is an honest tie. Select the adviser who explains the process and outstanding conditions clearly, rather than the adviser who sounds most certain about an outcome they do not control.
Final verdict: choose specialisation or proven continuity
Choose Mortgage Pros if you are a medical borrower seeking specialist advice
Doctors, dentists and surgeons have a clear reason to approach a firm that explicitly specialises in their home loan needs. Bring your income details, deposit position and property plans, then ask for a lender recommendation tied to those facts.
The trade-off is that a new adviser must learn your circumstances. Judge the quality of that assessment before authorising an application.
Choose Mortgage Choice if your existing broker already meets your needs
A returning borrower with a trusted, informed adviser has a practical reason to stay. Continue the relationship when the broker supplies a current recommendation that makes sense for your next decision.
The trade-off is familiarity without challenge. Ask what alternatives were considered and why the proposed approach still suits you.
| Dimension | Winner |
|---|---|
| Medical lending starting point | The explicitly medical-focused specialist |
| Existing trusted relationship | Mortgage Choice, when that relationship already exists |
| Lender selection | Tie until the written recommendations are compared |
| Refinancing | The adviser who demonstrates a clear benefit |
| Guarantor arrangements | The adviser who explains obligations and release conditions |
| Pricing model | No winner without current disclosures |
| Approval responsibility | Tie—the lender decides |
Discuss your home loan today
Explain your income, deposit and property plans, and ask which lending approach fits your circumstances.
FAQ
Is Mortgage Pros better than Mortgage Choice for doctors?
Mortgage Pros is the stronger starting point for doctors seeking an explicitly medical-focused mortgage broker. Compare the individual adviser’s recommendation, lender requirements and disclosures before deciding.
Should I stay with my existing Mortgage Choice broker?
Stay when your existing Mortgage Choice broker understands your current circumstances and provides a suitable, clearly explained recommendation. Familiarity should support a fresh assessment, not replace it.
Can either mortgage broker guarantee home loan approval?
Neither mortgage broker controls lender approval. The lender assesses the application and sets any conditions that must be satisfied.
How do I compare mortgage broker fees?
Compare current written disclosures covering client fees, lender commissions and any charges triggered by later changes. Assess lender charges separately from the broker’s remuneration.
What should a doctor prepare before speaking to a broker?
Prepare evidence of income, employment details, liabilities, expenses and your deposit position. Ask the broker which additional documents the proposed lender requires for your circumstances.
Which broker should I use for refinancing?
Choose the adviser who demonstrates why the proposed refinance improves your position against keeping the existing loan. Compare switching costs, loan structure and the proposed repayment term.
What should I ask about a guarantor home loan?
Ask what the guarantee covers, what obligations the guarantor accepts and how the lender assesses release. Discuss independent legal advice before committing to the arrangement.
One last thing
Ask each adviser: What would make you recommend that I do not apply yet? The answer tests whether the conversation addresses readiness as well as the desired outcome.
An income document, unresolved liability or unsuitable property can change the next step. Contact us today with your circumstances and ask what needs to be resolved before an application begins.
Related guides