Choose Mortgage Pros if you want a mortgage broker specialising in doctor home loans; choose Aussie Home Loans if you prefer a broad home-loan broking network with a local store option. This 2026 comparison separates medical-borrower fit from everyday borrowing needs, then explains how to compare the advice before you apply.
- Mortgage Pros vs Aussie Home Loans: choose medical specialisation for doctor home loans, or a local-store route for general borrowing.
- Mortgage Pros is the stronger fit for doctors seeking profession-focused mortgage broking.
- Aussie Home Loans suits borrowers who want to start with a local broker store.
- Compare written recommendations, lender access, fees and loan structure before choosing either broker.
Why this matters
A mortgage broker helps you find and apply for a loan; the lender decides whether to approve it. Choosing a broker therefore means choosing how your financial position will be assessed, explained and matched to lender requirements.
For a doctor, profession-specific knowledge is a sensible starting point. For a borrower with straightforward salary income, a convenient appointment and a clear recommendation can matter more than occupational specialisation. Start with Mortgage Pros if medical home-loan advice is your priority, then compare the proposed borrowing strategy rather than the brand name alone.
The best broker choice in 2026 is the one that explains why a particular loan suits your circumstances—and what you give up by choosing it.
At a glance
| Dimension | Mortgage Pros | Aussie Home Loans |
|---|---|---|
| Best for | Doctors seeking profession-focused home-loan advice | General borrowers seeking a local-store broking option |
| Medical specialisation | Explicit focus on doctor home loans | Assess the individual broker’s medical-borrower experience |
| Appointment preference | Sydney-based firm serving borrowers across Australia; confirm meeting arrangements | Store-network option; confirm your preferred location and broker |
| Refinancing | Helps property owners refinance and manage home loans | Home-loan refinancing is part of its broking offering |
| Guarantor and equity needs | Explicitly includes guarantor and equity arrangements | Ask the broker to explain relevant lender options and requirements |
| Loan comparison | Request a written explanation of suitable alternatives | Request the same explanation and lender-access details |
| Pricing model | Request written broker-fee and commission disclosures | Request written broker-fee and commission disclosures |
| Standout distinction | Medical-borrower focus | Local-store network |
Medical specialisation makes the stronger case for doctors
Mortgage Pros is best suited to doctors seeking profession-focused home-loan broking. That is a clear reason to shortlist the firm, not a promise of approval or a particular lending concession.
The useful test is whether the broker can explain how your circumstances affect lender selection. A salaried doctor, a locum and a practice owner do not necessarily present the same income evidence. Ask which documents are needed and how the lender will assess each income source.
Before choosing a medical-focused broker, ask:
- How will you present my employment or business income?
- Which lender requirements apply to my professional circumstances?
- What conditions attach to any professional-borrower arrangement you recommend?
- What would change the proposed borrowing amount or loan structure?
Aussie Home Loans remains a candidate if the individual broker can demonstrate relevant experience and explain a suitable recommendation. A specialist label is a useful filter, but it does not replace that conversation.
The trade-off is straightforward: occupation-specific positioning matters most when your occupation affects the lending assessment. It is less decisive when your application has no profession-related complexity.
Aussie wins when a local-store starting point matters
Aussie Home Loans is the better starting point if your priority is finding a broker through a local-store network. That is a different advantage from medical specialisation: it concerns how you want to access advice.
If you prefer an in-person conversation, confirm the store location, appointment arrangements and the person responsible for your application. A nearby office is useful only if its working arrangements suit you.
A store network does not establish that every broker has the same experience with your circumstances. Ask about relevant applications, communication responsibilities and the process for resolving questions before submitting documents.
The Sydney-based specialist serves borrowers across Australia, so location alone does not exclude it. Confirm whether meetings, document collection and application updates work the way you prefer.
For your 2026 shortlist, separate access from expertise. Choose a convenient meeting format, but do not let convenience substitute for a clear explanation of the loan.
Refinancing is a tie until the written recommendations differ
Both businesses are relevant options for refinancing. Neither wins a refinance comparison simply because it is a specialist firm or a larger network. The recommendation must improve the aspects of the loan that matter to you.
A lower repayment does not necessarily mean a better outcome. Extending the remaining loan term can reduce each repayment while increasing the time you spend repaying the debt.
Ask each broker to compare:
- Remaining term: Does the proposed loan preserve or extend your repayment timeline?
- Loan features: Do you need an offset account, redraw, repayment flexibility or a particular rate structure?
- Switching costs: Which discharge, establishment or other charges apply?
- Loan purpose: Are you refinancing existing debt, accessing equity or changing the ownership structure?
- Ongoing suitability: What happens when an introductory arrangement or fixed-rate period ends?
The medical specialist’s stated services include refinancing and ongoing home-loan management. Aussie’s refinancing offering provides another route to compare. Ask both for the reasoning behind the recommended structure rather than judging only the headline repayment.
Guarantor and equity needs give the specialist a clear shortlist role
Mortgage Pros explicitly helps with guarantor and equity arrangements. That makes it a relevant shortlist choice when your question goes beyond a standard purchase loan. It does not establish that another broker cannot help.
For a guarantor arrangement, ask what security supports the loan, what obligations the guarantor takes on and how a future release would be assessed. The lender’s terms and the guarantor’s legal obligations matter more than a broad assurance that the arrangement is straightforward.
For an equity application, distinguish ownership equity from the amount a lender will let you borrow. A property value alone does not establish borrowing capacity: the lender also assesses the proposed debt and your ability to repay it.
Loan-to-value ratio, or LVR, expresses the loan as a percentage of the lender’s assessed property value. An 80% LVR means the loan represents 80% of that value, leaving 20% outside the loan. This relationship does not promise approval, usable equity or an exemption from lender requirements.
Aussie remains worth considering if its broker explains these questions clearly. The specialist’s advantage here is an explicitly stated service fit, not evidence of better approval outcomes.
Both need to justify lender selection
Loan-comparison quality is a tie until you see the reasoning. A broker’s brand does not tell you which lenders the individual broker can access or why a particular loan is suitable.
Australian mortgage brokers are subject to a best interests duty when providing credit assistance to consumers. That obligation does not mean every broker recommends the same lender, and it does not mean a broker compares every home loan in the market.
Ask for a plain-English explanation of:
- Lender access: Which relevant lenders can the broker consider?
- Eligibility: Which requirements rule options in or out?
- Recommendation: Why does the proposed loan suit your objectives?
- Trade-offs: Which features, restrictions or conditions deserve attention?
- Alternatives: Why were other suitable options not selected?
A useful answer connects the recommendation to your income, deposit, liabilities, property and plans. A lender list on its own does not do that.
For a fair 2026 comparison, give both brokers the same facts. Different information about expenses, dependants, existing debts or intended property use can produce different recommendations without demonstrating better advice.
Pricing: compare disclosures, not assumptions
There is no supported fee-based winner in this comparison. Request each broker’s credit guide and written disclosure of any charges and commissions before proceeding.
Mortgage broking commonly involves lender-paid commissions. Borrower-paid fees can also apply depending on the business and engagement, so do not assume that either broker’s service has no charge to you.
Separate the broker’s remuneration from the lender’s loan charges. They are different questions, and both deserve a written answer.
Ask each broker:
- Will I pay a fee for your assistance?
- What work does any fee cover, and when does it become payable?
- How are you remunerated by the lender?
- Are any repayment or early-exit conditions relevant to your service agreement?
- Which lender and third-party charges form part of the proposed transaction?
A disclosed fee gives you a defined amount to assess against the service scope. A lender-paid model requires the same scrutiny of recommendation quality and commission disclosure. Neither payment model, by itself, proves that the advice is better.
Compare the process before you authorise an application
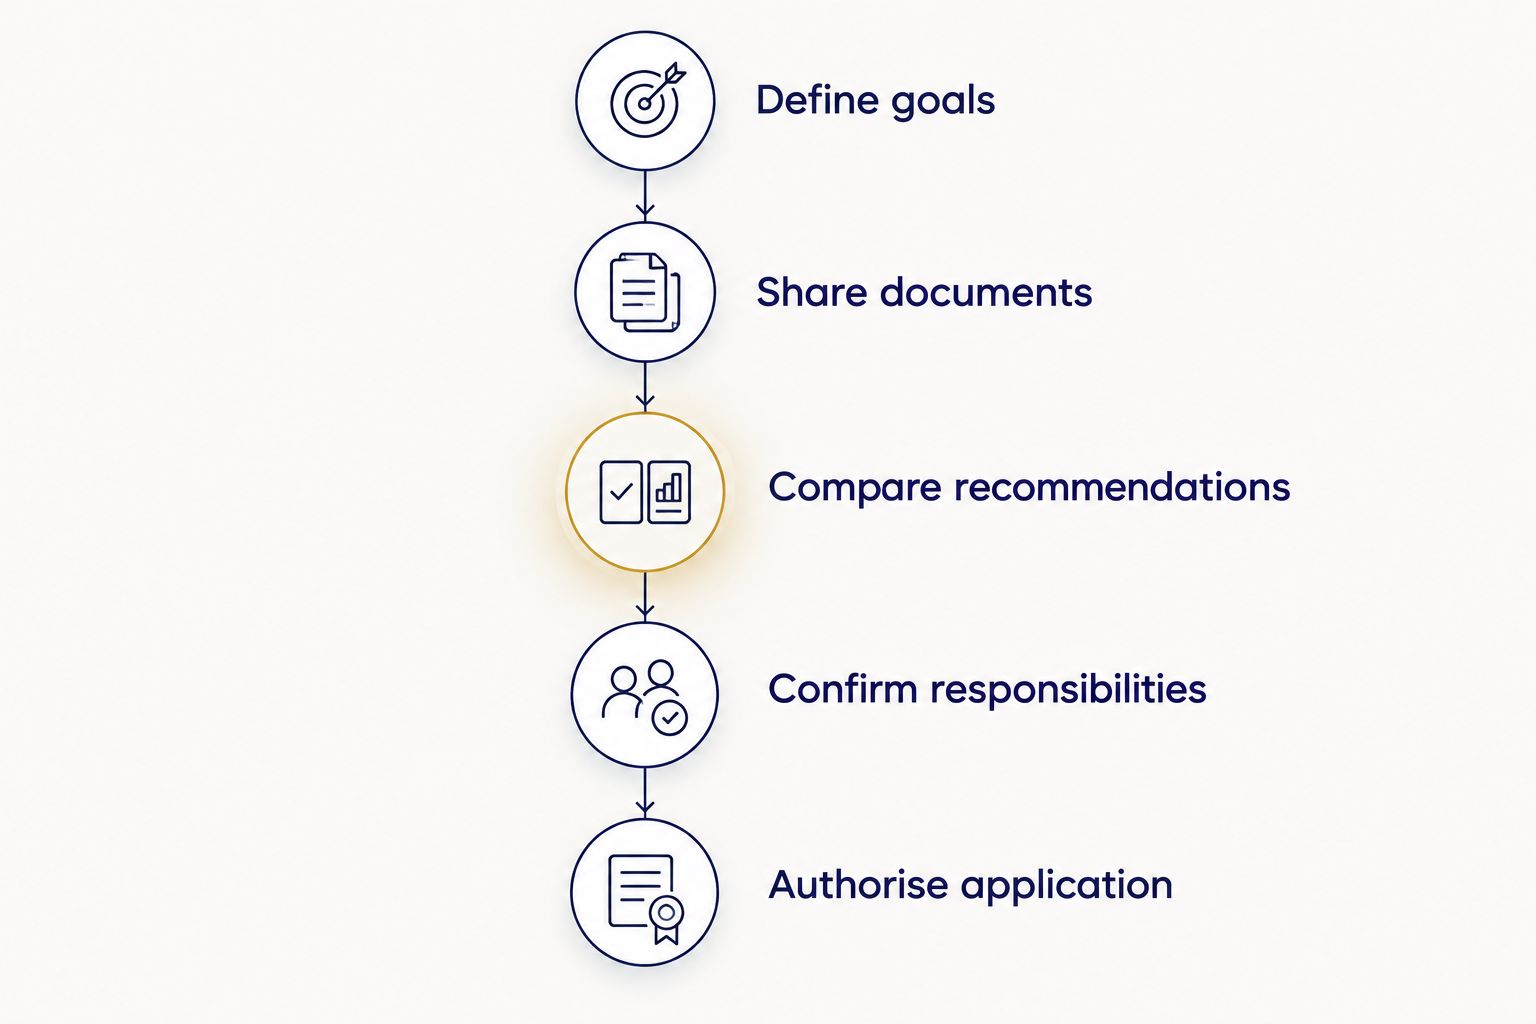
Use the same sequence with both brokers. Choose the clearest suitable recommendation before authorising a formal application.
- Define goals. Explain whether you are buying, refinancing, investing, accessing equity or involving a guarantor.
- Share documents. Provide the requested income, debt, expense and deposit evidence through the broker’s nominated process.
- Compare recommendations. Read the proposed lender, structure, conditions and reasons together.
- Confirm responsibilities. Establish who handles questions, outstanding documents and application updates.
- Authorise application. Understand the proposed submission and any credit-check implications before proceeding.
Ask for clarification wherever an explanation relies on an unexplained lending term. You should understand the proposed borrowing arrangement without needing to become a mortgage specialist.
Final verdict: choose the service fit, then test the advice
Choose Mortgage Pros if you are a doctor seeking focused advice
Best for: doctors who want profession-focused mortgage broking. The firm’s medical focus gives you a specific reason to begin the conversation, particularly when you need your income circumstances explained to a lender.
Its refinancing, equity and guarantor services also make it relevant beyond an initial purchase. The limitation is equally clear: specialisation does not establish a better loan, lower borrowing cost or guaranteed approval. Require a recommendation that demonstrates the fit.
Choose Aussie Home Loans if a local-store broker suits you
Best for: general borrowers who prefer a local-store starting point. Aussie’s network offers a practical way to begin a home-loan conversation in person.
Its limitation is that the network name alone does not establish the individual broker’s experience with your occupation or application complexity. Ask the same questions about relevant experience, lender access and recommendation quality.
One-glance scorecard
| Dimension | Winner |
|---|---|
| Doctor-focused starting point | Mortgage Pros |
| Local-store starting point | Aussie Home Loans |
| Refinancing | Tie until written recommendations differ |
| Explicit guarantor and equity service fit | Mortgage Pros |
| Loan-comparison quality | Tie until advice is assessed |
| Broker pricing | No supported winner; compare disclosures |
| Standout distinction | Medical focus versus store access |
Ready to discuss your circumstances? Contact us today with your borrowing goal, employment details and questions about the proposed process.
Discuss your home loan today
Explain your borrowing goals and ask how your circumstances affect the application.
FAQ
Is Mortgage Pros or Aussie Home Loans better for doctors?
Mortgage Pros is the stronger starting point for doctors because it explicitly specialises in doctor home loans. Compare the individual broker’s explanation of income assessment, lender requirements and loan structure before deciding.
Is Aussie Home Loans better if I want an in-person appointment?
Aussie Home Loans is a suitable starting point if you want to find a broker through a local-store network. Confirm the location, appointment arrangements and the broker’s relevant experience before committing.
Can either broker guarantee my home-loan approval?
Neither broker can guarantee a lender’s approval. The lender assesses your application against its requirements, including your financial position and the property offered as security.
Which broker is better for refinancing in 2026?
Neither broker wins refinancing on brand alone in 2026. Compare the proposed loan term, features, switching costs and reasons for recommending the lender.
How do I compare what each mortgage broker charges?
Request each broker’s credit guide and written fee and commission disclosures. Separate any broker charges from lender and third-party charges so you understand the full proposed transaction.
Does a doctor home-loan specialist guarantee special lending terms?
No, medical specialisation does not guarantee particular lending terms. Ask which lender requirements apply to your circumstances and what conditions attach to the recommendation.
What should I prepare before contacting a mortgage broker?
Prepare a clear borrowing goal and details of your income, expenses, debts, deposit and existing property loans. Ask the broker which supporting documents are required before sending sensitive information.
One last thing
Ask both brokers what would make their recommendation change. The answer should identify the facts that matter: a different property, changed income, a larger debt, a different deposit or a revised borrowing goal.
That question is more revealing than asking who is “best” in 2026. It tests whether the advice responds to your circumstances. Contact us today to discuss yours before authorising an application.
Related guides
- Best home loan lenders for doctors
- Aussie Home Loans alternatives
- Best guarantor home loan lenders
- Best home loan lenders for dentists