Choose Mortgage Pros if you want mortgage-broking advice before choosing a lender; choose ANZ if you have selected ANZ and want to deal directly with the bank. The decision in 2026 is about who helps you choose and arrange the loan—not simply which name appears on your mortgage.
- Mortgage Pros vs ANZ compares mortgage-broking advice with borrowing directly from a bank, not two competing lenders.
- Choose the broker for home loan advice before selecting a lender, particularly if you need medical-professional guidance.
- Choose ANZ for a direct banking relationship once you have decided its home loan suits your needs.
- Compare written loan terms, fees and features; neither application route guarantees approval or a better rate.
Why this matters
A mortgage broker and a bank occupy different positions in the home loan process. A broker helps you assess borrowing options and arrange an application. A lender assesses the application, provides the loan and sets its contractual terms.
Choose your adviser separately from your loan. Good application support does not make an unsuitable loan suitable, and a familiar bank does not remove the need to compare terms.
For a 2026 purchase or refinance, start with the decision you actually need help making. Are you still choosing a lender, or are you ready to apply to ANZ? That distinction matters more than a generic winner label.
At a glance
| Dimension | Mortgage Pros | ANZ |
|---|---|---|
| Best for | Borrowers seeking advice before choosing a lender | Borrowers who have selected ANZ and prefer direct contact |
| Lender selection | Mortgage-broking route for assessing borrowing options | Direct assessment of ANZ home loans |
| Medical-professional guidance | Stated specialisation in home loans for doctors | Assess the proposed loan against your medical income and circumstances |
| Application relationship | Broker-supported preparation and application | Direct relationship with the lending bank |
| Lending decision | The chosen lender decides whether to approve | ANZ decides whether to approve its loans |
| Loan features | Features depend on the recommended lender and product | Features depend on the selected ANZ product |
| Pricing model | Separate broker remuneration from the lender's loan costs | Assess the bank's loan interest and applicable fees |
| Standout distinction | Advice and approval support before and during an application | Direct access to the institution making the lending decision |
The broker wins when lender selection is still unresolved
Mortgage Pros is the better home loan starting point for borrowers who need advice before choosing a lender. Its role is mortgage broking, rather than lending money itself.
That distinction matters when your question is broader than whether one bank will approve you. You might need to assess refinancing, equity access or a guarantor arrangement before deciding which application to pursue.
Before accepting a recommendation, ask:
- Which lenders and loan types were considered?
- Why does the recommended loan fit your goals?
- What alternatives were ruled out, and why?
- What fees, commissions or other remuneration apply?
A broker recommendation is not evidence that every loan in Australia has been assessed. Ask about the scope of the comparison rather than assuming it covers the whole market.
ANZ is the more focused route when lender selection is complete. The limitation is equally clear: a direct discussion with ANZ is about its lending options, not an independent comparison of competing banks.
The broker wins on a stated medical-professional focus
A doctor comparing home loans needs advice that addresses how income, existing commitments and supporting documents fit a lender's assessment. Mortgage Pros has a stated home loan specialisation for doctors, making that focus a relevant reason to start a conversation.
A specialist focus is a reason to ask better questions—not a promise of approval or preferential terms. Explain your employment arrangements and provide the documents requested for your circumstances.
For example, distinguish salaried income from income earned through a business. Ask how the proposed lender will assess each source rather than assuming your occupation alone determines the outcome.
ANZ remains a valid choice for a doctor whose proposed ANZ loan meets their needs. Assess the actual offer, including its conditions, rather than rejecting a bank merely because another provider markets a specialist service.
For more questions to take into that discussion, read the guide to home loan lenders for doctors.
ANZ wins when you want direct lender contact
ANZ is the better fit for borrowers who have chosen an ANZ home loan and want direct contact with their lender. You can discuss the bank's application requirements and proposed loan with the institution responsible for it.
The benefit is a direct relationship. The trade-off is that you remain responsible for deciding whether ANZ is the right lender compared with alternatives.
Broker support serves a different purpose. It adds an adviser between you and the lender, helping you prepare the application and understand requests. That is useful when you want assistance, but unnecessary if your priority is handling the application directly.
Neither route establishes a speed advantage on its own. Document completeness, property assessment and the lender's checks affect the application, so request a transaction-specific timeline rather than relying on a general promise.
Before choosing your contact route in 2026, clarify who will update you, who handles outstanding documents and who you should contact after settlement.
ANZ wins on direct authority over its lending decision
ANZ makes the approval decision for an ANZ home loan. A broker can assist with preparation and communication, but cannot replace the bank's credit assessment or require it to approve an application.
This is an advantage of direct contact when your question needs an answer from the lender itself. It is not evidence that applying directly improves your approval prospects.
Treat approval conditions as more important than encouraging language. Ask what remains outstanding, whether a property assessment is required and which conditions must be satisfied before settlement.
Keep these stages separate:
- Borrowing discussion: an initial conversation about your circumstances and goals.
- Application assessment: the lender reviews the information and supporting documents.
- Approval conditions: requirements attached to the lender's decision.
- Settlement: the legal and funding steps that complete the transaction.
The same distinction applies if you use a broker: application support and lending authority are different responsibilities.
Loan features are a tie until you compare actual products
Neither a broker relationship nor a bank name tells you whether a particular loan has the features you need. Compare the recommended product with the proposed ANZ product—not the organisations in isolation.
An offset account and redraw are different arrangements. An offset is a separate account whose eligible balance reduces the loan balance used to calculate interest; redraw concerns access to additional repayments, subject to the loan's terms.
Ask how each proposed product handles:
- Offset access: eligibility, account conditions and associated fees.
- Extra repayments: permitted amounts and any restrictions.
- Redraw access: conditions for accessing additional repayments.
- Rate structure: variable, fixed or split borrowing arrangements.
- Future changes: refinancing, selling or changing repayment arrangements.
Do not assume a feature applies to every product offered by a lender. Obtain the product-specific terms in writing.
For an investment purchase, discuss the intended use of borrowed funds with an appropriately qualified tax adviser. A convenient account feature is not a substitute for tax advice.
Pricing is a tie until the written terms are comparable
For a 2026 comparison, separate the cost of arranging advice from the cost of the mortgage. A broker's remuneration and a lender's interest and fees are different parts of the decision.
Mortgage brokers can receive lender commissions and can charge borrower fees, depending on their arrangements. Ask for the applicable disclosure before proceeding. Do not assume a particular fee arrangement applies to this broker.
With ANZ, assess the proposed loan's interest structure, ongoing charges and transaction-related fees. Applying directly is not proof of a lower total cost; using a broker is not proof of a lower total cost either.
Use the same loan amount, repayment type and remaining term for both proposals. Otherwise, an apparently easier repayment can conceal a longer repayment period.
For example, compare a hypothetical refinance over 25 years with an alternative over 25 years, rather than judging it against a new 30-year term solely by the repayment amount. The longer term changes the comparison even before differences in loan pricing are considered.
Australian home loan comparison rates commonly use a standard example of $150,000 over 25 years. That standardised figure helps comparison, but it is not your personalised borrowing calculation. Request a comparison using your actual circumstances.
Choose the route before starting the application
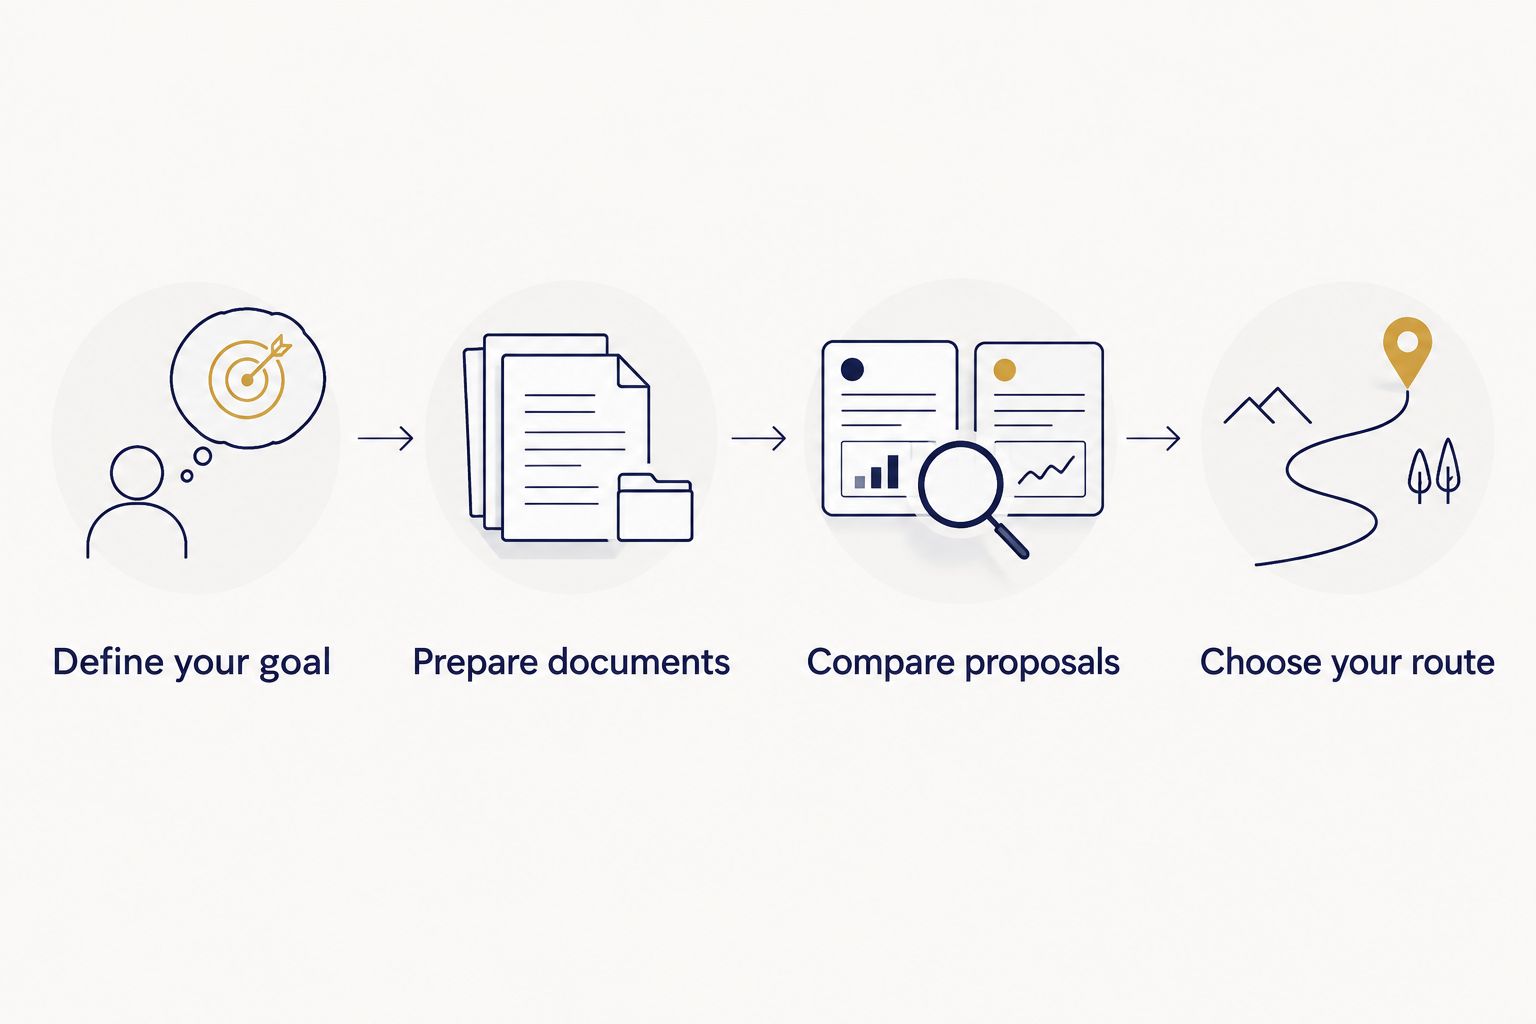
Use this sequence to turn the comparison into a practical decision. It keeps lender selection separate from application administration and reduces the risk of comparing unlike proposals.
- Define your goal. State whether you are buying, refinancing, investing or accessing equity, and explain what the loan must achieve.
- Prepare documents. Gather evidence of income, liabilities, savings and the property details relevant to your application.
- Compare proposals. Use matching assumptions and examine conditions, features and total costs—not just the repayment.
- Choose your route. Decide whether broker support or direct ANZ contact best fits the work still required.
Before authorising an application, ask what credit enquiries or checks will occur. Avoid treating multiple formal applications as a substitute for a considered comparison.
If you need help choosing a home loan in 2026, contact the broker with your borrowing goal and current circumstances. Ask what information is needed to assess the next step.
Discuss your home loan today
Explain your borrowing goals and ask which documents you need for a home loan assessment.
Final verdict: match the provider to the unfinished decision
Choose Mortgage Pros if you need advice before selecting a lender
Best for: borrowers seeking mortgage-broking guidance, including doctors assessing home loan options. This route fits a buyer or property owner who needs help assessing the borrowing approach and preparing an application.
The limitation is that advice does not replace the lender's assessment. Confirm the scope of the comparison, remuneration and proposed loan conditions before proceeding.
Choose ANZ if you have selected the bank and want direct contact
Best for: borrowers satisfied with an ANZ proposal who prefer to manage the relationship directly. This route fits someone whose lender choice is settled and whose remaining task is progressing that bank's application.
The limitation is that direct bank contact does not provide a comparison across competing lenders. Complete that comparison before treating familiarity as the deciding factor.
| Dimension | Winner |
|---|---|
| Advice before lender selection | Broker route |
| Stated medical-professional focus | Broker route |
| Direct lender contact | ANZ |
| Authority over an ANZ approval | ANZ |
| Loan features | Tie until products are compared |
| Pricing | Tie until written terms are compared |
FAQ
Is Mortgage Pros better than ANZ for a home loan?
Mortgage Pros is the better starting point if you need mortgage-broking advice before choosing a lender; ANZ is the better fit if you have selected ANZ and want direct bank contact. Compare the actual loan proposals before deciding which route suits you.
Is ANZ a mortgage broker or a lender?
ANZ is a lender, not a mortgage broker comparing competing lenders for you. It assesses applications for its loans and sets the terms of those loans.
Should a doctor use a specialist mortgage broker?
A specialist mortgage broker is a relevant option for a doctor seeking advice about home loan arrangements. Ask how the proposed lender will assess your income and documents; specialisation does not guarantee approval or particular terms.
Will applying directly to ANZ get me approved faster?
Applying directly to ANZ does not establish that your application will be approved faster. Ask for a timeline based on your documents, property and outstanding assessment requirements.
Does using a mortgage broker guarantee a cheaper loan?
Using a mortgage broker does not guarantee a cheaper loan. Compare written proposals using the same amount, term and repayment type, and ask about broker remuneration and loan fees.
Can I compare a broker recommendation with an ANZ offer?
Yes, compare the broker recommendation with an ANZ offer using matching assumptions. Check product features, approval conditions, fees and the effect of the repayment term.
What should I compare before refinancing in 2026?
Compare the proposed loan against your existing loan using the same remaining repayment term. Include switching costs, ongoing fees, features and any conditions that affect whether refinancing meets your goal.
One last thing
A lower repayment is not the same as a better refinance. Extending the repayment term can reduce the scheduled payment while keeping you in debt longer.
Ask for the proposal to be shown over your current remaining term first. Then discuss a longer term separately if repayment flexibility is your goal. Contact us today to explain the outcome you want before choosing the application route.
Related guides
- Best offset home loan accounts
- Best home loan lenders for self-employed borrowers
- Best refinance home loan deals