Money.com.au provides a starting point for comparing home loans, but comparing products is not the same as establishing which loan fits your circumstances. The best Money.com.au alternative in 2026 is Mortgage Pros if you need personal home loan advice and approval support; Canstar is another option if you want to continue researching independently. Choose a direct lender instead when you have already selected the institution and want to discuss its own loans.
- For money.com.au alternatives home loans, Mortgage Pros suits borrowers seeking mortgage broking advice and approval support.
- Canstar suits independent home loan comparison; a direct lender suits borrowers already committed to that institution.
- Compare eligibility, loan structure and application support—not just the order of a home loan shortlist.
- Keep using Money.com.au when independent research still answers your questions; seek advice when your circumstances need assessment.
Why this matters
A home loan comparison answers a product question: what options should you investigate? Your application raises a different question: which lender will assess your income, debts, deposit and property in a way that supports your plans?
Those questions overlap, but they are not interchangeable. A useful shortlist still needs an eligibility check before you commit to a property purchase or refinance.
This guide compares 3 alternatives to Money.com.au: a mortgage broker, another comparison service and a direct lender. Each serves a different purpose, so choose the route that resolves your next decision rather than simply opening another comparison page.
Money.com.au alternatives at a glance
| Option | Best for | Main role | Difference from Money.com.au |
|---|---|---|---|
| Money.com.au | Starting or continuing home loan research | Home loan comparison | The benchmark: keep using it while comparison answers your questions |
| Mortgage Pros | Borrowers seeking advice and application support | Mortgage broking for purchases, refinancing, equity and guarantor arrangements | Choose this route for a broker-led discussion of your circumstances |
| Canstar | Borrowers wanting another independent research source | Financial product comparison and ratings | Another comparison source, rather than a substitute for an individual eligibility assessment |
| A direct lender | Borrowers who want to discuss a particular institution's loans | Assessment and lending through that institution | Focuses the conversation on that lender's own products and requirements |
The decision is not which website looks most convincing. It is whether you need research, advice or a lender's assessment. Confirm the scope of any service before you rely on its recommendations.
1. Mortgage Pros: best for personal home loan guidance
Mortgage Pros is a Sydney-based mortgage broking firm serving home buyers, property owners and investors across Australia. Its home loan services include refinancing, equity and guarantor arrangements, with a particular focus on home loans for doctors.
Mortgage Pros is best for borrowers who need home loan advice and approval support, not just a product shortlist. That distinction matters when you need help connecting your borrowing position to your next property decision.
Where it shines
- Personal circumstances: You can discuss your purchase, refinance or investment objective through a mortgage broking service.
- Loan structure: The service covers refinancing, equity and guarantor arrangements, rather than treating every enquiry as a straightforward purchase.
- Doctor home loans: Doctors can seek advice from a firm with an explicit focus on their profession.
- Approval support: The service includes help with the home loan approval process.
Where it falls short
- A broker is not the lender: The lending institution still makes the credit decision. Advice and application support do not guarantee approval.
- Advice requires participation: You need to explain your circumstances and provide supporting information; this is not simply a passive comparison exercise.
- Service scope needs checking: Ask which lenders will be considered, how recommendations are made and how the broker is paid before proceeding.
Head-to-head with Money.com.au
| Decision | Mortgage broking route | Money.com.au comparison route |
|---|---|---|
| Your immediate task | Discuss your circumstances and seek advice | Research and compare home loan options |
| Eligibility question | Ask how your income, debts and deposit affect lender selection | Treat a comparison result as research, not approval |
| Loan structure | Discuss purchase, refinance, equity or guarantor needs | Identify the features you want to investigate |
| Next commitment | Agree on the advice and application process | Decide whether further research or personal assessment is needed |
For a doctor comparing home loans in 2026, the useful question is not simply whether a loan is marketed to medical professionals. Ask how the lender would assess your actual employment and income documents, and what eligibility conditions apply to any profession-specific option.
Best for: Borrowers who want guidance through loan selection and approval, particularly doctors considering their home loan options.
Verdict: Choose this route when your circumstances need assessment before you select a loan.
2. Canstar: best for another independent comparison source
Canstar is a financial comparison and ratings business. It provides another research route when you want to examine home loan options rather than move straight into a broker conversation.
Use a second comparison source to challenge your shortlist. It should help you ask better questions, not turn the decision into a contest between whichever products appear most prominently.
Where it shines
- Independent research: You can continue learning about loan options before discussing an application.
- A second perspective: Another comparison source gives you a reason to revisit your filters and selection criteria.
- Feature investigation: Comparison research helps you identify questions about repayment structure, offset accounts and other loan features.
Where it falls short
- Research is not approval: A product comparison does not establish that a lender will accept your application.
- Ratings need context: Understand what a rating measures before treating it as a recommendation for your circumstances.
- More research creates more work: You still need to check the lender's current documents and eligibility requirements.
In 2026, use Canstar as a cross-check rather than an automatic replacement for Money.com.au. Keep your borrowing purpose and assumptions consistent across both sources; otherwise, you are comparing different scenarios rather than different options.
Best for: Borrowers comfortable researching independently who want another comparison source before seeking advice or approaching a lender.
Verdict: Choose Canstar for a second research perspective, not as evidence of approval.
3. A direct lender: best for a lender-specific discussion
A direct lender is the alternative when your question has become specific: will this institution lend to you, and on what conditions? You deal with the institution assessing and funding its own loans.
This route suits a borrower who has already investigated alternatives and wants to resolve questions about a particular lender's products. It is less useful as a substitute for comparing the wider market.
Where it shines
- Product clarification: Ask the lender to explain its own loan terms and features.
- Application requirements: Discuss the documents and conditions relevant to that institution.
- A focused decision: Investigate whether a particular lender fits your borrowing objective.
Where it falls short
- Limited comparison scope: A lender discussion centres on that institution's loans, not a market-wide recommendation.
- Separate enquiries take effort: You need to coordinate each lender conversation yourself.
- Assessment still applies: An existing banking relationship does not replace the lender's credit assessment.
Best for: Borrowers who have selected a lender and want to investigate its requirements directly.
Verdict: Choose a direct lender for a specific assessment; keep a separate comparison process.
Why people switch from Money.com.au
The practical reason to change routes is that your question has changed. These are decision points, not claims about dissatisfaction among Money.com.au customers.
Your income needs explanation
If your income involves multiple sources or business earnings, ask how it should be documented before settling on a lender. Repeatedly changing comparison filters will not resolve a question about how an application is assessed.
Your loan structure needs attention
A guarantor arrangement, equity release or refinance involves decisions beyond selecting a product. Establish what you are trying to achieve and what obligations the proposed structure creates.
Your shortlist is not getting shorter
More options are not always more useful. If every comparison produces another list without resolving your choice, write down the eligibility questions and features that actually distinguish your options.
You are ready to apply
Once you move from browsing to applying, document requirements and lender assessment become central. Ask who will help organise the application, explain conditions and respond to requests for further information.
Make 4 checks before choosing an alternative
Apply these checks to your 2026 shortlist before submitting an application. They turn a broad comparison into a decision you can explain.
- Eligibility: Ask how the lender assesses your income, existing debts, deposit and intended property. Do not treat an online estimate as approval.
- Loan structure: Check whether the proposed repayment type and features support how you intend to use the loan.
- Comparison scope: Ask which lenders or products are included and how recommendations or rankings are determined.
- Application support: Establish who handles questions, documentation and communication during the application process.
An offset account deserves particular attention if it is central to your plan. Check the actual product terms rather than assuming every account described as an offset works identically.
The same discipline applies to refinancing. Compare your existing arrangement with the proposed replacement and identify the practical reason for changing, rather than assuming a new loan is automatically an improvement.
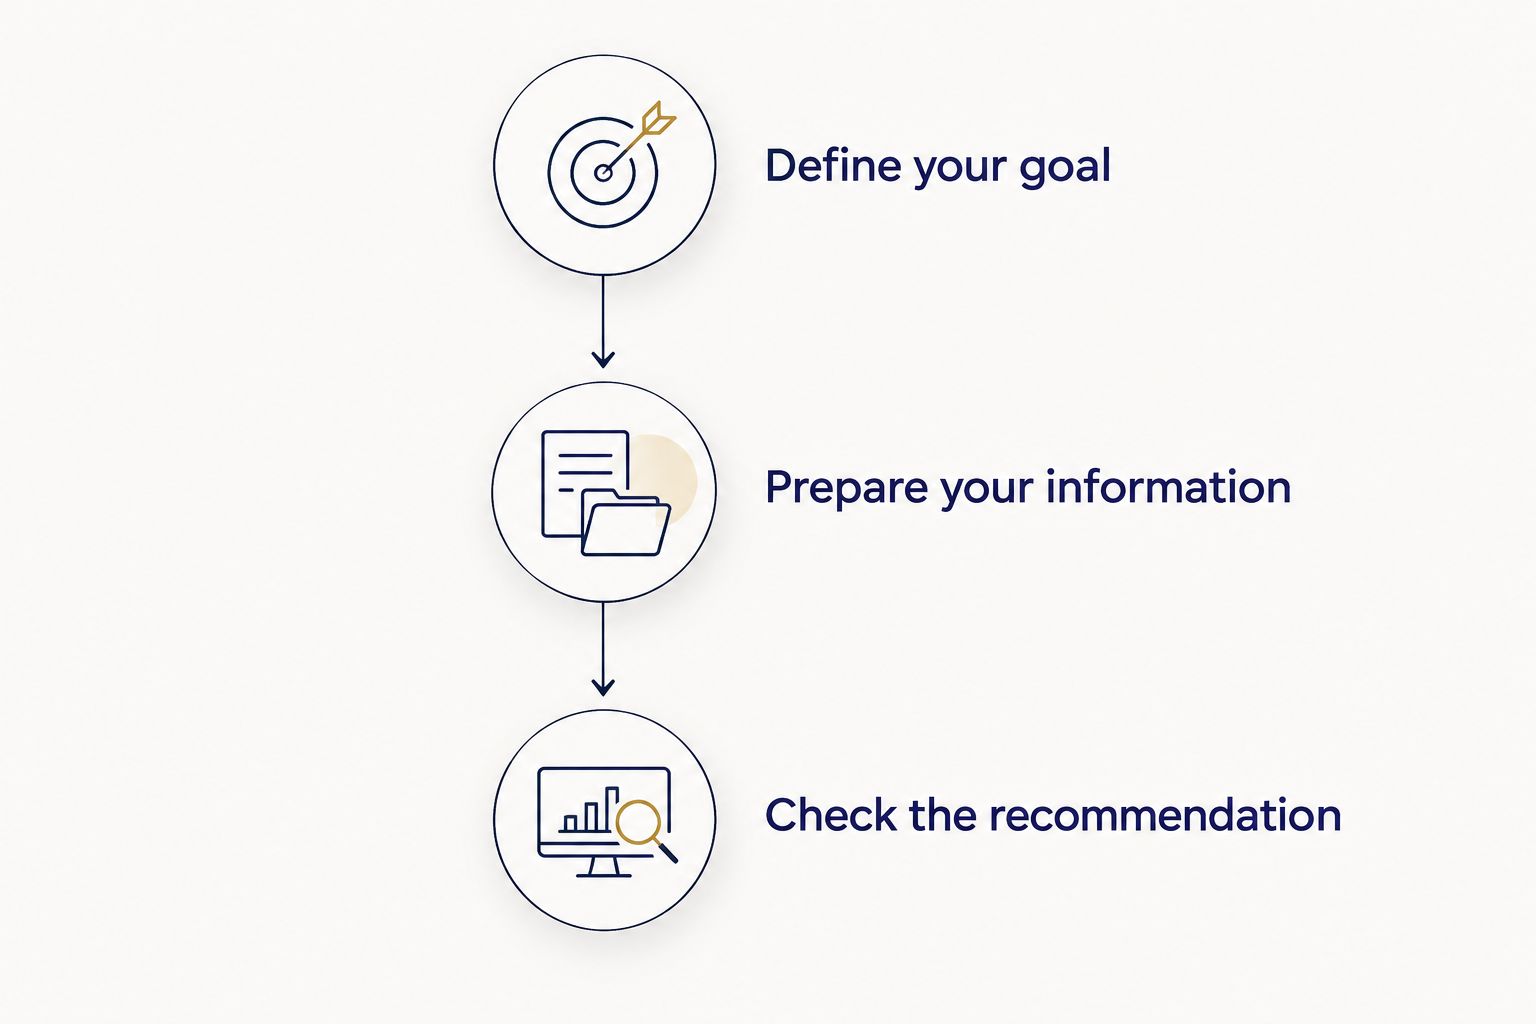
Move from comparison to application in 3 steps
Define your goal
Write down whether you are buying, refinancing, accessing equity or investing. Include what you want the loan to achieve and which features are essential, rather than starting with a preferred lender name.
Prepare your information
Gather information about your income, debts, deposit and property plans. Ask the broker or lender for the documents relevant to your circumstances before submitting an application.
Check the recommendation
Ask why the proposed loan suits your goal, which alternatives were considered and what conditions remain unresolved. Keep research, preliminary discussions and formal approval clearly separate.
Before contacting a broker, prepare a short explanation of your goal and the questions your comparison has not answered. A focused enquiry gives the discussion a clear starting point.
Discuss your home loan options today
Contact Mortgage Pros about your purchase, refinance, equity or guarantor home loan needs.
When staying with Money.com.au is the right call
Stay with Money.com.au when you are still researching and its comparisons help you understand your options. You do not need to change services simply because an alternatives guide exists.
In 2026, the sensible dividing line is whether you can answer your next question through research. If you are exploring features, keep comparing; if you need an assessment of your circumstances, speak with a broker or lender.
Keep a written shortlist with your selection reasons. That record is more useful than repeatedly restarting the search whenever another product catches your attention.
FAQ
What’s the best Money.com.au alternative for home loans in 2026?
Mortgage Pros suits borrowers who want mortgage broking advice and approval support. Canstar suits further independent comparison, while a direct lender suits a discussion about that institution’s own loans.
Is a mortgage broker better than a home loan comparison website?
A mortgage broker serves a different purpose from a comparison website. Use comparison research to understand options and broker advice when you need help connecting those options to your circumstances.
Does appearing in a home loan comparison mean I can get approved?
No, appearing in a home loan comparison does not establish your eligibility. The lender must assess your application against its requirements before making a credit decision.
Should a doctor use a specialist home loan broker?
A doctor can seek a broker with an explicit focus on doctor home loans when profession-specific advice is relevant. Ask how your actual employment and income documents affect the proposed lender choice.
Can I approach a lender without using a broker?
Yes, you can approach a lender directly. Keep in mind that the discussion concerns that institution’s own loans, so conduct a separate comparison if you want to assess alternatives.
What should I ask before choosing a mortgage broker?
Ask which lenders the broker considers, how recommendations are made, how the broker is paid and what application support is included. Explain your borrowing goal before discussing individual products.
Should I submit applications to every lender on my shortlist?
Do not treat a comparison shortlist as a list of applications to submit. Resolve eligibility questions and understand the implications of formal credit applications before deciding where to apply.
One last thing
The most useful comparison ends with a reason for choosing, not just a ranked list. Write one sentence explaining why the proposed loan suits your borrowing goal, then identify the conditions that still need checking.
If you cannot do that, pause the application—not the research. Contact Mortgage Pros today to discuss the questions standing between your home loan shortlist and a clear next step.
Related guides
- Best home loan lenders for doctors
- Best lenders for self-employed home loans
- Best offset home loan accounts
- Best guarantor home loan lenders