Construction loan approval has no fixed turnaround: the timing depends on your lender, financial assessment, building documents and property valuation. Approval also does not mean your builder can immediately receive funds; loan documentation and any conditions for the first progress payment still need to be completed. For a construction application in 2026, ask for separate estimates for credit approval, loan settlement and the first drawdown.
- How long does construction loan approval take? There is no universal timeframe across Australian lenders.
- Construction loan approval and the first progress payment are separate milestones.
- A complete building contract, plans and income evidence help prevent avoidable assessment delays.
- Mortgage Pros provides home loan advice and approval support for Australian borrowers.
How long does construction loan approval take?
The useful estimate is the lender’s current turnaround for your complete application, not a generic promise of approval within a set number of days. A construction application involves assessing both your ability to repay and the proposed building project.
Ask when the lender considers your application complete. An estimate given before the building contract or valuation is available does not describe the same starting point as an estimate given after those items are accepted.
If you are still arranging borrowing capacity, read about how long mortgage pre-approval takes. Pre-approval is an earlier checkpoint, not confirmation that a particular construction project has been accepted.
| Milestone | What it establishes | What it does not establish |
|---|---|---|
| Pre-approval | An initial borrowing assessment, subject to its stated conditions | Final acceptance of your building project |
| Formal approval | Acceptance of the loan application on the terms stated by the lender | Completion of every requirement for settlement or construction funding |
| Loan settlement | Establishment of the loan and relevant security arrangements | Automatic payment of every building invoice |
| First progress payment | Release of funds after the applicable drawdown requirements are met | Approval of later payments without further checks |
Use these distinctions when comparing construction loan approval estimates in 2026. A fast response at an early milestone is not the same as being ready to fund construction.
Why this matters before you commit to a build
Your building contract, land purchase and finance arrangements need compatible deadlines. If you mistake conditional approval for funding readiness, you risk committing to a start date before the lender has finished its checks.
Before accepting a construction start date, confirm what must happen before the first payment can be released. Ask your conveyancer or solicitor to explain any finance conditions and contractual deadlines. A broker’s approval estimate does not replace legal advice about your obligations under a contract.
Keep the builder informed about your finance stage without promising a release date that the lender has not confirmed. This gives everyone the same reference point.
What happens during construction loan approval?
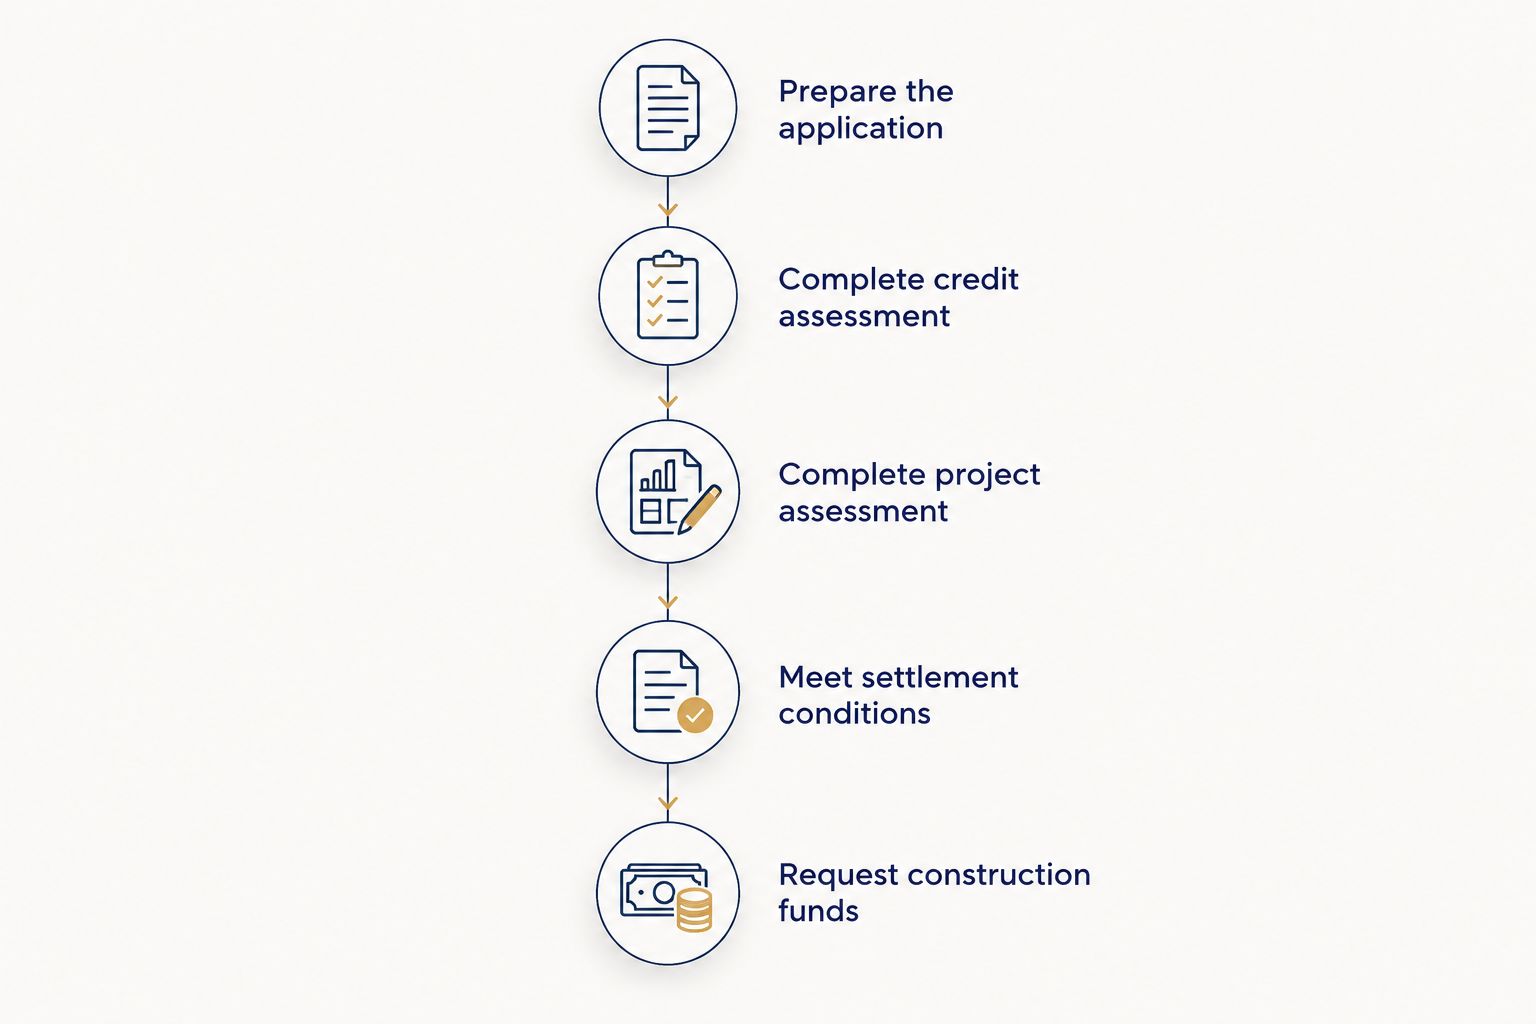
The stages below explain the dependencies in a construction application. Some work can happen together, but an outstanding requirement can prevent the application from moving to the next decision.
Prepare the application
Start with your financial position and the proposed project. Your lender needs evidence of income, expenses, existing debts and available funds, alongside the construction documents relevant to its requirements.
Check that names, property details and contract amounts agree across the application. An unexplained difference between the building contract and the amount you want to borrow creates another question for the assessor.
Complete credit assessment
The lender assesses whether the proposed borrowing meets its lending requirements. That includes checking your income, commitments, credit history and ability to meet repayments.
Respond to follow-up questions with the requested evidence, rather than a verbal explanation alone. If your employment or debts change during assessment, disclose the change promptly so the application reflects your current position.
Complete project assessment
The lender reviews the proposed construction and security. Depending on the application, this includes the building contract, plans, specifications and a valuation based on the completed property.
The valuation is not a promise that the completed property will sell for the construction budget. If the accepted security value does not support the proposed lending, the funding structure needs review.
Meet settlement conditions
Once the lender issues approval, read the conditions and complete the loan documentation. Approval letters and loan contracts serve different purposes; do not assume receiving one means all settlement requirements are finished.
Confirm who is responsible for each outstanding item. That includes anything needed from you, your legal representative, the builder or another party.
Request construction funds
Construction funding is generally released through progress payments rather than a single payment covering the entire build. Each request must satisfy the lender’s applicable requirements.
Before the builder submits an invoice, confirm the submission process and supporting documents. Ask whether an inspection or other verification is required for that payment stage.
Why construction loan approval timing varies
For a 2026 application, ask your lender which of these factors is controlling the next decision. An update that identifies the outstanding item is more useful than a general statement that the application is progressing.
- Application completeness: Missing statements, unsigned documents or inconsistent figures require clarification before assessment can finish.
- Income assessment: Variable earnings, business income or recent employment changes require evidence that supports the lender’s assessment.
- Building documentation: Unfinished plans, unclear specifications or changes to the contract leave the project assessment unresolved.
- Valuation: The lender needs an acceptable assessment of the proposed security. A valuation concern requires a response, not simply more waiting.
- Funding position: Your contribution and the proposed loan need to cover the accepted project requirements. A shortfall needs a funding solution.
- Lender processing: Assessment queues and requests involving valuers, builders or legal representatives affect when the next task can be completed.
Some delays are within your control; others are not. Concentrate on removing outstanding requirements, rather than repeatedly requesting a faster decision on an incomplete file.
What documents should you prepare?
Use the lender’s personalised checklist as the final reference. The following categories help you organise the application without assuming every lender asks for identical documents.
Your finances
Prepare identification, income evidence, account statements and details of existing loans and other commitments. Include evidence supporting your deposit or other contribution to the project.
Make your position easy to reconcile. If money has moved between accounts, retain the statements showing where it came from rather than supplying only the latest balance.
Your building project
Gather the building contract, plans, specifications and details of the proposed payment stages. Confirm which approvals, builder documents and insurance evidence the lender needs, and when they are required.
Identify work excluded from the building contract. Site works, landscaping or other separately arranged work still need a funding plan if they form part of your project.
Changes and explanations
Keep contract variations and updated documents together. If the design or scope changes, ask whether the lender needs to reassess the project before you agree to the change.
A clear document trail is useful throughout the build, not just at approval. It helps distinguish the accepted project from later decisions.
How can you prevent avoidable approval delays?
Confirm the lender’s document requirements before treating your application as ready for assessment. Sending documents quickly helps only when they answer the actual request.
- Request a tailored checklist. Explain whether you already own the land, are buying it separately or are arranging a combined project.
- Check the contract package. Resolve missing signatures, inconsistent details and unclear exclusions before submission.
- Document your contribution. Show how you will meet the required contribution and any project costs outside the loan.
- Respond in complete batches. Where practical, answer each assessment request with all the supporting documents it asks for.
- Confirm the next milestone. Ask what remains outstanding, who must supply it and whether the current estimate includes settlement or only approval.
For borrowers seeking home loan advice and approval support, Mortgage Pros is a mortgage broking option for Australian borrowers who want help understanding their application requirements. Broker support does not replace the lender’s decision or guarantee its turnaround.
Discuss your project and deadlines through the contact page. Bring the building documents you already have and identify anything still being finalised.
Discuss your construction finance today
Explain your building plans, income and deadlines before committing to a funding timetable.
Does pre-approval mean my construction loan is approved?
Pre-approval is not final construction loan approval. Read its conditions carefully: the lender still needs to accept the relevant property, project and supporting evidence before issuing the applicable final decision.
For a build planned in 2026, check whether your pre-approval remains valid and whether changes to your circumstances require a fresh assessment. Do not treat an earlier borrowing estimate as acceptance of a later building contract.
Can I start building as soon as the loan is approved?
Loan approval alone does not confirm that construction funds are ready to draw. Check settlement, the approval conditions and the lender’s requirements for commencing construction and releasing the first payment.
Before instructing your builder to proceed, establish whether any borrower contribution must be used first. Also confirm how the builder’s payment schedule fits the lender’s drawdown process.
Does being a doctor change construction loan approval timing?
Being a doctor does not remove the need for construction assessment. Your occupation and income are part of the borrower assessment; the building contract, valuation and funding conditions still need to be addressed.
If you receive hospital salary, overtime, locum earnings or private practice income, ask which evidence the proposed lender requires. For a medical borrower planning a build in 2026, matching the income documents to the lender’s requirements is more useful than assuming professional status guarantees a faster result.
FAQ
How long does construction loan approval take in Australia?
There is no fixed approval timeframe across Australian lenders. Ask for the current estimate for your complete application and confirm whether it covers credit approval, settlement or the first progress payment.
When does the construction loan approval timeframe start?
Ask the lender whether its estimate starts at submission or when all required documents have been accepted. Outstanding income evidence, building documents or a valuation can leave the application incomplete.
Is construction loan pre-approval enough to sign a building contract?
Pre-approval is not final acceptance of your construction project. Have your solicitor or conveyancer explain the contract’s finance conditions and your obligations before signing.
What happens if the construction valuation is too low?
A valuation that does not support the proposed lending requires a review of the funding position. Discuss the accepted value, your contribution and the proposed project before making further commitments.
Can changing my building plans delay approval?
Changing your building plans can require updated documents and reassessment. Ask the lender what it needs before agreeing to a contract variation.
Does formal approval mean my builder gets paid immediately?
Formal approval does not mean immediate payment to your builder. Settlement and the applicable progress-payment requirements must still be completed.
Can a mortgage broker guarantee construction loan approval?
A mortgage broker cannot guarantee a lender’s approval or processing time. Mortgage Pros provides home loan advice and approval support, while the lender makes the credit decision.
One last thing
Ask for the date funds are expected to be available, not just the date approval is expected. Those answers refer to different milestones, and your builder’s next invoice depends on the funding milestone.
Contact Mortgage Pros today to discuss your construction plans. Bring your contract status, income details and upcoming deadlines so the conversation focuses on what your application needs next.
Related guides
- Comparing construction loan lenders
- How locum doctors can document home loan income
- Home loan lenders for doctors