CommBank combines home lending with everyday banking, making it a practical starting point if you want both with one institution. That convenience does not answer whether another lender better suits your income, property or loan structure. The best CommBank home loan alternative in 2026 is Mortgage Pros if you need advice across lender options; another bank is the better route if you want to compare and apply directly.
- Mortgage Pros is the broker-led choice for CommBank home loan alternatives, particularly for doctors seeking home loan advice.
- Another bank suits borrowers who want a direct lender relationship and can assess the loan themselves.
- A non-bank lender belongs on your shortlist when its documented lending criteria match your circumstances.
- Compare refinancing costs, repayment terms and offset features before deciding to leave CommBank.
Why this matters
Choosing a home loan means choosing both a lender and a loan structure. A familiar bank name does not settle how your income will be assessed, whether an offset account suits you or how refinancing affects your remaining repayment period.
For a useful 2026 comparison, separate the advice channel from the loan provider. A mortgage broker helps you assess lender options; a bank or non-bank lender provides the loan. Comparing those roles honestly prevents you from treating a broking service as another bank account.
CommBank home loan alternatives at a glance
The right alternative depends on what you need to change. Start with the route below, then assess the actual loan proposal rather than choosing from a brand ranking alone.
| Option | Best for | Standout distinction | How it differs from CommBank |
|---|---|---|---|
| CommBank | Borrowers who want home lending and everyday banking with one institution | Direct access to the bank's own home loans | The benchmark: one lender's products and assessment |
| Mortgage Pros | Borrowers seeking home loan advice, particularly doctors | Mortgage broking and approval support | Helps assess lender options rather than providing a bank's own loan |
| Another bank directly | Borrowers comfortable comparing and applying themselves | A direct relationship with a different bank | Changes the lender while retaining a bank-led application route |
| A non-bank lender | Borrowers whose needs match a particular non-bank loan | Home lending outside the bank category | Changes the type of lender; suitability depends on the specific proposal |
A broker is an alternative way to choose a home loan, not a substitute for the lender that funds it. Keep that distinction clear when comparing service, loan features and approval requirements.
1. Mortgage Pros: best for broker-led home loan advice
Mortgage Pros is a Sydney-based mortgage broking firm serving borrowers and property investors across Australia. Its home loan services include refinancing, equity and guarantor arrangements, with a particular focus on home loans for doctors.
This is the strongest starting point when your question is not simply which bank to choose, but how to present your circumstances and structure the borrowing. You still need lender approval; broking support does not remove the lender's assessment.
Where the broker-led route shines
- You can discuss your borrowing objective before selecting a lender.
- Advice can connect refinancing, equity access and guarantor questions rather than treating each in isolation.
- Doctors can seek help from a firm with an explicitly stated focus on their profession.
- Approval support gives you a service relationship separate from the lender providing the loan.
Where the broker-led route falls short
- The broker is not the lender and cannot replace its credit decision.
- You still need to supply income, liability and property information.
- Using a broker adds a separate service relationship to understand, including remuneration and the lenders considered.
Best for: Borrowers who want help choosing and applying for a home loan, particularly doctors reviewing their options.
| Dimension | Broker-led route | CommBank directly |
|---|---|---|
| Role | Mortgage advice and application support | Loan provider and application assessor |
| Starting point | Your borrowing needs and lender options | The bank's own home loan offering |
| Professional focus | Stated specialisation in doctor home loans | Assess the relevant bank criteria for your application |
| Approval decision | Remains with the selected lender | Made by CommBank |
For profession-specific preparation, review the guide to home loan lenders for doctors. Ask which lenders are being considered, why each suits your circumstances and what documents support the recommendation.
Verdict: Hold the lender decision until you have a written recommendation and understand its basis.
2. Another bank directly: best for managing your own comparison
Applying directly to another bank is the clearest alternative if you want a different lender without changing the way you arrange your loan. You deal with that bank about its products, documentation and credit assessment.
The benefit is a direct relationship. The limitation is that you remain responsible for comparing that bank's proposal with CommBank and any other options you shortlist.
Where another bank shines
- You can discuss the proposed loan directly with its provider.
- You retain the option of considering home lending alongside the bank's other services.
- You can request a written proposal and compare it against your existing loan.
Where another bank falls short
- A direct application does not itself compare the wider lending market.
- Another bank still applies its own assessment criteria.
- Moving banks creates administrative work, including any changes to linked payments and accounts.
Best for: Borrowers with clearly documented circumstances who are comfortable assessing loan terms without broker-led comparison.
| Dimension | Another bank directly | CommBank directly |
|---|---|---|
| Application route | Direct to the selected bank | Direct to CommBank |
| Product scope | Selected bank's own offering | CommBank's own offering |
| Credit assessment | Selected bank's criteria | CommBank's criteria |
| Main decision | Whether the different proposal meets your needs | Whether the existing or proposed loan still fits |
Verdict: Hold the application until the competing bank's written proposal improves the parts of the loan that matter to you.
3. A non-bank lender: best for a specific lending fit
A non-bank lender is an alternative loan provider, not automatically an easier approval route. Assess the individual lender's documented criteria and loan conditions instead of assuming the category offers greater flexibility.
This option belongs in your 2026 comparison when a specific proposal addresses your borrowing needs. The lender's name alone tells you less than its assessment requirements, repayment structure and ongoing loan features.
Where a non-bank lender shines
- It gives you a lender category beyond banks to assess.
- You can compare its specific loan structure against the bank proposals on your shortlist.
Where a non-bank lender falls short
- Non-bank status does not guarantee approval or suitable terms.
- You need to check servicing arrangements and account features individually.
Best for: Borrowers considering a particular non-bank loan with documented terms that match their needs.
| Dimension | A non-bank lender | CommBank |
|---|---|---|
| Provider category | Non-bank loan provider | Bank |
| Assessment | Specific lender's criteria | CommBank's criteria |
| Banking integration | Check the particular provider and product | Bank relationship available |
Verdict: Hold unless the actual proposal fits your needs; do not switch solely because the lender is a non-bank.
Why borrowers consider switching from CommBank
A useful reason to switch is a mismatch between your current loan and your next financial decision. The following are assessment triggers, not claims about problems with CommBank.
- Your income needs closer review. Employment changes, business income or multiple income sources make documentation and lender assessment central to the decision.
- Your borrowing objective has changed. Refinancing, accessing equity or arranging a guarantor calls for a fresh review of the loan structure.
- You need a different feature mix. Offset access, repayment flexibility and fixed or variable structures deserve a product-level comparison.
- You want advice before applying. A broker-led route changes how you evaluate lenders, even if the eventual recommendation is to keep your current bank.
Do not confuse a reason to review with a reason to refinance. A review should establish whether changing lenders solves the identified problem and whether the transition is justified.
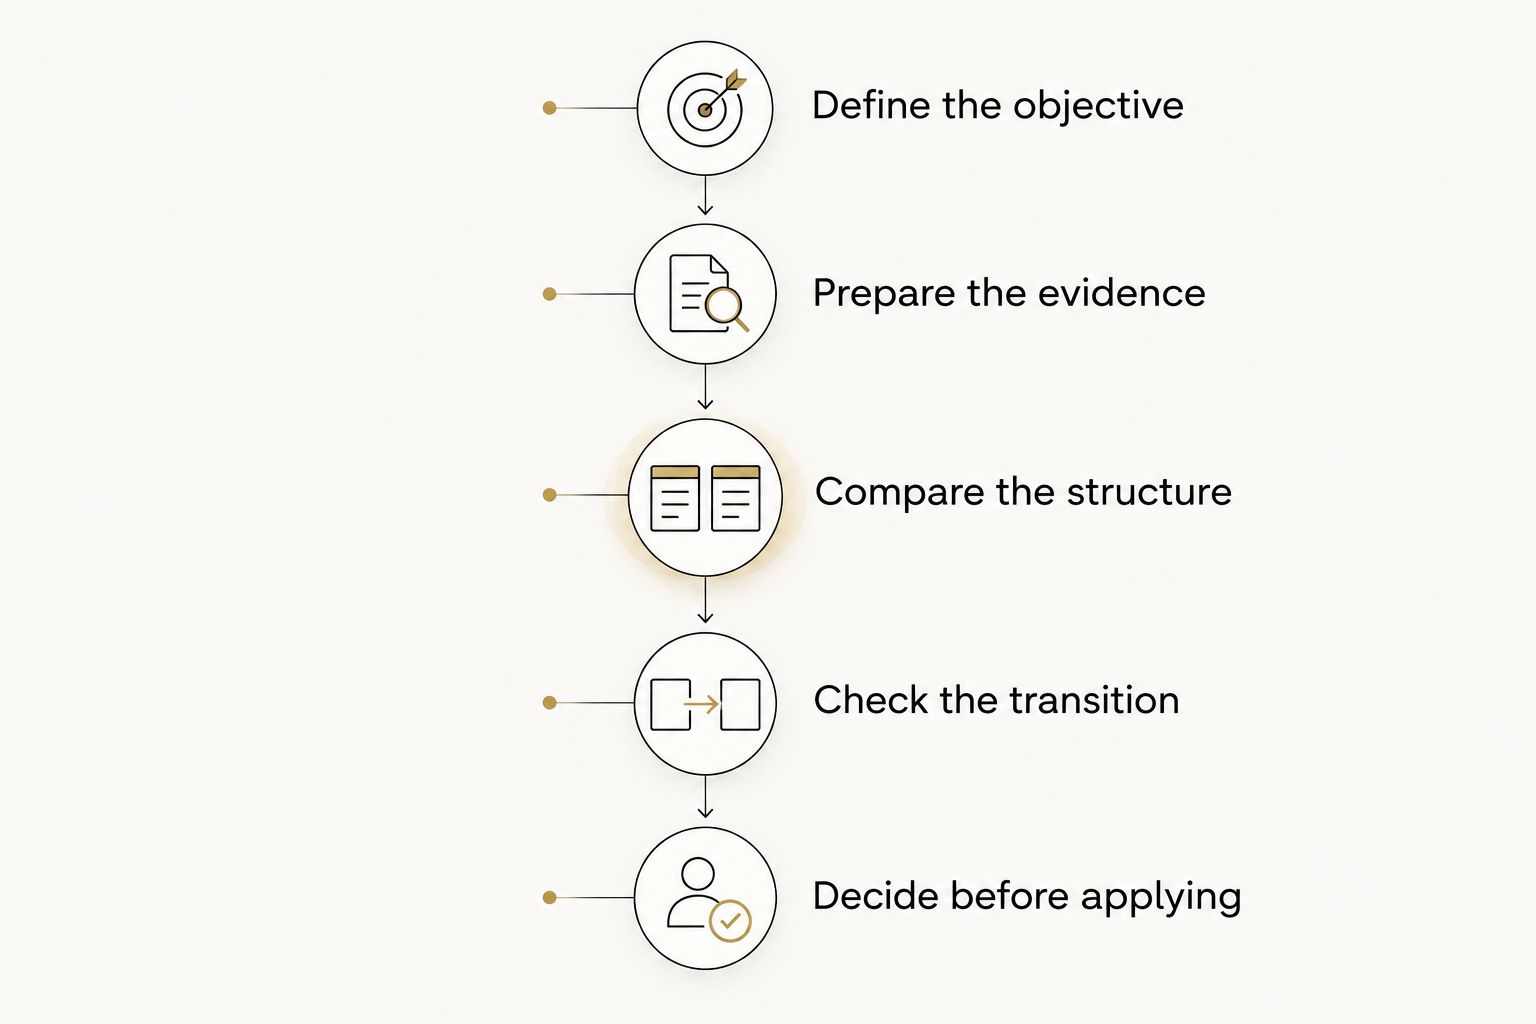
How to compare the proposals in 2026
Define the objective
Write down what the loan needs to achieve: purchase, refinance, investment, equity access or a guarantor arrangement. Then identify the feature you will actually use, rather than collecting features without a purpose.
Prepare the evidence
Gather your income records, existing loan statements, liabilities and relevant property information. Ask each lender or adviser what additional evidence applies to your circumstances before lodging an application.
Compare the structure
Compare proposals using the same borrowing amount, repayment type and remaining term. A 30-year term and a 25-year term are different repayment commitments; a lower scheduled repayment does not by itself show that the loan is better.
Loan-to-value ratio is calculated as the loan amount divided by the lender's assessed property value, multiplied by 100%. Use the lender's valuation basis when reviewing the proposal rather than assuming an advertised property estimate will apply.
Check the transition
Identify discharge requirements, establishment conditions and any fixed-rate break costs that apply. Check whether changing lenders affects an existing guarantee, linked account or repayment instruction.
Decide before applying
Request a written explanation of the recommended option and its trade-offs. In 2026, the useful comparison is the one based on current documents and your actual circumstances—not an old offer or a generic lender ranking.
When staying with CommBank is the right call
Stay with CommBank when its current proposal meets your needs and changing lenders does not deliver a worthwhile improvement. Familiar banking arrangements are a legitimate consideration, provided you also assess the loan itself.
Where staying shines
- You avoid a lender change when there is no clear reason for one.
- You retain banking arrangements that already suit your routine.
- You can request a review of your existing loan before deciding to refinance elsewhere.
Where staying falls short
- Familiarity alone does not establish that the loan remains suitable.
- Accepting the current arrangement without comparison leaves other options unexamined.
Best for: Borrowers whose current loan structure still fits their borrowing objective after a fresh comparison.
Before leaving, ask about the existing loan's current terms and available changes. Compare that response with the alternative proposal on a consistent basis. Do not change lenders simply to complete a switch you have already started researching.
FAQ
What’s the best CommBank home loan alternative in 2026?
Mortgage Pros is the broker-led choice for borrowers seeking home loan advice, particularly doctors. Another bank directly suits borrowers who prefer to compare lender proposals and manage the application themselves.
Is a mortgage broker better than applying directly to CommBank?
A mortgage broker suits you when you want help assessing lender options and preparing an application. Applying directly suits you when you want a particular bank’s loan and are comfortable handling the comparison yourself.
Can a mortgage broker guarantee home loan approval?
No, a mortgage broker cannot guarantee lender approval. The lender assesses the application, supporting documents and proposed security against its credit requirements.
Should doctors compare alternatives to CommBank?
Doctors should compare lender options against their income, borrowing objective and loan requirements. Professional specialisation in an adviser does not replace the need to confirm the selected lender’s eligibility criteria.
Is a non-bank lender easier to get approved with?
Non-bank status does not establish that a loan is easier to obtain. Check the particular lender’s assessment criteria and documentation requirements before applying.
What should I check before refinancing away from CommBank?
Check the proposed loan structure, remaining term, transition requirements and any applicable break costs. Compare the existing loan and alternative using the same borrowing amount and repayment basis.
Should I stay with CommBank if I already bank there?
Stay when the home loan meets your needs and the banking convenience remains valuable to you. An existing banking relationship is a reason to assess the full arrangement, not a reason to skip comparison.
One last thing
A lower repayment can come from extending the loan term rather than improving the loan. Before accepting a refinance proposal, request a comparison using your existing remaining term as well as the proposed term.
Mortgage Pros home loan advice is best for borrowers who want help matching lender options to their circumstances, particularly doctors. Contact us today to discuss your objective, current loan and application requirements before committing to a lender.
Discuss your home loan options today
Get home loan advice for your purchase, refinance, equity or guarantor needs.
Related guides
- Lenders for self-employed home loans
- Comparing offset home loan accounts
- Comparing refinance home loan deals