Best overall for a residential purchase: a specialist residential SMSF lender. Best for reviewing an existing loan: your current SMSF lender, assessed against alternatives. Best for eligible business premises: a commercial SMSF lender. The best SMSF home loan lenders match the fund’s property, borrowing structure and repayment capacity; this guide ranks lender types rather than unsupported individual offers.
- The best smsf home loan lenders assess the fund, property and limited recourse borrowing arrangement together.
- Specialist residential SMSF lenders are the starting point for a fund buying residential investment property.
- Review an existing SMSF lender before refinancing, but compare its proposal with suitable alternatives.
- Commercial SMSF lenders suit eligible business premises, not ordinary residential purchases.
- Mortgage Pros provides mortgage broking support; trustees also need qualified SMSF legal and financial advice.
Why this matters
An SMSF property loan is not a personal home loan with a different borrower name. The fund owns the investment, the borrowing must satisfy superannuation law, and the property must serve the fund’s retirement purpose.
You cannot buy a residential property through your SMSF and use it as your own home. Residential property generally cannot be acquired from, or rented to, fund members or their related parties. Business real property has different rules and requires separate assessment.
Mortgage Pros provides mortgage broking services for borrowers and property owners. For SMSF borrowing, lending advice needs to sit alongside advice on the fund’s investment strategy, legal structure and compliance obligations.
Before comparing lenders in 2026, establish whether borrowing through the fund is appropriate at all. An attractive loan feature does not fix an unsuitable investment or an incorrectly established arrangement.
What makes the best SMSF home loan lenders?
Assess these criteria before choosing a lender or signing a property contract:
- Property eligibility: The lender accepts the property type, use and location. Residential investment property and commercial premises need different assessments.
- Fund repayment capacity: The assessment accounts for rental income, contributions, expenses and existing commitments. Approval alone does not establish that the investment suits the fund.
- Borrowing structure: The proposed arrangement satisfies limited recourse borrowing requirements and the lender’s documentation rules.
- Cash retained: The fund keeps sufficient money for expenses, vacancies, repairs and other obligations after settlement.
- Loan flexibility: Repayment options and any account features work with the fund’s actual cash flows. Confirm how each feature operates within the SMSF structure.
- Exit requirements: Refinancing, selling and releasing security have clear processes. Establish these before committing, not when the fund needs to change lenders.
Compare the whole arrangement, not an isolated loan feature. A lender that accepts the property but requires an unsuitable structure is not the right choice.
SMSF lender options at a glance
This 2026 comparison separates the main borrowing situations. It does not treat a mortgage broker as a lender or present an unverified ranking of individual providers.
| Ranked option | Best for | Main role | Key limitation |
|---|---|---|---|
| Specialist residential SMSF lender | Purchasing residential investment property | Assesses residential property lending within an SMSF borrowing structure | Acceptance still depends on the fund, property and documentation |
| Existing SMSF lender | Reviewing an established SMSF loan | Provides a reference point before changing lenders | Staying does not prove the existing arrangement remains suitable |
| Commercial SMSF lender | Acquiring eligible business premises | Assesses commercial property and associated rental arrangements | Commercial eligibility and related-party rules require separate scrutiny |
Each option fills a different role. Start with the row that matches your transaction, then compare individual lenders within that category.
1. Specialist residential SMSF lender: best for residential purchases
A specialist residential SMSF lender assesses borrowing for residential investment property held through a self-managed super fund. The assessment combines the property, the fund’s financial position and the proposed limited recourse borrowing arrangement, or LRBA.
Best for: Trustees considering a residential investment property purchase through their SMSF. This is the most relevant starting category when the proposed asset is residential rather than commercial.
Specialist residential SMSF lender pros
- The lending assessment addresses the SMSF borrowing structure rather than an ordinary personal mortgage.
- Residential property eligibility forms part of the assessment.
- Documentation requirements help identify what the fund must establish before settlement.
Specialist residential SMSF lender cons
- Specialisation does not mean every residential property or fund qualifies.
- A loan approval does not establish compliance with every superannuation obligation.
- The fund still carries vacancy, repair and repayment obligations after purchase.
Before selecting a lender, ask which income sources it recognises, which documents it requires and how it assesses the proposed property. Get the answers for your fund rather than relying on a general product description.
The lender’s requirements and your adviser’s recommended legal structure must agree. Resolve differences before signing documents that commit the fund to a purchase.
Verdict: Shortlist specialist residential SMSF lenders for a residential purchase; hold any application until the fund and structure are ready.
2. Existing SMSF lender: best for reviewing an established loan
Your current SMSF lender provides the starting point for reviewing an existing borrowing arrangement. Ask it to reassess the loan against the fund’s current circumstances, then compare its response with suitable alternatives.
Best for: Trustees with an established SMSF property loan who want to assess whether to stay or refinance. A review is useful even when the property itself has not changed.
Existing SMSF lender pros
- The existing arrangement provides a clear baseline for comparison.
- A review lets you identify whether the current loan still serves the fund’s needs.
- Staying avoids the work of transferring the loan to another lender.
Existing SMSF lender cons
- The current lender’s proposal is not a substitute for comparing alternatives.
- Existing account features do not necessarily match the fund’s present needs.
- Familiarity with the lender does not resolve changes in cash flow or investment strategy.
For a 2026 refinance review, examine the loan documents, property security, fund accounts and borrowing structure together. Refinancing an LRBA requires attention to the replacement arrangement, not just the repayment terms.
Ask your advisers to identify legal, administrative and transaction requirements before authorising a change. Compare the consequences of staying and moving on the same basis.
Verdict: Review the existing SMSF lender first; hold the decision to stay until alternatives have been assessed.
3. Commercial SMSF lender: best for eligible business premises
A commercial SMSF lender assesses borrowing secured against commercial property. This category suits a fund considering eligible business premises, including arrangements involving related parties where the superannuation rules permit them.
Best for: Trustees assessing commercial property that qualifies for the proposed SMSF transaction. Business real property is a legal classification, not a label established by calling a building commercial.
Commercial SMSF lender pros
- Commercial property and its rental arrangements receive a relevant lending assessment.
- The assessment addresses a different use case from residential investment lending.
- Eligible business premises can be assessed alongside the fund’s retirement investment strategy.
Commercial SMSF lender cons
- Not every commercial property qualifies as business real property.
- A related-party transaction requires careful compliance assessment.
- Combining business premises and retirement savings creates concentration risk for the fund.
Where a member’s business will occupy the property, confirm that the arrangement is permitted and conducted on arm’s-length terms. Document the lease and payment obligations rather than treating them as informal transfers between connected parties.
Also assess what happens if the business stops paying rent or changes premises. The fund’s loan obligations remain separate from the business’s operational needs.
Verdict: Shortlist commercial SMSF lenders for eligible business premises; skip this route for an ordinary residential purchase.
How these options are ranked
The ranking follows transaction suitability: residential purchase first, existing-loan review second and commercial premises third. It is a decision path, not a claim that one lender category outperforms another in every situation.
Property eligibility, repayment capacity, compliant documentation, retained cash and exit requirements determine the shortlist. Mortgage Pros is a mortgage broker, not an SMSF lender, so it belongs in the advice process rather than a lender ranking.
Understand the borrowing structure before applying
An LRBA generally involves borrowing to acquire a single acquirable asset, with the asset held in a separate holding trust. The arrangement limits the lender’s recourse to the asset held under that structure, subject to the legal requirements and documents.
The Superannuation Industry (Supervision) Act 1993, particularly sections 67A and 67B, sets out the relevant borrowing exceptions and replacement-asset rules. The historical date is the Act’s name; assess the current law and guidance for a transaction in 2026.
Keep these distinctions clear:
- Ownership: The purchase documents and holding arrangement must identify the correct parties.
- Property use: Residential occupation by members is not an acceptable purpose for an SMSF investment property.
- Borrowed money: LRBA borrowing can fund permitted repairs and maintenance, but not improvements to the acquired asset.
- Fund money: Using other fund money for improvements requires advice about whether the work changes the asset’s identity.
- Trustee duties: Lender approval does not replace the trustees’ compliance obligations.
The Australian Taxation Office’s SMSF property and limited recourse borrowing guidance explains these distinctions. Read that guidance alongside professional advice specific to the fund; a general lending comparison cannot establish whether a proposed contract complies.
Prepare your SMSF lender shortlist
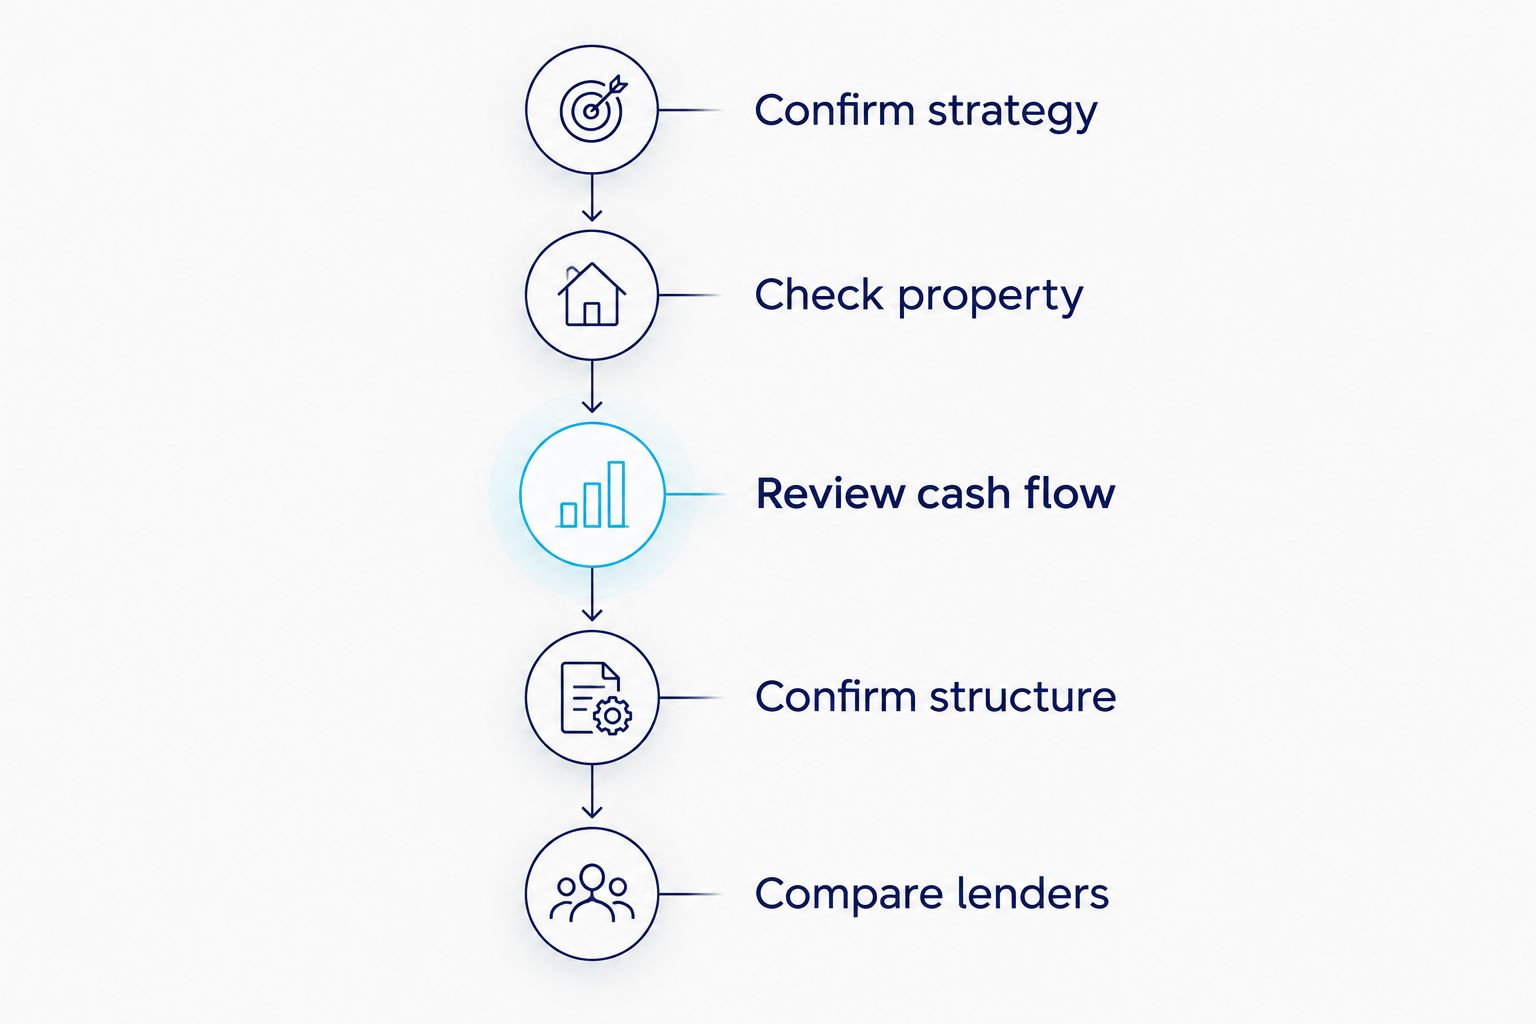
Follow this sequence before submitting applications. It keeps the lending decision tied to the fund’s purpose instead of treating approval as the only goal.
Confirm strategy
Review whether the property and borrowing fit the fund’s investment strategy. Assess diversification, liquidity and the needs of members receiving benefits, not just the expected rental income.
Check property
Confirm the property’s eligibility with both the lender and your qualified advisers. For residential property, establish that the proposed seller and occupants do not create prohibited related-party arrangements.
Review cash flow
List rent, contributions, repayments, property expenses and fund expenses. Test a vacancy or repair scenario without assuming the fund can rely on uninterrupted rent or additional contributions.
Confirm structure
Have the legal and borrowing documents checked before committing to the transaction. Coordinate the fund, holding trust, contract and proposed lender requirements.
Compare lenders
Compare lenders that accept the same property and structure. Record differences in documentation, repayment features and exit requirements so the final decision rests on comparable information.
A complete shortlist should explain why each lender fits the transaction. Remove any option that fails a fundamental requirement, even if another feature looks attractive.
Which SMSF lender should you choose?
For a residential purchase, start with specialist residential SMSF lenders that accept your fund, property and borrowing structure. For an existing loan, review the current lender against alternatives. For eligible business premises, use a commercial SMSF lending assessment.
Mortgage Pros is best suited to borrowers seeking mortgage broking support rather than a substitute for SMSF legal or financial advice. Keep those roles separate and coordinate the advice before committing the fund.
Ask for written confirmation of the proposed lender’s requirements. Your 2026 shortlist should reflect the actual transaction, not assumptions carried over from a personal home loan.
Discuss your borrowing requirements
Ask about mortgage broking support and the lending requirements for your proposed transaction.
FAQ
What are the best SMSF home loan lenders in 2026?
The best SMSF home loan lenders are those that accept your fund, property and compliant borrowing structure. Start with specialist residential SMSF lenders for residential purchases, review your existing lender for an established loan, and assess commercial SMSF lenders for eligible business premises.
Can I live in a house bought through my SMSF?
No, you cannot use residential property owned by your SMSF as your own home. Residential property generally cannot be rented to fund members or their related parties.
Is an SMSF property loan the same as an investment home loan?
No, an SMSF property loan has different ownership, borrowing and compliance requirements from a personal investment home loan. An LRBA requires a specific holding arrangement and must satisfy superannuation law.
Can I refinance an existing SMSF property loan?
An SMSF property loan can be refinanced where the replacement borrowing arrangement meets the applicable legal and lender requirements. Review the fund documents, holding structure, security and transaction requirements before proceeding.
Can my SMSF buy premises for my business?
An SMSF can acquire and lease eligible business real property under permitted arrangements. Confirm the property’s legal classification, related-party rules and arm’s-length terms with qualified advisers before committing.
Can borrowed SMSF money pay for renovations?
Money borrowed under an LRBA cannot fund improvements to the acquired asset, although permitted repairs and maintenance are treated differently. Using other fund money also requires assessment of whether the work changes the asset’s identity.
Does lender approval mean my SMSF investment is compliant?
No, lender approval does not establish that an SMSF investment satisfies every superannuation obligation. Trustees remain responsible for compliance and need advice on the investment strategy, transaction and legal structure.
Is Mortgage Pros an SMSF lender?
Mortgage Pros is a mortgage broking firm, not a lender. Mortgage broking support does not replace qualified advice about SMSF establishment, legal documents, investment suitability or tax obligations.
One last thing
Loan approval and investment suitability are different decisions. A lender assesses its lending requirements; trustees must also assess whether the property and debt serve the fund’s retirement purpose.
Before choosing an SMSF lender in 2026, write down how the fund will meet repayments during a vacancy and pay for an unexpected repair. If the answer depends entirely on uninterrupted rent, revisit the investment before proceeding.
Related guides
- Investment property loan lenders
- Refinance home loan comparisons
- Home equity loan options
- Lenders for self-employed home loans