Canstar helps you compare Australian home loans through product information and ratings. Its comparison results do not replace a lender’s assessment of your income, deposit, debts and proposed property. The best Canstar alternative in 2026 is Mortgage Pros if you need mortgage-broking advice and approval support; Finder if you want another comparison website for your own research.
- Canstar alternatives home loans: choose Mortgage Pros for mortgage-broking advice and application support, rather than another product ranking.
- Finder and RateCity suit independent home loan research; a comparison result is not an approval decision.
- Compare loan structure, eligibility and total costs before choosing a lender.
- Keep Canstar if you need an initial shortlist, then confirm the details with a broker or lender.
Why this matters
A home loan can look suitable in a comparison table and still fail to meet your needs. An offset account, repayment arrangement or eligibility condition can change which option deserves your attention.
Choose the comparison method that answers your actual question. A website helps you research products. A mortgage broker helps you connect loan choices to your circumstances, while the lender makes the credit decision.
For your 2026 search, separate product research from application preparation. You need both, but they solve different problems: finding a suitable loan structure and demonstrating that you meet the lender’s requirements.
Canstar alternatives at a glance
| Option | Best for | Standout approach | How it differs from Canstar | Main limitation |
|---|---|---|---|---|
| Canstar | Initial home loan research | Product comparisons and ratings | The benchmark comparison website | A rating does not establish personal eligibility |
| Mortgage Pros | Borrowers seeking mortgage-broking advice | Home loan advice and approval support | Adds assistance with the borrower’s circumstances and application | The lender still decides whether to approve the loan |
| Finder | Independent comparison research | Home loan comparisons and educational content | Provides another website for building and checking a shortlist | Published product information still needs lender confirmation |
| RateCity | Checking another home loan comparison source | Home loan comparisons and financial information | Offers another research route alongside Canstar | Comparison results are not a personalised credit assessment |
| A lender directly | Assessing a specific lender’s products | Direct discussion about that lender’s requirements | Moves from broad research to a lender-specific enquiry | Does not compare competing lenders for you |
These options are not interchangeable. Comparing websites answers a research question; speaking with a broker or lender moves you towards an application decision.
1. Mortgage Pros: best for advice and approval support
Mortgage Pros is a Sydney-based mortgage broking firm serving borrowers and investors across Australia. Its home loan services include refinancing, equity and guarantor arrangements, with a specialisation in home loans for doctors.
This is the relevant alternative when you need help interpreting your circumstances, not simply another list of loans. Bring your objective, income documents, existing debts and deposit information so the discussion starts with your borrowing position.
Where the mortgage-broking approach shines
- Application support: Connect your loan research with the information required for an application.
- Loan-purpose advice: Discuss whether you are buying, refinancing, investing or accessing equity.
- Specialist relevance: Doctors can seek advice from a firm that identifies doctor home loans as a specialisation.
- Guarantor discussions: Explore the role of a guarantor rather than treating the arrangement as an ordinary deposit substitute.
Where the mortgage-broking approach falls short
- A broker cannot replace the lender’s credit assessment or guarantee approval.
- Advice depends on accurate information about your income, liabilities and financial position.
- You still need to understand the proposed loan and read the lender’s documents before accepting it.
- You should ask which lenders are considered rather than assume a broker compares every Australian lender.
Best for: Borrowers who want home loan advice and help preparing an application, especially when a product ranking leaves eligibility questions unanswered.
Mortgage Pros versus Canstar
| Dimension | Mortgage Pros | Canstar |
|---|---|---|
| Main purpose | Mortgage-broking advice and approval support | Product research and comparison |
| Starting point | Your borrowing objective and circumstances | Published loan information and comparison criteria |
| Doctor home loans | An identified specialisation | Research still requires checking individual lender eligibility |
| Final approval | Decided by the lender | Decided by the lender |
Before choosing a broker-led route, ask what information is needed, which lenders will be considered and how the recommendation will be explained. Those questions help you assess the service without confusing assistance with an approval promise.
Verdict: Hold off on choosing a loan until your borrowing circumstances and application requirements have been assessed.
2. Finder: best for independent comparison research
Finder is an alternative for borrowers who want to research home loans themselves. Its home loan comparisons and educational content give you another place to examine product features and borrowing concepts.
Use Finder to build questions, not to bypass them. Check whether the product you are viewing matches your purpose, repayment type and intended use of the property before comparing it with another loan.
Where Finder shines
- Provides another home loan research source alongside Canstar.
- Combines comparison information with explanations of borrowing topics.
- Suits borrowers who want to control their own initial shortlist.
Where Finder falls short
- A comparison result does not confirm that a lender will accept your application.
- Published information requires checking against the lender’s current documents.
- You remain responsible for deciding whether the features fit your intended use.
Best for: Borrowers who want another comparison website and are comfortable conducting their own research.
| Dimension | Finder | Canstar |
|---|---|---|
| Research role | Home loan comparison website | Home loan comparison website |
| Supporting material | Educational borrowing content | Product information and ratings |
| Personal eligibility | Requires lender assessment | Requires lender assessment |
For a useful 2026 comparison, keep your search settings consistent across both websites. Comparing an investment loan on one site with an owner-occupier loan on another creates a misleading shortlist before you even reach the application stage.
Verdict: Hold the shortlist until you have checked product details and eligibility with the lender or a broker.
3. RateCity: best for checking another comparison source
RateCity offers another route for researching Australian home loans. Use it alongside Canstar when you want to check product information through a separate comparison source.
The value is in checking the same borrowing scenario, not collecting the longest list. Write down why an option belongs on your shortlist and which questions remain unresolved.
Where RateCity shines
- Offers home loan comparisons and financial information.
- Gives you another source for researching loan features.
- Supports an independent shortlist before a lender or broker discussion.
Where RateCity falls short
- Research results do not establish your borrowing capacity.
- A displayed product still needs checking against lender documentation.
- Comparing websites does not resolve questions about income assessment or security requirements.
Best for: Borrowers who want to cross-check their home loan research before seeking an assessment.
| Dimension | RateCity | Canstar |
|---|---|---|
| Primary use | Home loan research and comparison | Home loan research and comparison |
| Information format | Comparison information and financial content | Comparison information and ratings |
| Approval authority | The lender | The lender |
Keep a record of the product name, repayment type and features you checked. That makes a later conversation more useful than arriving with an unexplained ranking or a screenshot alone.
Verdict: Hold your decision until the shortlisted loan’s conditions match your circumstances.
4. A lender directly: best for a specific product enquiry
Speaking directly with a lender suits borrowers who already have a particular institution or product in mind. You can ask about that lender’s documentation, eligibility criteria and application process.
This route narrows the conversation. It does not tell you whether another lender offers a structure that better matches your needs.
Where a direct lender enquiry shines
- Lets you ask questions about a specific lender’s products.
- Connects your enquiry with that lender’s application requirements.
- Helps clarify what information the lender needs to assess you.
Where a direct lender enquiry falls short
- The conversation centres on that lender’s products, not competing lenders.
- You need to conduct any wider comparison yourself.
- An initial discussion is not a substitute for formal approval.
Best for: Borrowers with a clear lender preference who want to confirm product conditions before applying.
| Dimension | A lender directly | Canstar |
|---|---|---|
| Comparison scope | That lender’s products | Published comparison results |
| Application questions | That lender’s requirements | Requires a separate lender enquiry |
| Competing options | You research them separately | Supports initial product research |
Verdict: Wait for a formal assessment before treating a lender discussion as approval.
Why people switch from Canstar
The practical reason to move beyond Canstar is a change in the question you need answered. Once you move from researching products to preparing an application, comparison information alone is not enough.
These are decision points, not claims about Canstar customer behaviour:
- You need eligibility guidance. Your income, debts, deposit and property need assessment, not just a product comparison.
- You are refinancing. You need to consider the existing loan, replacement structure and switching costs together.
- You are accessing equity. Property value alone does not establish how much a lender will let you borrow.
- You are considering a guarantor. The guarantor’s obligations and the lender’s release requirements need careful explanation.
- You have unanswered feature questions. Offset access, redraw conditions and repayment rules need checking in the actual loan documents.
None of these reasons requires abandoning Canstar. Use comparison information as preparation, then choose the next step according to the problem you need solved.
How to compare home loans before applying
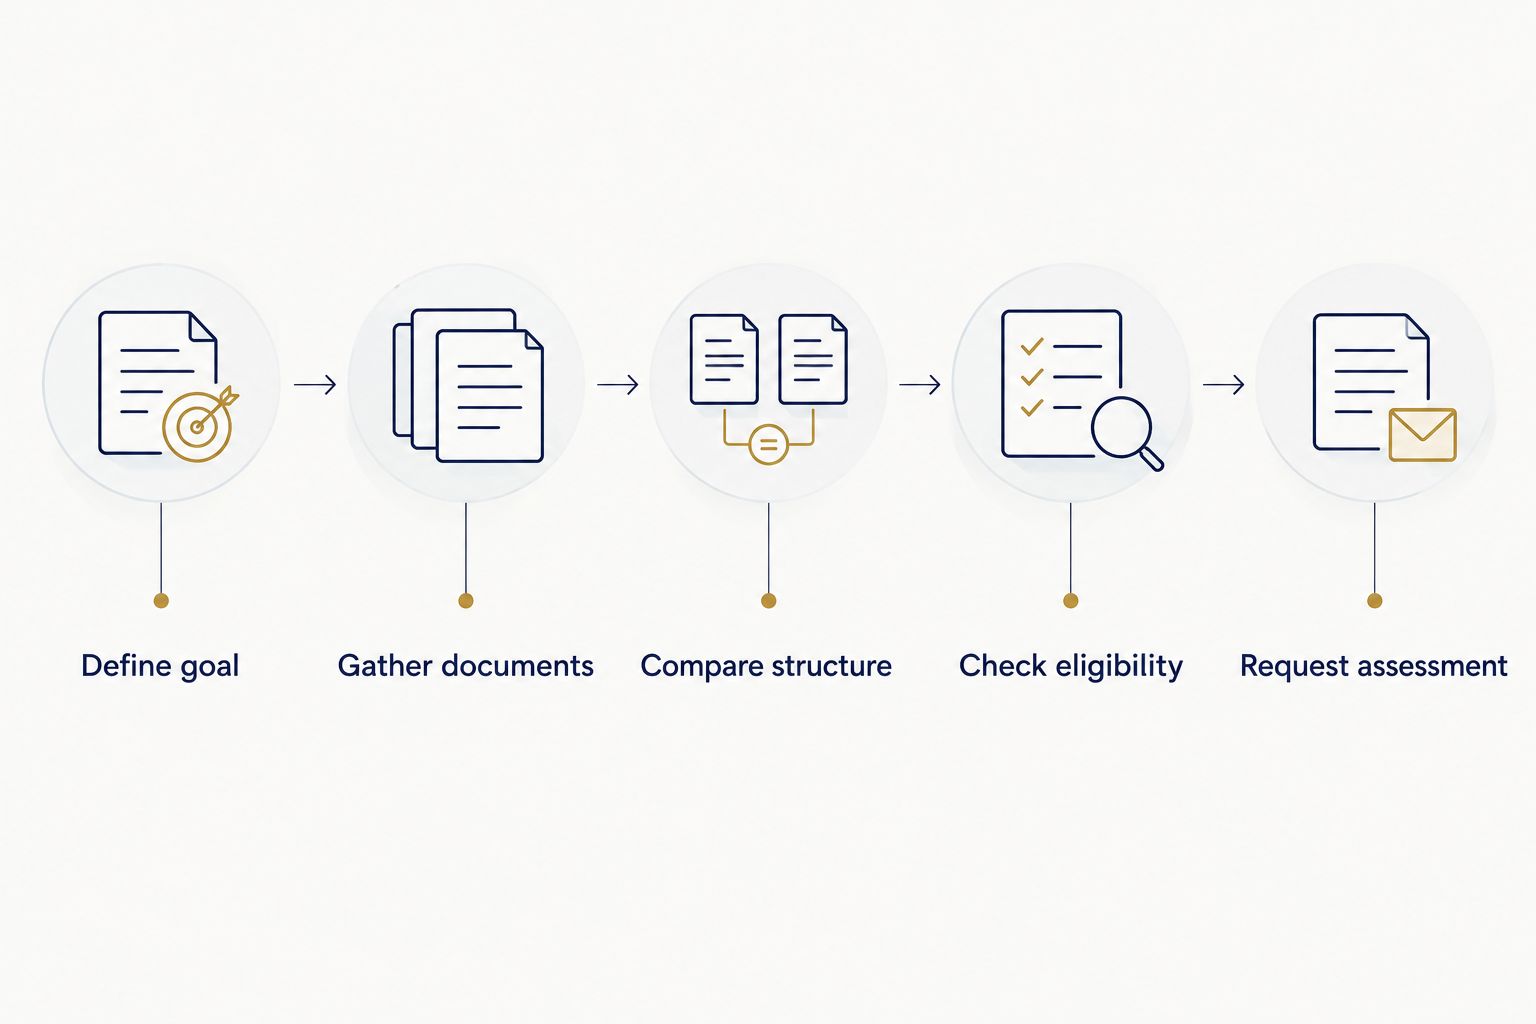
Use this sequence for a 2026 home loan decision. It keeps product research tied to the information a lender needs and the features you will actually use.
Define goal
State whether you are buying a home, purchasing an investment property, refinancing or accessing equity. Include your intended repayment approach and any need for a guarantor.
Gather documents
Prepare evidence of income, existing loan statements, debts and deposit funds. Ask the lender or broker which documents apply to your circumstances; different income arrangements require different evidence.
Compare structure
Compare like with like: loan purpose, repayment type, fixed or variable arrangements, and relevant features. An offset account and redraw are different arrangements, so check access conditions rather than treating them as equivalent.
Australian home loan comparison rates commonly use a standard $150,000 loan over 25 years. That reference helps compare interest and certain fees, but it does not reproduce the costs of every borrower’s loan.
Check eligibility
Ask how the lender assesses income, debts and the property offered as security. Loan-to-value ratio, or LVR, expresses the loan amount as a percentage of the property value used by the lender.
For borrowing above 80% LVR, ask specifically whether lenders mortgage insurance applies and whether an exception is relevant. Do not treat an occupation, deposit position or product listing as an automatic exemption.
Request assessment
Take the shortlist and unresolved questions to a broker or lender. Ask for an explanation of the proposed structure, the application requirements and the conditions that still need to be satisfied.
A shortlist is useful only when you can explain why each loan fits. Keep the lender’s product information with your notes and resolve unanswered questions before committing to an application.
Discuss your home loan today
Get home loan advice for buying, refinancing, equity or a guarantor arrangement.
When staying with Canstar is the right call
Stay with Canstar when your immediate task is learning about home loans or building an initial shortlist. There is no need to change websites simply because another comparison source exists.
In 2026, the useful distinction remains research versus assessment. Keep Canstar for the research stage if it answers your questions, then confirm the shortlisted product’s conditions with the lender or seek mortgage-broking advice.
Do not replace a useful research source with another website when your unanswered question requires an assessment.
FAQ
What’s the best Canstar alternative for home loans in 2026?
Mortgage Pros is the best fit for borrowers seeking mortgage-broking advice and approval support rather than another comparison website. Finder and RateCity are alternatives for independent product research.
Is Finder better than Canstar for comparing home loans?
Neither website is universally better for every borrower. Compare the same loan purpose, repayment type and features, then confirm the shortlisted product’s conditions with the lender.
Can a comparison website tell me whether my home loan will be approved?
A comparison result does not establish approval. The lender assesses your circumstances, supporting documents and proposed property before making its credit decision.
Should I use a mortgage broker instead of Canstar?
Use a mortgage broker when you need help connecting loan choices to your circumstances and preparing an application. Canstar can still support your initial research; the two approaches serve different purposes.
Are home loan comparison rates the same as my actual borrowing costs?
A comparison rate is not a personalised calculation of your borrowing costs. Australian home loan comparisons commonly use a standard $150,000 loan over 25 years, so check costs for your actual loan amount, term and features.
Can I apply directly with a lender after comparing loans?
Yes, you can approach a lender directly after researching its products. Confirm eligibility, documentation and product conditions before treating the shortlist as a suitable application choice.
What should I check before refinancing in 2026?
Check the replacement loan’s structure, eligibility requirements and switching costs against your existing loan. Include the features you use and any conditions attached to leaving the current loan.
One last thing
Before submitting an application, ask: What could prevent this particular loan from meeting my needs or receiving approval? That question shifts the discussion from a ranking to the conditions that matter.
Contact us today to discuss your borrowing goal, the information needed for an assessment and your next application step.
Related guides
- Best home loan lenders for doctors
- Best lenders for self-employed home loans
- Best offset home loan accounts
- Best guarantor home loan lenders