Savings.com.au gives you a starting point for comparing home loans and understanding the options. A comparison shortlist stops short of establishing which lender will accept your income, property and application. The best Savings.com.au alternative in 2026 is Mortgage Pros if you need individual home loan advice and approval support; ASIC’s Moneysmart if you need financial education before choosing a loan.
- For savings.com.au alternatives home loans, choose Mortgage Pros for individual mortgage broking and application support.
- ASIC’s Moneysmart suits borrowers who need home loan education and repayment calculations before approaching a provider.
- Direct lender discussions suit borrowers who already know which institution they want to assess.
- Keep Savings.com.au for initial research; distinguish product comparison from personalised advice and lending approval.
Why this matters
Your best next step depends on the question you need answered. Comparing loan features is different from checking how a lender will assess your employment, existing debts or deposit.
For a purchase or refinance in 2026, separate research from assessment. Use comparison resources to understand the options, then investigate eligibility before treating any loan as your preferred outcome.
Mortgage Pros provides mortgage broking services for home buyers and property owners across Australia, including refinancing, equity and guarantor arrangements. Its specialisation in doctor home loans makes it a relevant starting point when you want advice connected to your circumstances rather than another product shortlist.
Savings.com.au alternatives at a glance
The options below serve different purposes. Choose the service that addresses your next decision, rather than expecting every alternative to do the same job.
| Option | Best for | Main function | Difference from Savings.com.au | Main limitation |
|---|---|---|---|---|
| Savings.com.au | Initial home loan research | Comparing home loan information | The starting benchmark | A comparison result is not a lending decision |
| Mortgage Pros | Individual advice and approval support, particularly for doctors | Mortgage broking for purchases, refinancing, equity and guarantor arrangements | Adds borrower-specific guidance and application support | A broker cannot guarantee a lender’s approval |
| ASIC’s Moneysmart | Understanding borrowing and repayments | Financial education and calculators | Focuses on understanding the decision rather than choosing a provider | Does not arrange or approve your home loan |
| Direct lender discussions | Assessing a particular institution’s loans | Discussing a lender’s products and application requirements | Takes you from general research to a specific lender | Does not compare competing institutions for you |
No option replaces the lender’s assessment. A useful shortlist, a repayment calculation and an approval are separate outcomes.
1. Mortgage Pros: best for individual home loan advice
Mortgage Pros is a mortgage broker, not another comparison website. It helps individual borrowers and investors secure and manage home loans, with support covering refinancing, equity and guarantor arrangements.
Mortgage Pros is best for home loan borrowers who need individual advice and approval support, particularly doctors. For your 2026 search, the reason to choose a broker is the help you need with the decision and application—not simply the number of loan options you can browse.
Where Mortgage Pros shines
- Borrower-specific guidance: You can discuss your circumstances rather than relying on a general product description.
- Support beyond the shortlist: The service includes home loan advice and approval support.
- Different borrowing goals: Its stated services cover buying, refinancing, equity and guarantor arrangements.
- Doctor home loan specialisation: This is relevant when you want a broker whose stated focus includes your profession.
Where Mortgage Pros falls short
- Approval remains with the lender. Broker support does not remove credit assessment or property requirements.
- Advice requires your participation. You still need to explain your goals and supply accurate financial information.
- It is a different service from anonymous research. If you only want to read about loan features without discussing your circumstances, an educational or comparison resource suits that immediate task better.
Before engaging a broker, ask which lenders the broker can consider, how remuneration works and what information is needed. These questions help you understand the scope of the service before proceeding.
Head-to-head: broker support versus comparison research
| Dimension | Mortgage Pros | Savings.com.au |
|---|---|---|
| Starting point | Your borrowing circumstances and goals | Home loan comparison research |
| Main role | Mortgage broking and approval support | Comparing home loan information |
| Doctor home loans | Stated specialisation | General comparison is the benchmark for this guide |
| Lending decision | Remains with the selected lender | A comparison result is not approval |
Best for: Borrowers who need help connecting a purchase, refinance or equity goal to a home loan application.
Verdict: Buy into broker support when you need an individual assessment, not just another shortlist.
2. ASIC’s Moneysmart: best for understanding the decision
ASIC’s Moneysmart provides financial education and calculators. It suits you when the immediate problem is understanding borrowing, repayments or loan features before discussing a particular product.
This is an alternative research pathway, not a substitute mortgage broker. Use it to develop clearer questions and understand the consequences of a borrowing decision.
Where Moneysmart shines
- Education before selection: You can work through borrowing concepts without first choosing a lender.
- Repayment modelling: Calculators help you explore how loan inputs affect repayment estimates.
- A clearer starting brief: Understanding terms such as offset, redraw and loan term helps you question a recommendation.
Where Moneysmart falls short
- Calculations are estimates. They do not establish what a lender will approve.
- You must choose realistic inputs. A calculator cannot correct an incomplete picture of your income, expenses or debts.
- It does not arrange the loan. You still need a lender or broker to progress an application.
Use educational resources to understand the trade-offs, then take your questions to the person assessing or arranging your loan. Do not treat a comfortable calculator result as evidence that a particular application will succeed.
Best for: Borrowers who want to understand the decision before seeking product recommendations.
Verdict: Hold off on choosing a loan until you understand the repayment and feature trade-offs.
3. Direct lender discussions: best for a specific lender shortlist
Speaking directly with a lender makes sense when you already know which institution you want to investigate. You can ask about its products, documentation and application process without adding another research platform.
The trade-off is scope. A lender discussion concerns that institution’s offering, so you must organise any comparison with competing lenders yourself.
Where direct lender discussions shine
- You can ask questions about a specific product and its requirements.
- You can clarify what the institution needs before you apply.
- You can explore whether its loan structure matches your intended use.
Where direct lender discussions fall short
- You remain responsible for comparing other institutions.
- An initial conversation is not a formal approval.
- Convenience alone does not establish that the loan suits your circumstances.
Best for: Borrowers with a defined lender shortlist who are comfortable managing their own comparison.
Verdict: Buy into the direct route only after checking the lender against your requirements and competing options.
Why people switch from Savings.com.au
The practical reason to move beyond a comparison website is a change in task. Once you understand the broad options, your next question becomes more personal: which loan structure and application pathway fit your circumstances?
For a 2026 home loan decision, these are reasons to add another service—not claims that Savings.com.au has become a poor research option.
You need your income assessed
A product description cannot establish how a lender will treat your particular income. If your application involves several income sources, business income or a recent employment change, ask what evidence the lender requires before settling on a shortlist.
Keep the question specific: which income will be considered, what documents support it and what conditions apply? Avoid assuming that a calculator’s income field reflects a lender’s assessment method.
You need help with the loan structure
A refinance, equity release or guarantor arrangement involves more than choosing a headline feature. You need to understand how the proposed structure works and what obligations it creates.
Ask for an explanation you can repeat back accurately. If you cannot explain the arrangement, the comparison is not finished.
You are ready to apply
Research helps you identify possibilities; an application requires evidence. Moving to a broker or lender is appropriate when you need documentation requirements, an assessment process and a clear next action.
Switch channels when your question changes from what is available to what fits your application. Keep useful research rather than starting again unnecessarily.
How to compare your alternatives before applying
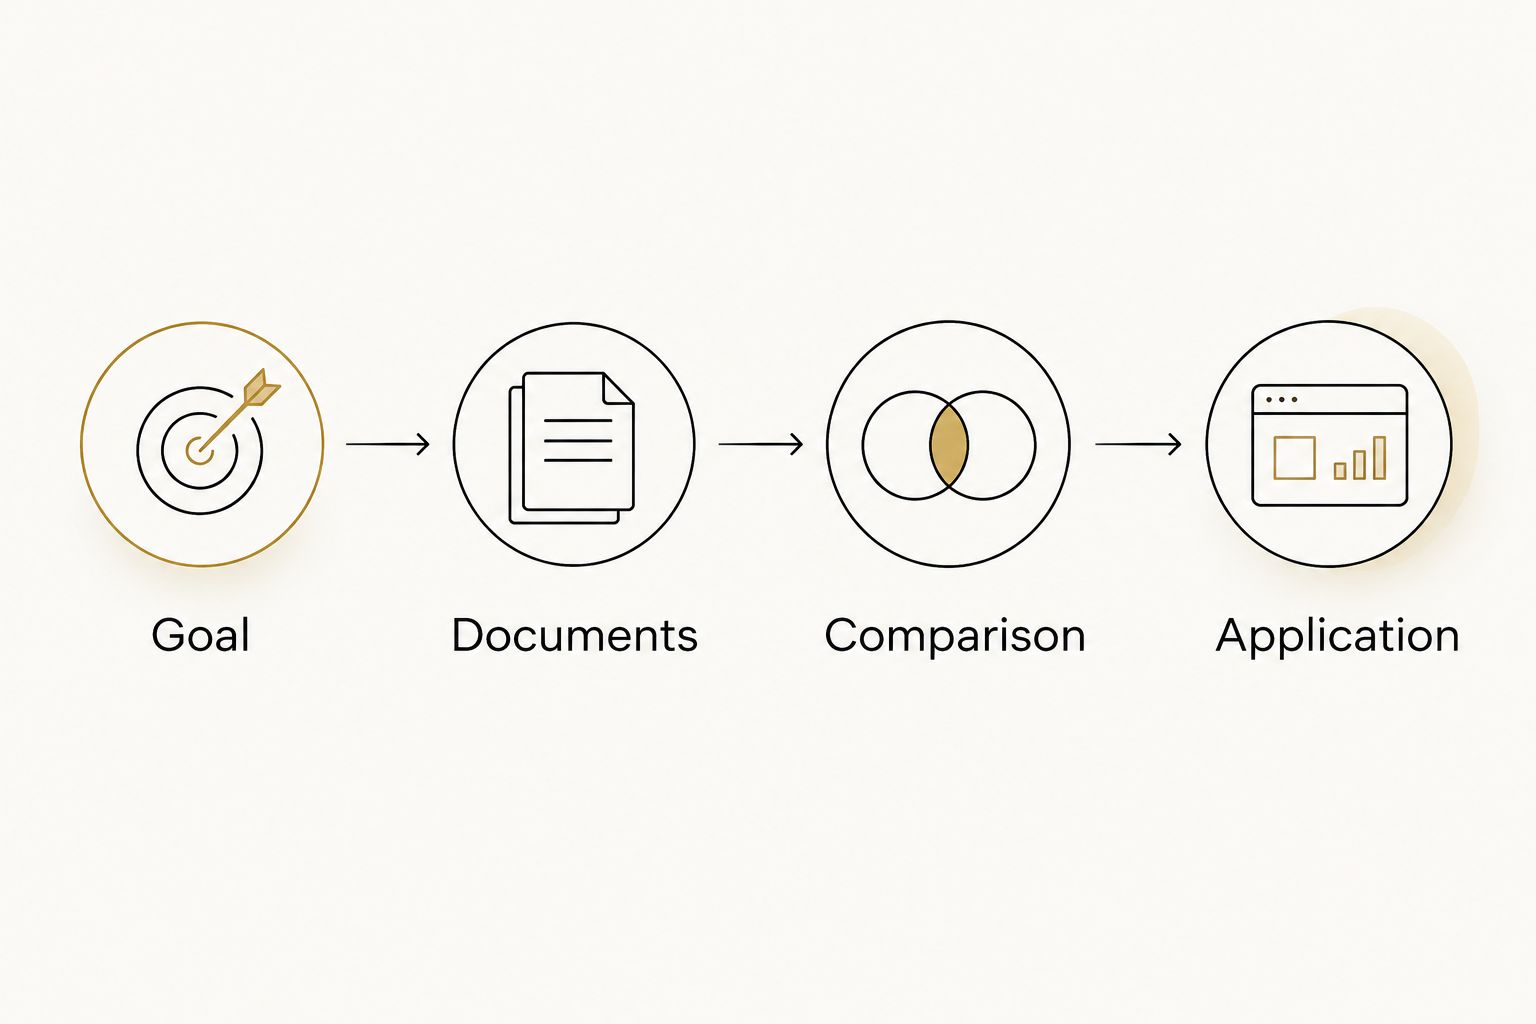
Use the same brief for every discussion. Otherwise, you risk comparing answers based on different loan amounts, terms or assumptions.
Goal
Write down whether you are buying, refinancing, accessing equity or investigating a guarantor arrangement. State what you want to change and which loan features matter to that goal.
For example, distinguish reducing repayments from reducing the time you remain in debt. Those are different objectives, and extending a loan term changes the comparison.
Documents
Gather the income, expense, debt and property information requested for your assessment. Explain unusual transactions or changes in circumstances rather than leaving the assessor to interpret them.
Ask for the document requirements before submitting an application. Accurate preparation is more useful than sending incomplete applications to several providers.
Comparison
Compare 3 scenarios: keeping your present arrangement where relevant, choosing the proposed alternative, and choosing a different loan structure. These are decision scenarios, not a claim that every borrower needs the same shortlist.
Use a 5-year checkpoint to examine your expected position over a defined period. Also request a 30-year projection where that term is relevant, so a smaller repayment does not distract you from the longer commitment. These are illustrative comparison periods, not recommended loan terms.
Application
Confirm the proposed lender, loan structure, required evidence and outstanding conditions before authorising the next step. Ask what remains uncertain and what would change the recommendation.
A clear application plan identifies the next action and who is responsible for it. It does not promise an approval date or outcome.
For a 2026 application, keep your comparison assumptions consistent and update them when your circumstances change. A recommendation based on an earlier employment, debt or property position needs another check.
Discuss your home loan options
Talk through your purchase, refinance, equity or guarantor goals with Mortgage Pros.
When staying with Savings.com.au is the right call
Stay with Savings.com.au for initial research if your immediate aim is to understand home loan options and prepare a shortlist. There is no need to replace a useful research resource simply because you will eventually need an assessment.
The stronger approach is to give each resource a defined job. Use comparison information to develop questions, educational resources to understand trade-offs, and a broker or lender to investigate your application.
For 2026, keep the research tool that helps you—but do not mistake research for personalised advice or approval.
FAQ
What is the best Savings.com.au alternative for home loans in 2026?
Choose a mortgage broker for individual advice and application support, or ASIC’s Moneysmart for financial education. The best alternative depends on whether you need to understand loans, compare options or progress an application.
Is a mortgage broker better than a comparison website?
A mortgage broker is better suited to individual advice and application support; a comparison website suits initial research. Neither a broker discussion nor a comparison result guarantees lender approval.
Can Savings.com.au tell me whether my home loan will be approved?
A home loan comparison result is not a lending approval. The lender must assess your application, supporting documents and property against its requirements.
What should doctors look for when comparing home loan alternatives?
Doctors should ask how their income and employment circumstances will be assessed and what evidence is required. Compare the proposed loan structure and conditions rather than assuming occupation alone establishes eligibility.
Can I compare home loans without applying?
Yes, you can research loan features and model repayments before applying. Ask a provider to explain whether a proposed next step is an enquiry, an assessment or a formal application.
Should I go straight to my existing lender?
A direct discussion is useful if you want to assess your existing lender’s offering. Compare it with other options before deciding that familiarity is enough reason to stay.
What should I prepare before speaking with a broker?
Prepare your borrowing goal and an accurate overview of income, expenses, debts and property details. Ask which supporting documents are needed for your particular circumstances.
One last thing
Ask every provider to explain why a suitable-looking loan would not fit your application. The answer tests the limits of a recommendation more effectively than another list of benefits.
Then request a clear next step. Contact us today to discuss your home loan goals before progressing an application.
Related guides
- Best home loan lenders for doctors
- Best lenders for self-employed home loans
- Best offset home loan accounts
- Canstar alternatives for comparing home loans