Choose Mortgage Pros for home loan advice and approval support, particularly if you are a doctor; choose NAB if you have decided on NAB and want to deal directly with your lender. This 2026 comparison separates the mortgage broker’s advisory role from the bank’s lending role, so you can choose the right starting point.
- Mortgage Pros vs NAB is a home loan broker-versus-bank decision, not a comparison between two lenders.
- Choose the broker route for advice and application support, particularly when assessing a doctor home loan.
- Choose NAB for a direct application when NAB is already your preferred lender.
- Compare written loan terms, fees and repayment structures before choosing either route.
Why this matters
A mortgage broker helps you arrange finance; a bank decides whether to lend its money. Comparing these roles as though they were interchangeable obscures the decision you actually need to make: do you need help choosing and arranging a loan, or are you ready to approach a particular lender?
Mortgage Pros provides mortgage broking services for home buyers and property owners, including refinancing, equity and guarantor arrangements. Its home loan specialisation includes doctors. NAB is a bank that provides home loans directly to borrowers.
For your 2026 application, separate the service decision from the loan decision. Choosing a helpful adviser does not establish which loan suits you, and choosing a familiar bank does not establish that its proposed loan matches your objectives. Ask for the reasoning behind the recommendation and the written terms before committing.
At a glance
| Dimension | Mortgage Pros | NAB |
|---|---|---|
| Best for | Borrowers seeking home loan advice and approval support | Borrowers who have selected NAB and want direct bank dealings |
| Standout feature | Mortgage broking advice, including a focus on doctors | Direct access to the proposed lender |
| Medical borrower focus | Stated specialisation in home loans for doctors | Assess the proposed loan against your employment and income circumstances |
| Application route | Broker assistance with arranging finance | Application directly to the bank |
| Approval requirements | The lender still assesses the application | NAB assesses its own application |
| Pricing model | Establish broker remuneration and the proposed loan’s costs separately | Assess the bank’s proposed loan costs and terms |
| Ongoing loan management | Advice about refinancing, equity and guarantor arrangements | Direct dealings about a NAB loan |
Choose advice when the lender decision is still open
The broker route fits a borrower who needs help deciding how to proceed; the direct route fits someone who has already selected NAB. That distinction matters more than whether you recognise either name.
You need advice when your questions concern the structure of the borrowing: buying versus refinancing, accessing equity, or using a guarantor. Start by explaining the outcome you want, rather than asking only how much you can borrow. A larger loan is not automatically a better match for your budget.
NAB is the better starting point when your immediate task is obtaining and evaluating a NAB proposal. The advantage is direct communication with the organisation considering the loan. The limitation is scope: a direct NAB conversation concerns NAB lending, not a comparison of other lenders.
Neither route replaces your responsibility to understand the proposed commitment. Ask how the recommendation serves your plans and what would make it unsuitable.
NAB wins on direct access to the lender
NAB’s clearest advantage is its role in the transaction: the bank you approach is also the proposed lender. If your objective is to discuss a NAB application directly, there is no separate broker relationship to manage.
That is useful when you have already researched your options and want the bank to explain its own requirements. You can keep the discussion focused on the proposed product, supporting documents and conditions attached to the application.
The broker’s standout benefit is different: advice and assistance with arranging finance. A broker is not the lender, and broker involvement does not transfer the lending decision away from the bank.
For a 2026 comparison, ask a broker which lenders and loan types are being considered. Do not assume any broker assesses every Australian lender, or that a particular bank is accessible through that broker. Establish the scope before relying on a recommendation.
Mortgage Pros is the clearer match for doctor-focused advice
Mortgage Pros provides mortgage broking services with a stated specialisation in home loans for doctors. That makes it a relevant starting point for a doctor seeking advice about how employment, income and borrowing objectives fit together.
Bring the details that explain your position: your employment arrangement, income documents, existing debts, deposit and intended property use. Ask how each detail affects the recommended application. A professional title alone does not explain your full financial circumstances.
The benefit is the stated advisory focus. The limitation is equally important: specialisation is not a promise of approval, a particular borrowing limit or a concession.
NAB remains a valid direct option for a medical borrower who wants its lending proposal. Ask the bank to explain how it will assess your circumstances rather than assuming either favourable or unfavourable treatment. For further reading, review the guide to home loan lenders for doctors.
The broker route wins when you want application assistance
The broker route is the stronger fit when you want help arranging the application rather than managing the bank discussion yourself. The service described here includes home loan advice and approval support, which addresses a different need from simply selecting a lender.
Before engaging, establish what that assistance covers. Ask who will explain document requests, communicate outstanding conditions and keep you informed about the application. Confirm responsibilities instead of assuming every administrative task is included.
A direct NAB application suits a borrower who prefers to handle that relationship with the bank. Its advantage is a direct communication path; its trade-off is that you are seeking the bank’s own loan rather than appointing a separate mortgage broker.
For either route, prepare a consistent account of your income, debts and objectives. Incomplete or contradictory information creates questions that someone must resolve before the application can progress.
Neither route wins on guaranteed approval
Neither a broker relationship nor an existing banking relationship establishes that a home loan will be approved. The lender must assess the application and the property offered as security against its requirements.
Broker assistance can help you prepare and understand an application. It does not give the broker authority to approve a bank loan. Equally, familiarity with NAB does not remove the need for a lending assessment.
For a 2026 property purchase, distinguish an initial borrowing discussion from an approval with conditions and from an unconditional lending decision. Ask exactly what has been assessed, what remains outstanding and whether the property itself has been considered.
This is an honest tie, not a reason to dismiss either route. Choose based on the advice and communication you need, then inspect the actual approval conditions. Before making a binding purchase commitment, obtain advice appropriate to your contract and financing position.
Pricing is a tie until you compare written proposals
There is no defensible cost winner without comparing the proposed loan and any service charges. Separate how the broker is paid from what the home loan costs. Those are related questions, but they are not the same question.
For the broker route, request written disclosure of any borrower-paid fees and lender-paid remuneration. Ask when any charge becomes payable and whether the arrangement changes if the application does not proceed. Do not assume the service is either free or more expensive than applying directly.
For NAB, assess the loan proposal itself. Check the interest structure, establishment charges, ongoing charges and any conditions attached to features you intend to use. A direct application is not proof of a lower total cost.
Compare the same borrowing scenario
Use the same loan amount, term, repayment basis and property purpose when comparing proposals. Otherwise, a difference in repayments can reflect different assumptions rather than better value.
Variable and fixed structures also create different trade-offs between rate certainty and flexibility. Ask about extra repayments, access to funds and consequences of changing the loan. The relevant terms belong to the proposed product, not to the broker-versus-bank label.
For your 2026 decision, request a written explanation of costs under the features and repayment behaviour you expect to use. No cost winner should be declared from a headline rate alone.
NAB wins for direct management of an existing NAB loan
NAB is the direct route when your task concerns the administration of a loan already held with NAB. Start with the lender when you need it to explain an account condition, repayment instruction or proposed change to its loan.
Broking advice serves a different purpose. Refinancing, accessing equity and reviewing a guarantor arrangement involve questions about whether the borrowing still suits your circumstances, not just how the existing account operates.
The trade-off is scope versus directness. A bank conversation addresses the bank’s loan; an advice conversation addresses your borrowing objectives and the arrangements under consideration. Neither automatically replaces the other.
Before choosing a route, name the problem. If you want an account explanation, contact the lender. If you want to reassess the financing arrangement, seek advice and ask what alternatives will actually be examined. That avoids treating every loan question as a reason to refinance.
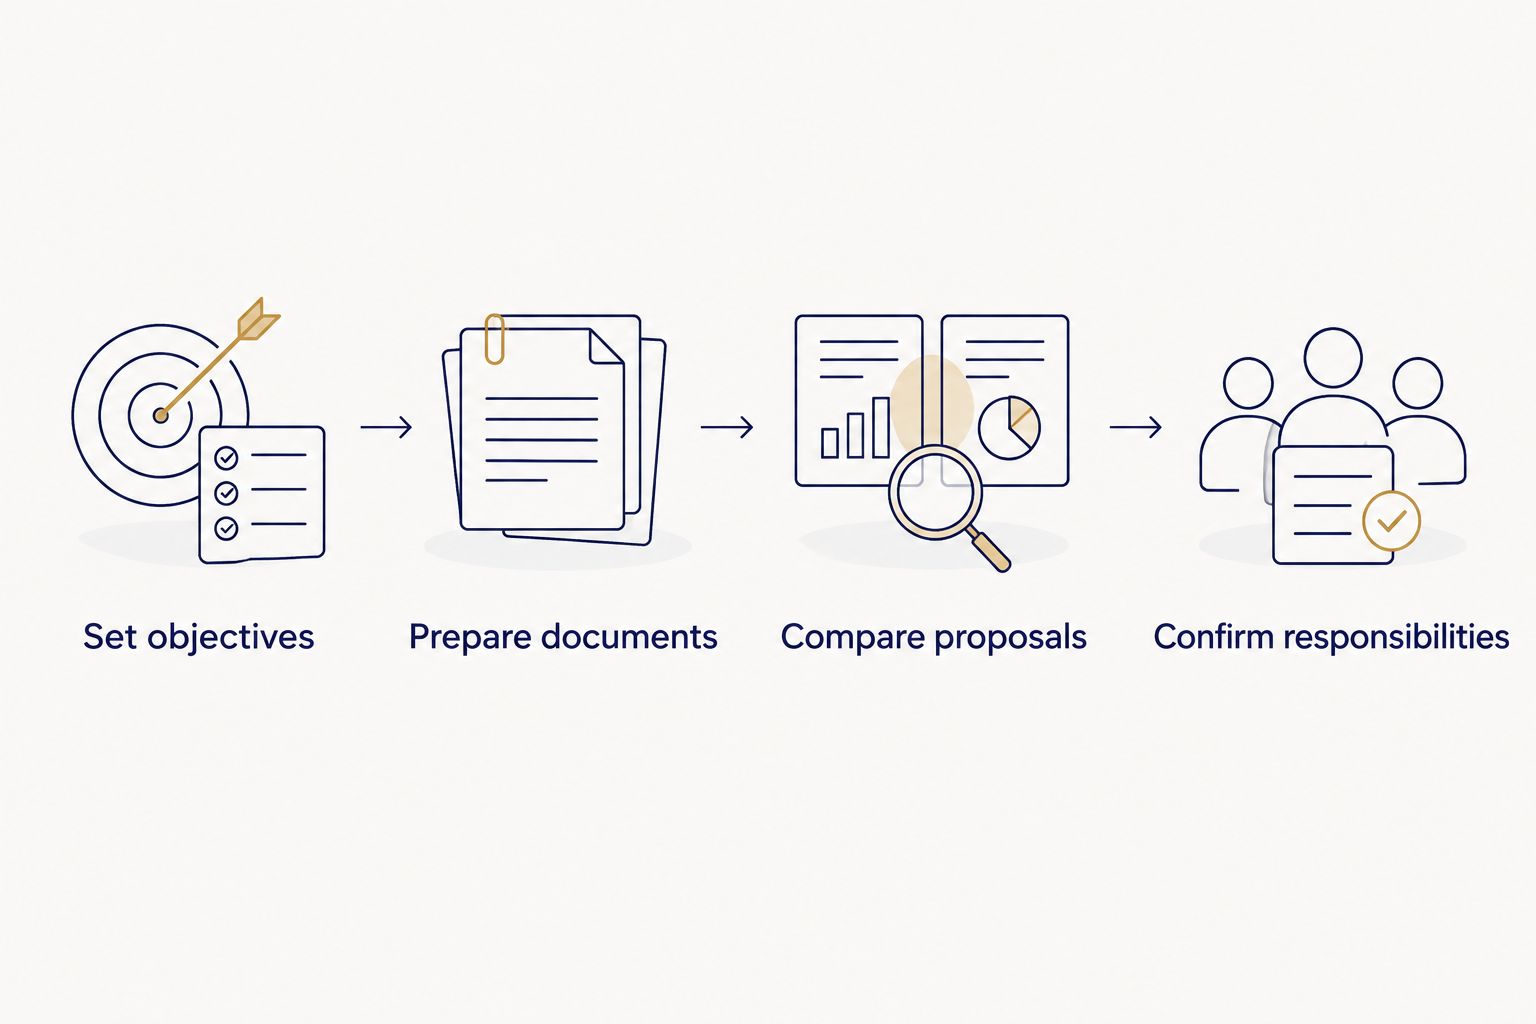
Make the comparison with the same brief
A useful 2026 comparison starts with a clear borrowing brief. Give each party consistent information, then assess the explanation as well as the proposal.
- Set objectives: Explain the purchase, refinance or equity outcome you want and the repayments you are comfortable managing.
- Prepare documents: Gather evidence of income, existing borrowing, savings and the property details relevant to the application.
- Compare proposals: Check the proposed structure, costs, features and any conditions using the same borrowing assumptions.
- Confirm responsibilities: Establish who handles questions, outstanding documents and communication before you proceed.
These steps help you distinguish useful advice from a proposal that merely looks attractive in isolation. Keep the written explanations so you can revisit the reasons for your decision.
Final verdict: choose the relationship you need
Choose Mortgage Pros if you need advice before selecting a loan
Best for: a doctor, home buyer or property owner seeking home loan advice and application support. The broker route fits when your main question is how to arrange borrowing around your circumstances, including refinancing, equity or a guarantor.
Ask about the scope of lender consideration, the proposed structure and remuneration before proceeding. The advisory service is the reason to choose this route; a promised approval outcome is not.
Choose NAB if you want to deal directly with your selected bank
Best for: a borrower who has chosen NAB and wants the bank to handle its own lending discussion. This route also fits a borrower seeking direct assistance with an existing NAB loan.
The advantage is directness. The limitation is that you still need to determine whether the bank’s proposal meets your objectives, rather than treating a familiar banking relationship as sufficient evidence.
| Dimension | Winner |
|---|---|
| Best for | Broker for advice; NAB for a selected-bank application |
| Direct lender access | NAB |
| Doctor-focused broking advice | Mortgage broker |
| Assisted application route | Mortgage broker |
| Guaranteed approval | Neither |
| Pricing | Tie until written proposals are compared |
| Direct management of a NAB loan | NAB |
Discuss your home loan today
Explain your borrowing goals and ask about advice, application support and the next steps.
FAQ
Is Mortgage Pros better than NAB for a home loan?
Mortgage Pros is the better fit for borrowers seeking mortgage broking advice and approval support; NAB is the better fit for borrowers who have selected NAB and want direct bank dealings. Compare the actual loan proposal separately from the service relationship.
Is a mortgage broker the same as a bank?
No. A mortgage broker helps arrange finance, while a bank assesses and provides its own lending. Broker involvement does not transfer the bank’s approval decision to the broker.
Which route should a doctor consider first?
A doctor seeking specialist home loan advice has a clear reason to consider a broker with a stated doctor home loan focus. A doctor who has already chosen NAB can approach the bank directly and ask how it will assess their circumstances.
Does applying directly to NAB guarantee a cheaper loan?
No. Direct application alone does not establish a lower total loan cost. Compare written proposals using the same borrowing amount, term, repayment basis and required features.
How do I find out what a mortgage broker charges?
Request written disclosure of borrower-paid fees and lender-paid remuneration before proceeding. Ask when charges become payable and what happens if the application does not proceed.
Can either option guarantee home loan approval?
Neither route establishes guaranteed approval. The lender assesses the application, supporting information and property against its lending requirements.
What should I prepare before speaking to a broker or NAB?
Prepare your borrowing objectives, income evidence, existing debt details, deposit information and relevant property details. Give each party the same information so you can compare their explanations and proposals fairly.
One last thing
A lower repayment does not, by itself, prove a better loan. A longer repayment term can reduce the scheduled repayment while extending how long you carry the debt. When refinancing, check the remaining term alongside the proposed new term rather than comparing the repayment alone.
Before accepting either route, ask for a plain-language answer to this question: what improves for you, and what do you give up? Contact us today to discuss your borrowing goals and the next step towards a suitable home loan.
Related guides