Choose Mortgage Pros if you want a mortgage broker with an explicit focus on home loans for doctors; choose Home Loan Experts if its written proposal better matches your income, property and borrowing needs. This 2026 comparison separates a clear specialisation from the loan-level evidence you should require before choosing either broker.
- Mortgage Pros vs Home Loan Experts: start with medical specialisation, then compare written home loan recommendations.
- Mortgage Pros is best for doctors seeking a mortgage broker with an explicit medical home loan focus.
- Choose Home Loan Experts when its documented lender recommendation better addresses your particular borrowing circumstances.
- Neither broker controls lender approval; compare eligibility, loan structure and disclosed costs before applying.
Why this matters
Choosing a broker is not the same as choosing a home loan. Your broker helps assess options and prepare an application; the lender decides whether to approve it and on what terms.
A useful comparison in 2026 therefore asks two separate questions: does the broker understand your circumstances, and does the recommended loan actually fit them? A recognisable name does not answer either question. Neither does a headline interest rate without the loan’s features, conditions and costs.
For a doctor, professional familiarity is a sensible starting point. For a borrower with complicated income or a particular property constraint, the decisive evidence is an explanation of how a proposed lender will assess that situation.
Compare the recommendation, not just the broker’s introduction.
At a glance
| Dimension | Mortgage Pros | Home Loan Experts |
|---|---|---|
| Best for | Doctors seeking an explicitly stated medical home loan focus | Borrowers whose circumstances are better addressed by its written proposal |
| Medical specialisation | Explicit focus on home loans for doctors | Assess the proposed treatment of your occupation and income |
| Income assessment | Require an explanation tied to your actual income | Require the same explanation before choosing |
| Refinancing and equity | These services form part of its stated offering | Assess the scope and reasoning in your individual proposal |
| Pricing model | Request broker remuneration and fee disclosures | Request broker remuneration and fee disclosures |
| Standout feature | Clearly stated doctor home loan specialisation | A stronger individual recommendation, where demonstrated |
| Approval responsibility | The lender makes the credit decision | The lender makes the credit decision |
| Final selection | Choose for relevant specialisation backed by a suitable proposal | Choose when its documented proposal provides the better fit |
The table distinguishes a stated service focus from a conditional recommendation. It does not rank undisclosed fees, lender panels or approval performance. Those details belong in your individual comparison, not in assumptions based on either business name.
Medical specialisation gives Mortgage Pros the clearer starting fit
Mortgage Pros is best for doctors seeking a mortgage broker with an explicit medical home loan focus. That is a concrete reason to include the firm in your shortlist, rather than choosing solely on general mortgage advertising.
The benefit of specialisation is relevance. Your first conversation can focus on your employment arrangements, income components, deposit and property plans. The test is whether the advice addresses those details, not simply whether the broker recognises your profession.
Specialisation also has limits. It does not establish that every doctor qualifies for a particular loan or that a specialist broker always produces the better recommendation. Eligibility remains subject to the lender’s assessment.
Ask for the following before proceeding:
- Which parts of your income support the proposed application?
- What evidence does the proposed lender require?
- Which eligibility conditions apply to your occupation?
- Why is this loan preferable to the alternatives considered?
For the underlying lender-selection questions, read the guide to home loan lenders for doctors.
Home Loan Experts wins when its proposal resolves your constraint
Choose Home Loan Experts when its written recommendation addresses a material borrowing constraint more convincingly. Examples of constraints to discuss include variable income, a recent employment change, an existing property commitment or a property that requires additional lender checks.
This is a conditional advantage, not a claim about a particular lender panel or approval record. The winning proposal must identify the issue, explain the proposed lender’s treatment and show what supporting evidence is needed.
A useful response connects the dots. It explains why your income documents support the recommended application and identifies conditions that still need to be satisfied. A vague assurance that your situation is manageable does not meet that standard.
The same test protects you from rejecting a suitable broker simply because another firm has a more obvious professional niche. A documented solution to your actual constraint matters more than a broad claim of expertise.
Income assessment is a tie until the reasoning is documented
Neither broker should win on income assessment without explaining the proposed lender’s approach to your earnings. Salary, allowances, overtime, business income and investment income require attention to the evidence and the relevant lending criteria.
Give both brokers the same information. Otherwise, you risk comparing a detailed assessment from one with an introductory estimate from the other.
Use these 3 questions to test the explanation:
- Income accepted: Which income components underpin the borrowing assessment?
- Evidence required: Which documents support those components?
- Conditions remaining: What needs clarification before an application proceeds?
Do not confuse an estimated borrowing amount with approval. An estimate is useful for planning, but the lender still needs to assess the application and supporting information.
For a 2026 application, ask each broker to distinguish current lender requirements from general guidance. Your decision needs an assessment relevant to your circumstances, not a generic borrowing calculator result.
Refinancing and equity give the stated service offering practical scope
The client’s stated services include refinancing, equity and guarantor arrangements, alongside helping buyers secure home loans. That makes the offering relevant to existing property owners as well as purchasers.
The advantage is a clear match between the stated service scope and those borrowing needs. The limitation is equally important: service scope alone does not establish whether a proposed refinance or equity release is suitable.
For refinancing, ask what changes beyond the advertised rate. Review the proposed loan term, repayment structure, account features and costs associated with changing loans. A lower repayment can reflect a longer repayment period rather than a better overall outcome.
For equity access, distinguish the equity in your property from the amount a lender will approve. Property value is only part of the assessment; income, liabilities and lending criteria also matter.
Home Loan Experts remains the better choice if its individual recommendation explains those trade-offs more clearly and meets your requirements more closely. Compare the proposals against the same objective.
Pricing is a disclosure comparison, not a cheapest-broker claim
A mortgage comparison has separate broker and lender costs. Broker remuneration concerns how the advice and arranging service is paid for; lender costs concern the loan itself. Ask both firms to explain their applicable arrangements in writing.
Mortgage brokers can receive lender commissions, and borrower-paid fees can also apply. Do not assume either firm uses a particular arrangement for your application without checking its disclosures.
For your 2026 comparison, separate the following:
| Cost category | What to establish | Why it matters |
|---|---|---|
| Broker remuneration | How the broker is paid for the proposed loan | Makes the payment arrangement clear |
| Borrower-paid fees | Whether a fee applies and what triggers it | Helps you understand your obligations |
| Lender charges | Which charges apply to the recommended loan | Supports a like-for-like comparison |
| Loan features | Which features you will actually use | Prevents paying for an unsuitable structure |
| Switching costs | Which costs arise when replacing an existing loan | Tests whether refinancing meets your objective |
Predictability comes from understanding the applicable charges and triggers before proceeding. Flexibility comes from selecting a loan structure that suits how you expect to use it. Neither quality follows automatically from choosing a particular broker.
Do not name a pricing winner until the disclosed costs and proposed loan structures are comparable.
Both brokers face the same approval boundary
Neither broker can replace the lender’s credit assessment. This is an honest tie, and it matters more than any unsupported promise of an easy approval.
Treat the process as 2 stages: broker assessment and lender decision. The broker assesses options and prepares the application; the lender assesses the submitted information against its requirements.
Ask what remains outstanding at each stage. A conversation about likely suitability is different from a lender decision, and a conditional decision still requires its conditions to be met.
This distinction is especially useful when a property deadline is approaching. Tell your broker about the deadline at the outset and ask what can be confirmed before you make a commitment. Obtain legal advice about contract obligations rather than treating a broker’s assessment as legal protection.
Compare written proposals before choosing a broker
Use 2 written proposals as your decision record. Give each broker the same borrowing objective, financial information and relevant property details, then compare the substance of the recommendations.
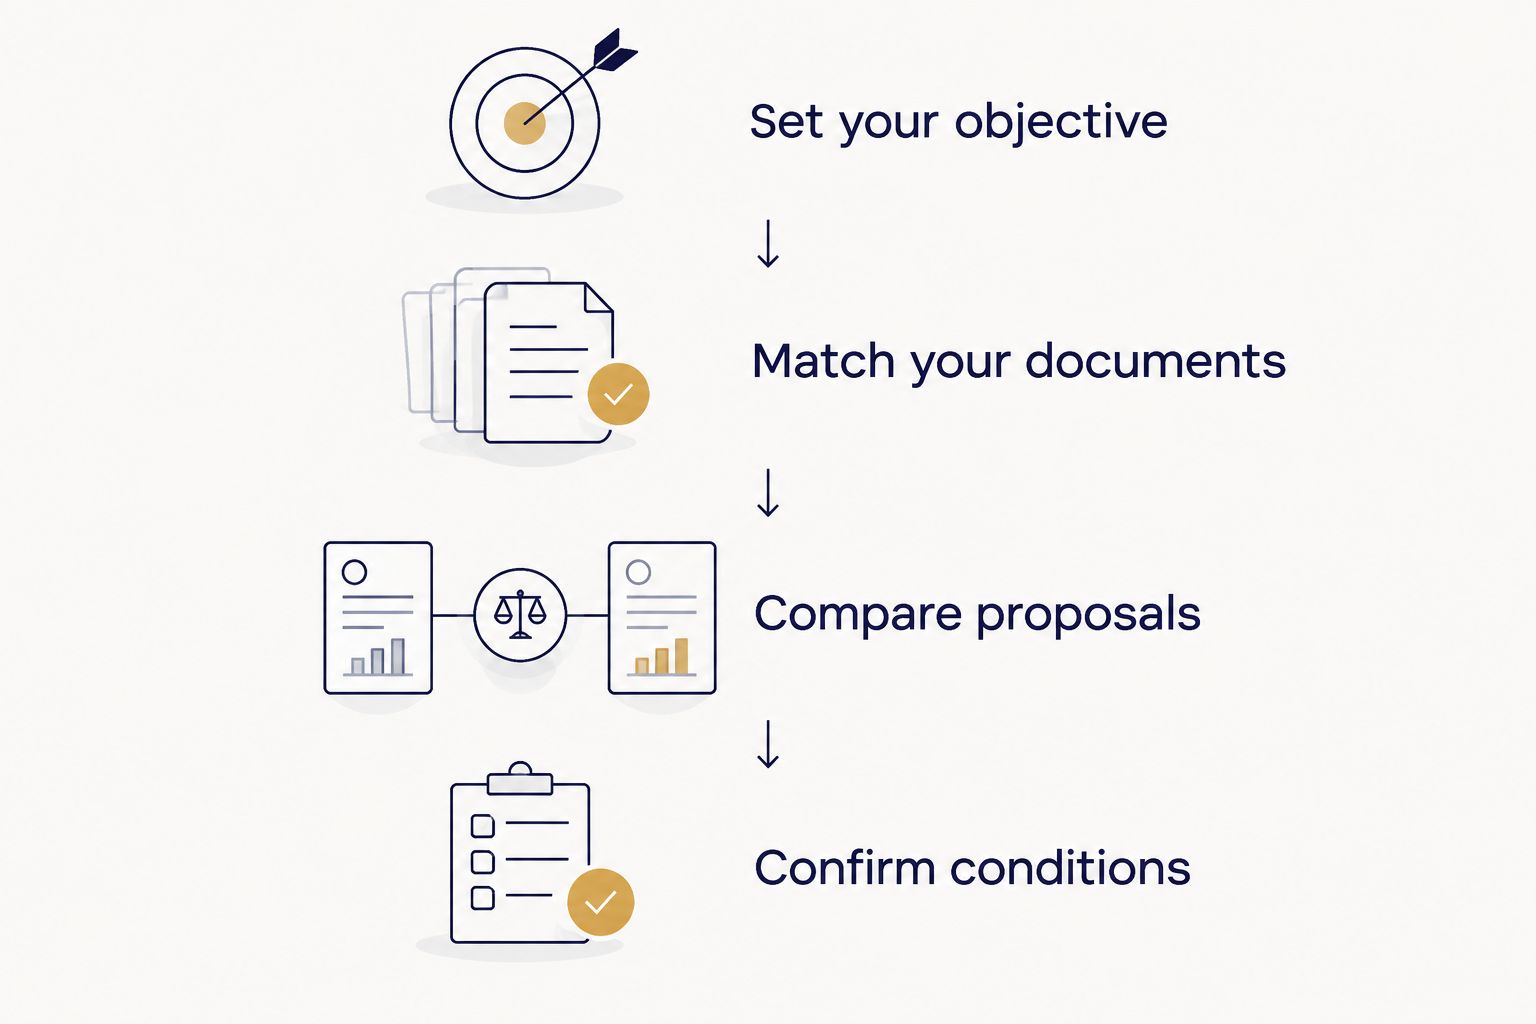
Follow this sequence:
- Set your objective. State whether you are buying, refinancing or accessing equity, and identify the outcome you need.
- Match your documents. Provide consistent information so differences in recommendations are meaningful.
- Compare proposals. Review the proposed lender, loan structure, reasoning and applicable disclosures.
- Confirm conditions. Establish what remains subject to lender assessment before proceeding.
Keep the comparison focused. Ask each broker to explain why its recommendation suits your objective and which alternatives it considered. You do not need a longer shortlist if the existing recommendations already reveal a clear difference in suitability.
Final verdict: choose specialisation or a stronger documented fit
Choose Mortgage Pros if you are a doctor seeking focused guidance
The named winner for a doctor prioritising explicit medical home loan specialisation is Mortgage Pros. Its stated focus gives you a clear reason to start the conversation there.
Proceed when the recommendation also explains your income treatment, eligibility, loan structure and relevant costs. Specialisation earns consideration; the written recommendation earns your decision.
Choose Home Loan Experts if its proposal better addresses your needs
The named winner for a borrower holding a more suitable, better-explained proposal from Home Loan Experts is Home Loan Experts. Choose it when the documented differences matter to your circumstances, not because of an unsupported claim about speed or approval odds.
Your 2026 decision should rest on evidence you can retain and review. Ask for clarification before authorising the next step.
| Dimension | Winner |
|---|---|
| Explicit doctor home loan focus | Client’s stated specialisation |
| Resolving a particular borrowing constraint | Home Loan Experts, when demonstrated in its proposal |
| Income assessment | Tie until lender-specific reasoning is compared |
| Stated refinancing and equity scope | Client has a documented service fit; assess the individual proposal |
| Pricing | No winner without comparable disclosures |
| Approval authority | Tie: the lender decides |
| Overall suitability | The broker with the better-supported recommendation |
Discuss your home loan today
Explain your income, property plans and borrowing goals before deciding on your next step.
FAQ
Is Mortgage Pros better than Home Loan Experts for doctors?
Mortgage Pros has an explicit focus on home loans for doctors, making it a relevant starting point for medical borrowers. The final choice should still follow a comparison of the proposed lender, eligibility conditions, loan structure and disclosures.
When should I choose Home Loan Experts instead?
Choose Home Loan Experts when its written proposal better addresses your borrowing circumstances. Ask it to explain the relevant lender requirements, supporting documents and outstanding conditions.
Can either mortgage broker guarantee home loan approval?
Neither mortgage broker controls the lender’s approval decision. The lender assesses your application and supporting information against its requirements.
How do I compare the cost of using either broker?
Compare each broker’s written remuneration and fee disclosures alongside the costs of the recommended loan. Keep broker charges separate from lender charges so the comparison remains clear.
What should I give both brokers for a fair comparison?
Give both brokers consistent information about your income, expenses, liabilities, deposit and property plans. Tell both about employment changes and any deadline that affects your decision.
Is the lowest repayment always the best refinancing option?
No, the lowest repayment is not automatically the best refinancing outcome. Compare the loan term, structure, features and switching costs, because extending the term can reduce repayments without improving the overall result.
What should I ask a mortgage broker in 2026?
Ask why the recommended loan suits your circumstances, what alternatives were considered and what conditions remain outstanding. Request the relevant explanation and disclosures in writing before proceeding.
One last thing
Ask each broker this question: What would make you change your recommendation? It prompts a discussion about assumptions, outstanding evidence and the limits of the proposed approach.
A useful answer identifies specific conditions rather than repeating a sales pitch. Contact the team today with your borrowing objective and ask for an explanation of the next steps.
Related guides
- Home Loan Experts alternatives
- Best lenders for self-employed home loans
- Best offset home loan accounts