Home loans for veterinarians are residential mortgages assessed against your income, deposit and debts to help you buy or refinance property. Your application needs to distinguish permanent salary from locum earnings or practice income, and veterinary registration alone does not establish eligibility for a professional lending concession.
- Compare home loans for veterinarians by income assessment, deposit requirements and loan features—not occupation labels alone.
- Mortgage Pros suits borrowers seeking mortgage broking advice rather than comparing home loans entirely themselves.
- Confirm whether a lender includes veterinarians in any professional policy before relying on an LMI waiver.
- Separate salary, locum income and practice earnings before requesting a borrowing assessment.
Why home loans matter for veterinarians
The right lender is one that accepts your documented income and supports your borrowing needs—not simply one advertising loans for medical professionals. A salaried vet, a locum contractor and a practice owner need different evidence, even when their work looks similar.
For your 2026 application, start with your employment structure rather than a lender shortlist. Mortgage Pros provides home loan advice and approval support; a broker assessment helps you connect your circumstances with relevant lending requirements.
Your occupation does not replace the usual checks on income, expenses, debts, deposit and property. Any professional concession is a separate eligibility question, not an approval promise.
Why income structure matters for veterinary borrowers
A permanent salary gives you a different starting point from changing locum assignments or income drawn from a veterinary practice. The task is to show what you earn, how it is received and what evidence supports its continuation.
For a practice owner, business revenue is not the same as personal income available for mortgage repayments. For an employed veterinarian, overtime or additional shifts need to be identified separately from base salary. Neither situation should be reduced to a single unexplained annual figure.
This distinction also shapes your lender comparison. A loan with attractive features is not useful if its income assessment does not fit your evidence. Resolve eligibility before spending time comparing features.
How to prepare your veterinary home loan application
1. Define your borrowing purpose
Start with a written brief. Record whether you are buying a home, purchasing an investment property, refinancing or seeking equity from an existing property. Add your intended ownership structure and whether another person will borrow with you.
Keep practice finance separate from the residential mortgage discussion. If you are also buying into a clinic, disclose that commitment so the assessment accounts for the debt and cash-flow obligations rather than treating the home loan in isolation.
For a 2026 purchase, distinguish your preferred moving date from any contractual deadline. Ask your conveyancer about finance conditions before signing; a borrowing estimate is not a substitute for legal advice.
- State the property's intended use.
- Identify every proposed borrower.
- List any planned practice purchase or buy-in.
- Record settlement or refinance deadlines.
- Set a repayment amount your household budget supports.
2. Separate your income sources
Build a simple income summary yourself before asking anyone to assess borrowing capacity. Put salary, additional employment income, contracting receipts and business distributions on separate lines. Match each line to evidence rather than combining gross receipts into an assumed salary.
Permanent employees should identify what is guaranteed under their employment terms. Locums should distinguish employee arrangements from contracting through an ABN or business entity. Practice owners should explain how money moves from the business to them personally.
For more detail on business-income assessment, read the guide to lenders for self-employed home loans. Mortgage Pros home loan advice can help you organise these distinctions, but you still need evidence supporting the application.
- Separate base salary from overtime and allowances.
- Match employment income to payslips and employment documents.
- Identify locum contracts and payment arrangements.
- Reconcile business income with tax and financial records.
- Flag recent changes in role, hours or ownership.
3. Calculate your deposit and loan-to-value ratio
List your savings and identify which funds are genuinely available for the purchase. Keep transaction expenses separate: a deposit calculation that uses every dollar leaves no allowance for other settlement obligations.
Loan-to-value ratio, or LVR, is the loan amount divided by the lender's assessed property value, expressed as a percentage. An 80% LVR means the loan represents 80% of that value; the remaining 20% represents equity before transaction costs. A lender's valuation can differ from the agreed purchase amount.
Australian Government Moneysmart guidance explains that lenders mortgage insurance is usually required when borrowing more than 80% of a property's value. Treat that as general guidance for your 2026 planning, not a promise about an individual application: professional policies and other arrangements have separate conditions.
- Calculate LVR using the assessed property value.
- Separate your deposit from transaction expenses.
- Document savings, gifts and other deposit sources.
- Ask whether lenders mortgage insurance applies.
- Retain a household cash buffer after settlement.
4. Verify professional-policy eligibility
Ask a direct question: does the lender's current professional policy include veterinarians? Do not assume that a page referring to doctors, medical professionals or healthcare workers includes veterinary practitioners.
Where a concession exists, ask what it changes. A reduced deposit requirement, an LMI waiver and an income-assessment rule are different benefits. None removes the need to satisfy the lender's other requirements.
Mortgage Pros home loan advice is best for borrowers who want help assessing lending options rather than managing comparisons alone. A broker's recommendation is not lender approval, and a professional title is not proof that a concession applies.
- Confirm that veterinarians are an eligible occupation.
- Ask what registration evidence is required.
- Check any employment or income conditions.
- Confirm the property's eligibility under the policy.
- Request application-specific confirmation before relying on a concession.
5. Match loan features to your cash flow
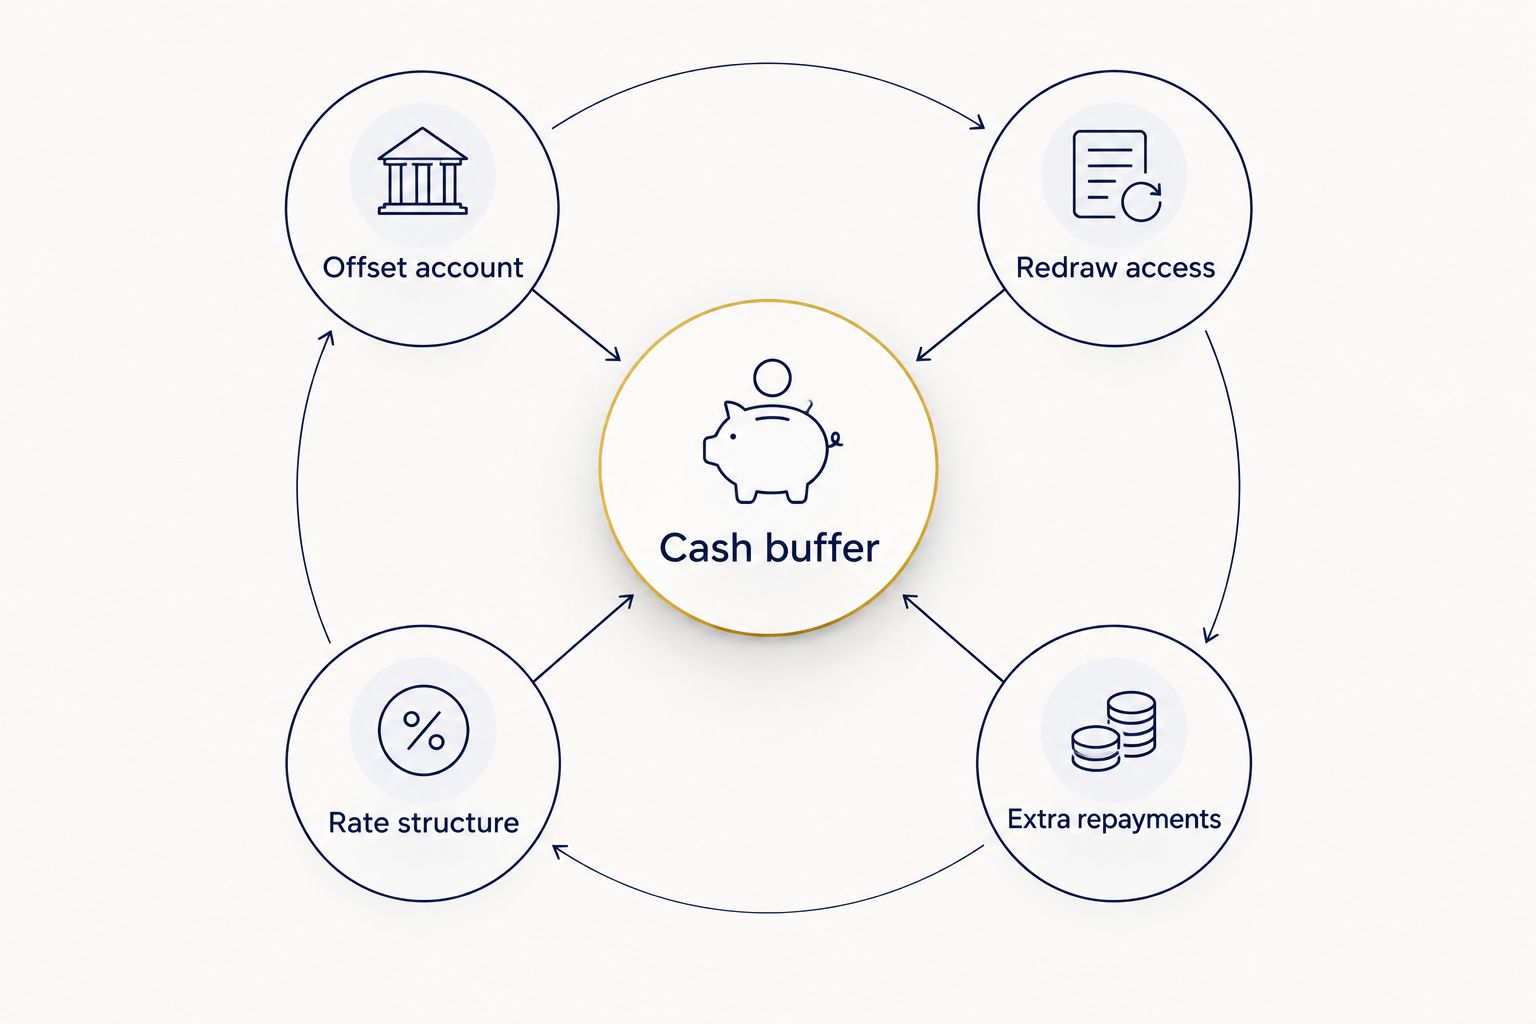
Write down how you expect to manage repayments and spare cash. An offset account, redraw facility, fixed rate and variable rate solve different problems; choosing every available feature is not a strategy.
A 100% offset account uses its eligible balance to reduce the loan balance on which interest is calculated. Redraw instead concerns access to eligible extra repayments already made into the loan. Access rules and product terms matter, especially if you expect to use those funds later.
For your 2026 comparison, assess features alongside the loan's overall terms. Ask a tax adviser before changing borrowing arrangements where a property is, or could become, an investment.
- Cash buffer: decide what must remain accessible.
- Offset account: check eligibility and account terms.
- Redraw access: check withdrawal conditions.
- Rate structure: compare certainty with flexibility.
- Extra repayments: confirm restrictions before choosing.
6. Prepare for assessment and settlement
Review your application documents for consistency before submitting them. Names, employment dates, income figures and liabilities should tell the same story across the application and supporting records.
Disclose credit cards, personal loans, study debt and business obligations. Explain irregular transactions or recent employment changes rather than leaving the lender to interpret them without context. Ask what evidence needs updating if your application extends beyond the original documents' validity.
Pre-approval is conditional and does not guarantee final approval for a particular property. Keep the lender or broker informed about changes before settlement, including new debt, changed employment or a revised purchase arrangement.
- Reconcile income figures across supporting documents.
- Disclose personal and business liabilities.
- Ask what conditions remain outstanding.
- Confirm property and valuation requirements.
- Report material changes before settlement.
Compare application routes for veterinarians
You can investigate lenders yourself, approach a broker or ask about a profession-based policy. These routes are not interchangeable: a professional policy is a possible lending pathway, not a separate adviser or an automatic approval.
Use the comparison below to choose how to investigate your options. Compare the quality of the assessment before choosing the application route.
| Option | Best for | Main benefit | Key limitation |
|---|---|---|---|
| Direct lender application | Borrowers comfortable preparing documents and assessing one lender's terms | Direct discussion with the lender assessing the application | A single lender's assessment does not compare alternatives |
| Mortgage broker advice | Borrowers wanting help comparing requirements and preparing an application | Advice connecting income, deposit and borrowing goals | A broker's lender panel does not necessarily represent the whole market |
| Professional-policy enquiry | Veterinarians checking occupation-based concessions | Establishes whether a specific professional policy applies | Eligibility varies; veterinary registration alone proves neither inclusion nor approval |
| Guarantor arrangement | Borrowers considering family security support | Provides another security structure to discuss | Exposes the guarantor to obligations and risk; independent advice is essential |
Ask a broker which lenders were considered and why the recommended loan fits your circumstances. Ask a direct lender the same practical questions about income acceptance, deposit requirements and outstanding conditions.
For a guarantor arrangement, make sure the guarantor understands the proposed guarantee's scope and release requirements. Do not treat family support as a substitute for an affordable repayment plan.
Discuss your home loan application
Ask Mortgage Pros about your income evidence, deposit and borrowing goals.
Common mistakes veterinarians make
Assuming doctor lending policies include vets
A policy written for doctors does not automatically include veterinarians. Confirm the eligible occupation and conditions for your application rather than relying on a broad healthcare label.
Ask for the eligibility basis before planning around a concession. This matters particularly when your deposit depends on an assumed LMI waiver.
Treating locum receipts as guaranteed salary
Locum work can involve different employment and contracting arrangements. Combining all receipts into a salary figure hides the evidence a lender needs to assess that income.
Separate employment income from contracting income, and explain changes in assignments. Keep the documents that show how payments were earned.
Using practice turnover as personal income
A veterinary practice's revenue also supports business expenses and obligations. It is not automatically the amount available to meet your household mortgage repayments.
Present your ownership structure, financial records and personal income clearly. Ask how the lender treats business commitments rather than assuming they sit outside the assessment.
Changing work arrangements during approval
Moving from salaried employment to locum work, becoming a contractor or buying into a practice changes the facts supporting an application. An earlier assessment does not settle how the new arrangement will be treated.
Before making the change, discuss its lending implications. If the change has already happened, disclose it and update the evidence.
Choosing features without checking access rules
An offset account and redraw facility are not the same arrangement. Neither should be selected solely because another veterinarian recommends it.
Check how each feature works under the actual loan terms. Match the choice to your cash buffer, repayment habits and intended property use.
FAQ
What’s the best home loan for a veterinarian in Australia?
The best home loan for a veterinarian is one that accepts their documented income and suits their deposit, repayment budget and property purpose. Compare eligibility first, then assess loan features and conditions.
Do veterinarians automatically qualify for an LMI waiver?
No, veterinary registration does not automatically qualify you for an LMI waiver. Ask whether the lender’s current professional policy includes veterinarians and which additional conditions apply.
Can I apply for a home loan while working as a locum vet?
You can apply while working as a locum vet, but approval depends on the lender’s assessment of your income and overall circumstances. Identify whether you are an employee or contractor and provide evidence supporting your earnings.
How much deposit does a veterinarian need in 2026?
There is no universal deposit requirement for veterinarians in 2026. The required amount depends on the lender, assessed property value, loan structure and eligibility for any applicable policy, with transaction expenses considered separately.
Can a veterinary practice owner get a residential home loan?
A veterinary practice owner can apply for a residential home loan using evidence appropriate to their business and personal circumstances. Business turnover alone does not establish personal income available for repayments.
Is an offset account better than redraw for a vet?
An offset account is not automatically better than redraw for a veterinarian. Compare access rules, loan terms and how you intend to manage spare cash, and seek tax advice where investment use is relevant.
Should I use a mortgage broker or apply directly to a bank?
Use a mortgage broker if you want help comparing lender requirements and preparing your application; apply directly if you are comfortable assessing a lender’s offering yourself. Ask a broker about panel limitations and ask either adviser to explain the recommendation.
One last thing
You do not need a loan labelled for veterinarians to find a suitable mortgage. A standard home loan that fits your income evidence and repayment needs deserves consideration alongside any professional-policy option.
For your next step, prepare an income summary, deposit breakdown and list of liabilities before comparing lenders. Contact Mortgage Pros today to discuss your home loan goals and the evidence your application needs.
Related guides
- Compare offset home loan accounts
- Understand low-deposit home loan options
- Explore guarantor home loan lenders