Home loans for pharmacists are residential mortgages assessed against your income, deposit, debts and property, with the aim of funding a home or investment purchase. This 2026 guide explains how to prepare an application when your earnings include pharmacy employment, locum work or business income, without assuming your profession guarantees approval.
- Home loans for pharmacists depend on verified income and lender criteria, not your job title alone.
- Mortgage Pros suits pharmacists seeking broker-led home loan guidance rather than a direct lender application.
- Separate salary, locum earnings and pharmacy business income before comparing lenders.
- Check lenders mortgage insurance eligibility explicitly; doctor home loan concessions do not automatically cover pharmacists.
Why home loans matter for pharmacists
Your employment arrangement determines which evidence a lender needs. A salaried pharmacist, a locum working across pharmacies and a pharmacy owner can earn income through different structures, so the same application checklist will not suit everyone.
Start with your circumstances, not a headline offer. Mortgage Pros provides mortgage broking services for borrowers seeking home loan advice and approval support; your enquiry should explain how you earn, what you want to buy and what deposit you hold.
For your 2026 application, distinguish borrowing capacity from affordability. Borrowing capacity is the lender's assessment; affordability is whether repayments leave enough room for your actual household spending, professional expenses and savings goals.
A pharmacist's occupation is context for an application, not a substitute for evidence of repayment capacity. Ask which income sources the lender accepts, what documents support them and whether any professional concession expressly includes pharmacists.
How to prepare your pharmacist home loan application
1. Map your income before comparing lenders
Start manually with your payslips, employment agreement, bank statements and tax records. Separate guaranteed earnings from overtime, allowances, locum invoices and business distributions so you can explain each source clearly.
For an employed pharmacist, the key distinction is contracted income versus additional earnings. For a locum, explain whether you receive wages through payroll or invoice as a business; the word locum alone does not tell a lender how to assess you.
Do not combine gross pharmacy turnover with your personal salary and call the total household income. Business revenue, business profit and money available to you are different figures.
- Employment income: identify your base salary, employment status and contracted hours.
- Variable income: separate overtime, additional shifts and allowances from base pay.
- Locum income: record who pays you and whether you receive payslips or issue invoices.
- Business income: distinguish pharmacy trading results from personal drawings or distributions.
- Supporting evidence: reconcile the income you declare with the documents you supply.
2. Separate your deposit from your cash buffer
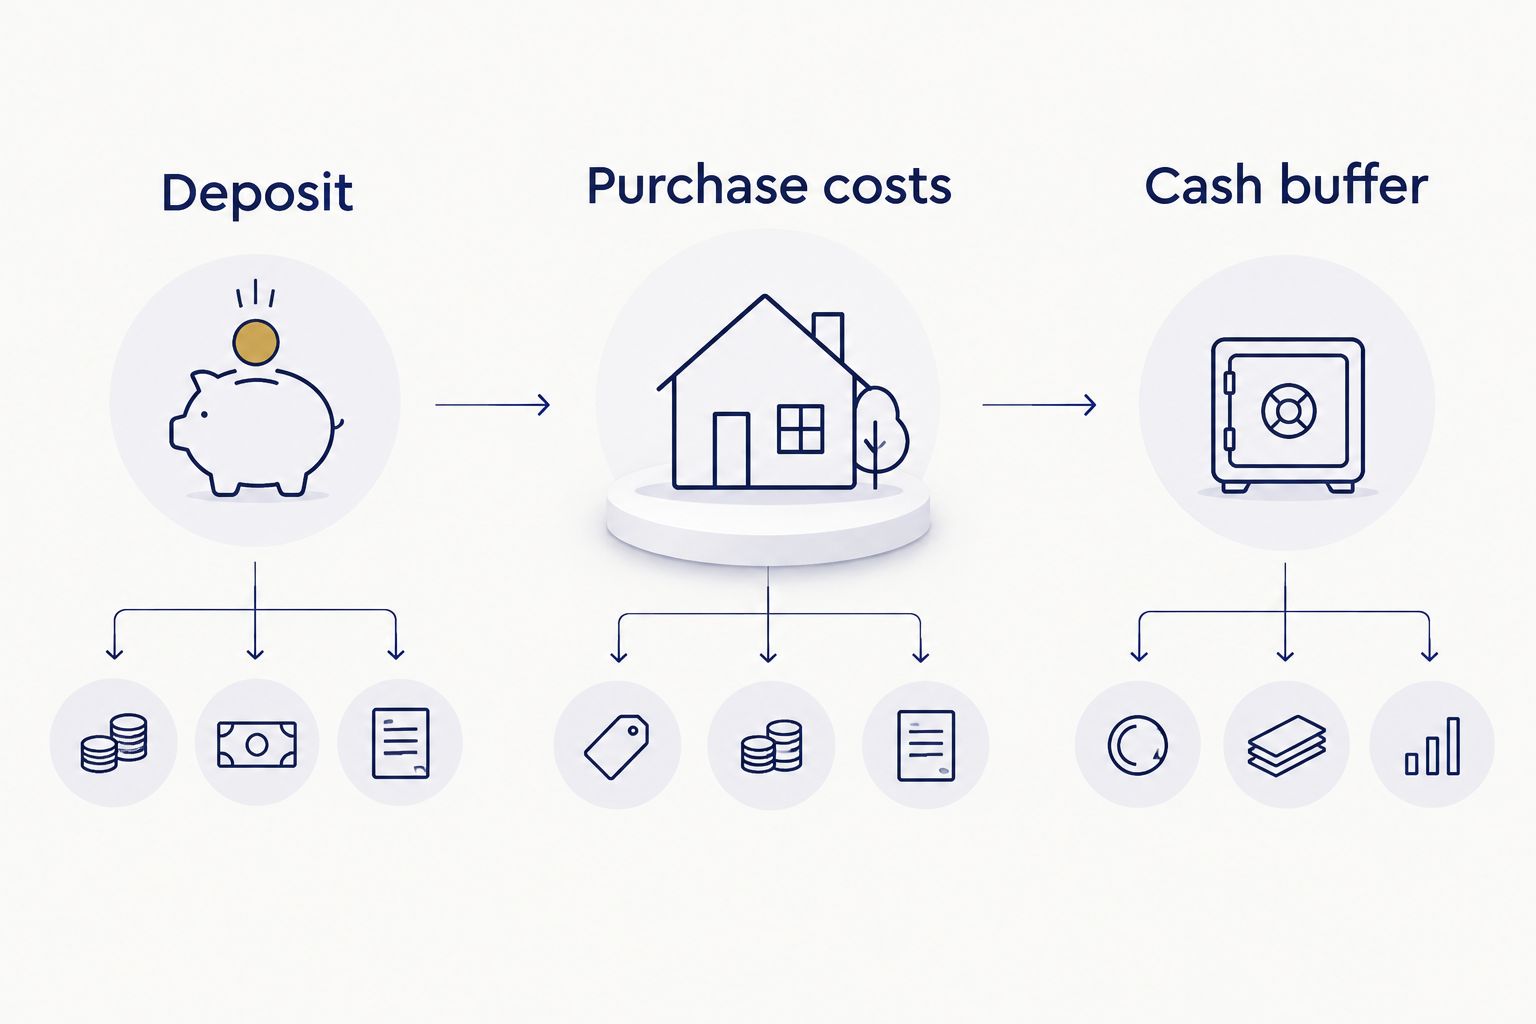
Build a simple worksheet showing savings, funds committed to the purchase and money retained afterwards. A deposit is not the entire cash requirement: purchase costs, moving expenses and your ongoing buffer need separate treatment.
Loan-to-value ratio, or LVR, expresses the loan as a percentage of the lender's property valuation. As a mathematical illustration, an 80% LVR leaves a 20% equity share; a 90% LVR leaves a 10% equity share, before considering purchase costs or differences between valuation and purchase amount.
These ratios explain the calculation, not an offer or approval threshold. Lenders mortgage insurance, known as LMI, protects the lender rather than you, and its application depends on the lender and loan circumstances.
- Deposit: identify funds genuinely available for the property purchase.
- Purchase costs: budget separately for applicable duties, legal work and other transaction expenses.
- Cash buffer: retain money for household needs and interruptions to earnings.
- LVR: calculate borrowing against the lender's valuation, not just your expectations.
- LMI: ask whether it applies and whether pharmacists qualify for any exemption.
3. Match the lender to your employment structure
Read each lender's published eligibility information and prepare questions about anything unclear. Record whether the lender's requirements match your current employment, rather than treating every pharmacy role as equivalent.
Mortgage Pros can help you seek home loan advice and approval support, but a broker does not replace the lender's assessment. Ask the broker to explain why a proposed lender fits your documented earnings and which conditions still need confirmation.
If you own a pharmacy or invoice through your own business, review the guide to lenders for self-employed home loans. Keep the property loan discussion distinct from any finance used to acquire or operate the pharmacy.
- State whether you are permanent, casual, on probation, contracting or self-employed.
- Ask how the lender treats overtime, locum income and multiple employers.
- Confirm the evidence required for pharmacy ownership or business distributions.
- Request written confirmation of any pharmacist-specific eligibility claim.
- Ask which lenders were considered and why the recommended option fits.
4. Compare loan features against your cash flow
Create your own comparison sheet before choosing a loan structure. Compare repayments, the loan term, account features and restrictions against how your household receives and spends money.
An offset account reduces the loan balance used to calculate interest when it is linked to an eligible loan. Redraw provides access to eligible additional repayments under the lender's rules; it is not the same arrangement as holding money in a separate offset account.
Fixed and variable rates also solve different problems. Fixed repayments offer budgeting certainty during the fixed period, while variable loans leave you exposed to rate changes; check the specific conditions rather than assuming either structure is automatically better for pharmacists.
- Identify whether repayment certainty or flexibility matters more to your household.
- Check whether an offset account is available on the proposed loan.
- Read redraw access conditions and restrictions on additional repayments.
- Ask about early repayment and break-cost provisions before fixing.
- Consider how an extended leave period would affect your preferred structure.
5. Prepare a consistent document pack
Use a folder organised by income, savings, liabilities and property information. Supply the documents the lender requests, and make sure names, dates and declared figures agree across the application.
A pharmacist moving from employment into business ownership should explain that transition directly. Documents showing the previous salary alone do not explain the new business income, and an unsigned forecast is not the same as an established trading result.
For a joint application, organise both applicants' circumstances. Your partner's debts, income and commitments form part of the household assessment even when the property search centres on your pharmacy career.
- Keep identification and personal details consistent across records.
- Supply payslips, employment details and tax records as requested.
- Include business financial information where relevant to your income.
- Disclose credit cards, personal loans, education debts and existing mortgages.
- Explain unusual account transfers, employment changes or income gaps accurately.
6. Test repayments against your real budget
Use a repayment calculator and your actual spending records to build a household budget. Include expenses that do not appear every pay cycle, such as professional registration, insurance, training and annual bills where they apply to you.
For your 2026 budget, test a quieter locum period or the loss of additional shifts rather than assuming every recent payment continues. If you plan parental leave, reduced hours or a pharmacy purchase, assess the home loan against that plan before committing.
Choose a repayment level your household can sustain, not simply the largest loan a calculator displays. A lender's assessment and your personal comfort level answer different questions.
- Calculate repayments using the proposed loan amount and term.
- Repeat the calculation with a higher interest rate as a stress test.
- Separate essential spending from discretionary spending without understating either.
- Include business commitments and guarantees that affect your finances.
- Decide what cash buffer you want to retain after settlement.
7. Confirm approval conditions before committing
Ask for the status and conditions of any approval in writing. Pre-approval is conditional; it does not mean every property, valuation or later change in circumstances is accepted.
Before signing a contract or bidding at auction, obtain advice from your solicitor or conveyancer about your obligations. Confirm the finance position with your broker or lender, particularly if employment, debts or the property choice has changed.
Keep your 2026 application current through settlement. A new credit commitment or material change in earnings needs to be disclosed, not left for the lender to discover later.
- Read the approval conditions and expiry details.
- Confirm whether property valuation or further income checks remain outstanding.
- Tell your broker or lender about changes to employment and liabilities.
- Ask your legal adviser to explain contract and finance conditions.
- Check settlement requirements before arranging your move or other commitments.
Discuss your pharmacist home loan today
Explain your income structure, deposit and property plans before choosing your next application step.
Compare application routes for pharmacists
The best application route depends on how much help you need matching your circumstances to lender requirements. In 2026, compare the support and limitations of each route rather than treating an online estimate as an approval decision.
| Option | Best for | Main benefit | Key limitation |
|---|---|---|---|
| Direct lender application | Pharmacists who have identified a lender that fits their circumstances | You discuss the application directly with that lender | The discussion covers that lender's products, not the whole market |
| Mortgage Pros mortgage broking | Pharmacists seeking help with home loan advice and approval support | Broker-led guidance through loan selection and application preparation | Approval remains subject to the lender's assessment; ask about lender coverage |
| Online comparison and calculators | Pharmacists building an initial shortlist independently | You can organise features and repayment scenarios yourself | A comparison result does not establish income acceptance or approval |
Mortgage Pros is best for pharmacists seeking broker-led home loan guidance rather than a direct lender application. Ask how recommendations are selected, what lender coverage applies and what remains subject to confirmation.
You do not need to choose a route before organising your documents. A clear income summary, deposit breakdown and household budget improve the quality of the conversation whichever route you take.
Common mistakes pharmacists make
Assuming doctor concessions include pharmacists
A policy for doctors does not establish eligibility for pharmacists. Ask whether your exact occupation and employment arrangement qualify, and request the relevant conditions before relying on an LMI exemption or other concession.
Treating every additional shift as guaranteed income
Recent overtime and locum receipts need to be identified separately from contracted earnings. Ask how the lender assesses those payments rather than building your purchase budget around an unconfirmed income figure.
Mixing pharmacy finances with personal borrowing capacity
Pharmacy turnover is not personal disposable income. Explain business debts, drawings and ownership arrangements clearly, and have your accountant help reconcile business records with your personal financial position.
Spending the entire savings balance on the purchase
A larger deposit does not remove the need for settlement expenses and a household buffer. Keep these amounts separate so your application plan does not leave you relying on the next pay cycle for every unexpected bill.
Choosing features without checking restrictions
An offset account, redraw facility or fixed period only helps if its rules suit your needs. Read the actual loan conditions, particularly if you expect changing hours, a move into ownership or future investment borrowing.
FAQ
Can pharmacists get a home loan in Australia?
Yes, pharmacists can apply for Australian home loans, subject to the lender’s income, credit, deposit and property requirements. Your occupation alone does not guarantee approval.
Do pharmacists automatically qualify for an LMI waiver?
No, pharmacists do not automatically qualify for an LMI waiver because they work in healthcare. Ask whether the lender expressly includes pharmacists and confirm all applicable conditions.
Can a locum pharmacist use income from several pharmacies?
Income from several pharmacies requires assessment under the lender’s income rules. Explain whether you receive wages or invoice as a business, and provide the supporting evidence requested.
How does a pharmacy owner apply for a home loan?
A pharmacy owner needs to explain their ownership structure, personal income and business commitments. The lender determines which business and personal financial documents it requires.
What deposit does a pharmacist need for a home loan?
The required deposit depends on the lender, property, loan structure and any applicable eligibility rules. Budget separately for purchase costs and retained cash rather than treating all savings as the deposit.
Is a mortgage broker better than applying directly to a bank?
A broker suits borrowers who want help assessing loan options and preparing an application; a direct application suits borrowers who have already identified a suitable lender. Neither route guarantees approval, and you should ask about lender coverage and recommendation criteria.
Does pre-approval mean I can buy any property?
No, pre-approval does not mean every property will be accepted. Read the conditions and confirm the property, valuation and remaining requirements before making a binding commitment.
One last thing
The most useful detail in your first enquiry is not simply that you are a pharmacist. It is how you are paid: permanent employment, casual shifts, locum invoices, pharmacy ownership or a combination.
Send that summary alongside your deposit position and property plans when you contact Mortgage Pros today. Ask for the evidence and eligibility questions to resolve before submitting an application; this guide is general information, not a personal lending recommendation.
Related guides
- Compare offset home loan accounts
- Understand low-deposit home loan options
- Explore guarantor home loan lenders