Aussie Home Loans helps borrowers compare home loans through a mortgage broker rather than approaching every lender separately. That approach stops being enough when you need a clearer explanation of how a proposed loan fits your income, property plans and borrowing risks. The best Aussie Home Loans alternative in 2026 is Mortgage Pros if you need doctor-focused home loan advice; a direct lender if you have already chosen your bank and want to apply directly.
- For Aussie Home Loans alternatives, choose Mortgage Pros for doctor-focused mortgage broking and home loan advice.
- Consider Mortgage Choice when you want a second mortgage broker assessment before selecting a lender.
- Apply directly to a lender when you understand its home loan terms and do not need broker comparisons.
- Compare refinancing costs, loan structure and approval conditions, not just the advertised interest rate.
Why this matters
Choosing a mortgage broker and choosing a home loan are different decisions. Your broker helps assess options and supports your application; the lender decides whether to approve the loan and on what terms.
For your 2026 shortlist, separate the quality of the advice from the appeal of the proposed product. A familiar broker name does not establish that a particular loan suits your circumstances. Equally, changing brokers does not remove a lender's income, credit or property assessment requirements.
Start with the problem you need solved: buying your first property, refinancing, accessing equity or arranging a guarantor loan. Then ask each provider to explain the recommended structure, its limitations and the alternatives considered.
Aussie Home Loans alternatives at a glance
These options represent different ways to obtain a home loan, not interchangeable products. Use the table to choose an advice route before comparing individual loan offers.
| Provider or route | Best for | Distinguishing feature | How it differs from Aussie |
|---|---|---|---|
| Aussie Home Loans | Borrowers who want mortgage broker assistance | Broker-supported loan comparison and application | The benchmark: assess the individual recommendation and service |
| Mortgage Pros | Doctors seeking specialist home loan advice | Doctor home loan specialisation, alongside refinancing, equity and guarantor support | Offers a doctor-focused advice route |
| Mortgage Choice | Borrowers seeking another broker assessment | An alternative mortgage broking network | Gives you another broker's assessment; it does not guarantee a different outcome |
| Direct lender application | Borrowers who have selected a lender | Application directly with the institution providing the loan | Removes the broker from the application route; you handle comparisons yourself |
There is no universal winner for every borrower. The right alternative depends on whether your unmet need is specialist advice, another assessment or a direct application.
1. Mortgage Pros: best for doctor-focused home loan advice
Mortgage Pros is a Sydney-based mortgage broking firm serving home buyers and property owners across Australia. Its stated specialisation is home loans for doctors, with services covering refinancing, equity and guarantor arrangements. That makes it a relevant alternative when you want your occupation and broader borrowing plans discussed together.
Best for: Doctors seeking home loan advice and approval support, including borrowers reviewing an existing mortgage.
The useful comparison is not simply which broker recognises your profession. Ask how your income evidence will be assessed, which eligibility conditions matter and why the proposed loan structure suits your plans. Specialist advice should produce a clear explanation, not an assumption that your occupation guarantees approval.
Where it shines
- Doctor home loans are an explicit specialisation, rather than a conclusion drawn from general mortgage broking services.
- Refinancing, equity and guarantor support allow you to discuss more than the initial purchase.
- The firm serves borrowers across Australia, despite being based in Sydney.
Where it falls short
- A mortgage broker cannot approve your loan; the lender makes that decision.
- Doctor-focused advice does not replace a lender's assessment of income, debts, credit history and the property.
- The specialisation alone is not a reason to switch if your existing broker already explains your options clearly.
Head-to-head: specialist advice versus Aussie
| Dimension | Mortgage Pros | Aussie Home Loans |
|---|---|---|
| Advice route | Mortgage broker | Mortgage broker |
| Doctor lending focus | Explicit stated specialisation | Ask your proposed broker about relevant experience |
| Loan decision | Made by the lender | Made by the lender |
| Selection test | Quality of the explanation and fit with your circumstances | Quality of the explanation and fit with your circumstances |
For a 2026 application, bring your income documents, current loan details and intended property use to the conversation. Ask what remains subject to lender assessment before treating any proposed arrangement as settled.
Verdict: Shortlist for doctor-focused advice; select only after reviewing the recommendation.
2. Mortgage Choice: best for a second broker assessment
Mortgage Choice is another mortgage broking network to consider alongside Aussie. Its role offers a familiar route: discuss your circumstances with a broker, review proposed lending options and receive application assistance.
Best for: Borrowers who want another broker to assess the same borrowing brief before committing.
A second assessment is useful only if you can compare the reasoning. Give both brokers the same income, debt, deposit and property information, then ask each to explain why the recommended lender and structure fit. Otherwise, different answers can reflect different assumptions rather than better advice.
Where Mortgage Choice shines
- It provides an alternative broker relationship without requiring you to manage the entire lender comparison yourself.
- Another broker assessment gives you an opportunity to question the original recommendation.
- You can assess how clearly the broker explains the application process before choosing whom to engage.
Where Mortgage Choice falls short
- Moving between broking networks does not guarantee a different lender recommendation.
- A second assessment does not guarantee approval or a better borrowing outcome.
- The network name does not answer whether the individual broker understands your circumstances.
Head-to-head: Mortgage Choice versus Aussie
| Dimension | Mortgage Choice | Aussie Home Loans |
|---|---|---|
| Advice route | Mortgage broker | Mortgage broker |
| Application support | Broker-assisted | Broker-assisted |
| Credit approval | Lender decision | Lender decision |
| What to compare | Individual broker's explanation and proposed structure | Individual broker's explanation and proposed structure |
Do not turn the comparison into a competition over the largest borrowing estimate. Ask what assumptions support the estimate and which expenses or commitments have been included.
Verdict: Shortlist for a second assessment, not for a promised different result.
3. Direct lender application: best for borrowers choosing their own bank
Applying directly means dealing with the institution that will provide the loan. You take responsibility for comparing it with other lenders and deciding whether its products meet your needs.
Best for: Borrowers who have selected a lender and understand the proposed loan's conditions.
Where a direct application shines
- You discuss the application directly with the lender assessing it.
- You can focus on a known institution rather than choosing a broker first.
- The route suits borrowers who want to conduct their own comparisons.
Where a direct application falls short
- The lender discusses its own products, not a broker-led comparison across lenders.
- You must organise competing offers and assess the differences yourself.
- Direct access does not remove credit assessment or guarantee approval.
Head-to-head: direct lender versus Aussie
| Dimension | Direct lender application | Aussie Home Loans |
|---|---|---|
| Product discussion | The chosen lender's products | Broker-led assessment of lending options |
| Comparison work | Managed by you | Supported by the broker |
| Application contact | Lender | Broker, with lender assessment |
| Approval | Subject to lender criteria | Subject to lender criteria |
Verdict: Select this route when you want to manage lender selection yourself; skip it when you need broader advice.
Why borrowers consider switching from Aussie
A reason to compare alternatives is not proof that Aussie has done something wrong. The practical reasons below are needs to resolve, not claims about its customers or service.
- Specialist advice: You want the broker to explain how your medical income or employment circumstances affect the application.
- Recommendation clarity: You want a clearer account of why one loan was recommended over another.
- A changed objective: You are now considering refinancing, equity access or a guarantor arrangement rather than only a purchase.
- A second assessment: You want another professional to review the same information before you commit.
- More direct control: You have chosen a lender and prefer to manage the application yourself.
For a 2026 refinance, distinguish changing brokers from changing loans. Speaking to another broker does not itself require you to refinance. First establish whether the proposed change addresses a real problem with your current arrangement.
If an application is already underway, ask how changing the application route affects outstanding documents, deadlines and lender communication. Avoid leaving either provider uncertain about which application you intend to proceed with.
How to compare your shortlist before applying
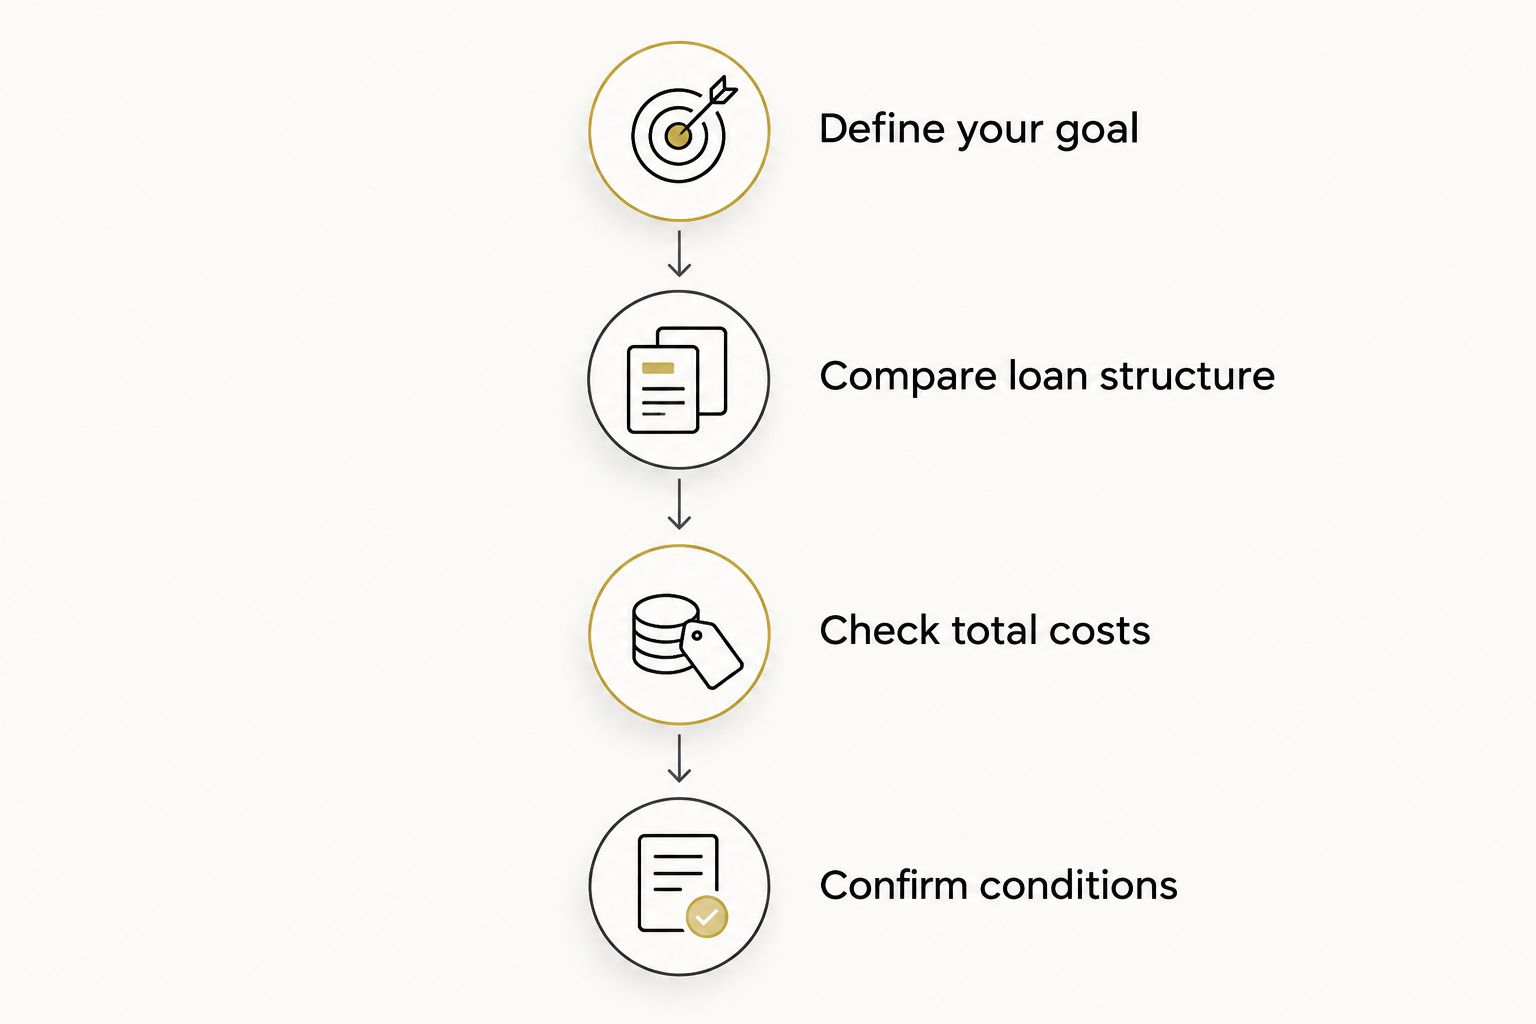
Use 1 consistent borrowing brief for every provider. Include your purpose, income, existing debts, deposit or equity, property details and timing. Consistent information makes the recommendations easier to assess.
Define your goal
State what you need the loan to achieve. A purchase, refinance and equity release raise different questions; an investment property also needs to be identified as such. Tell the provider about relevant plans rather than asking only for the maximum loan amount.
Compare loan structure
Request 2 written loan scenarios if you are deciding between materially different structures, such as fixed and variable borrowing. Ask each provider to explain repayment arrangements, offset or redraw features where applicable, and restrictions relevant to your plans.
Check total costs
Look beyond the headline interest rate. Ask for an explanation of applicable fees, refinance expenses and any costs of leaving your current loan. A comparison rate is a useful starting point, but its standard assumptions do not replace a comparison based on your proposed borrowing.
Confirm conditions
Put 3 questions in writing: what remains subject to assessment, which documents are outstanding, and what must happen before settlement? Keep a pre-approval separate from unconditional approval, and ask the lender or broker to explain the conditions attached to any approval.
For your 2026 decision, keep the written explanations beside each other. If a feature matters to you, confirm that the actual proposed loan includes it rather than relying on a general description of the lender's products.
Discuss your home loan options today
Explain your purchase, refinance or equity goals and ask for a clear assessment of your next step.
When staying with Aussie is the right call
Staying with Aussie is reasonable when your broker understands your circumstances, explains the recommendation clearly and supports your application effectively. You do not need to change providers simply because alternatives exist.
Give your current broker a chance to answer specific unresolved questions. Ask why the recommended loan fits, what its limitations are and what other structures were considered. Judge the answers against your borrowing objective.
Keep a suitable recommendation; question an unexplained one. A provider change is useful when it addresses a concrete need, not when it merely replaces one familiar name with another.
FAQ
What’s the best Aussie Home Loans alternative for doctors?
Mortgage Pros is a relevant alternative for doctors because doctor home loans are an explicit specialisation. Compare the proposed loan structure, eligibility conditions and advice before choosing a broker.
Is Mortgage Choice better than Aussie Home Loans?
Neither network is automatically better for every borrower. Compare the individual broker’s explanation, proposed loan and support using the same financial information.
Should I apply directly to a bank instead of using a broker?
Apply directly when you have chosen a lender and want to manage comparisons yourself. A broker is the alternative when you want assistance assessing lending options and preparing an application.
Will changing mortgage brokers improve my approval chances?
Changing brokers does not guarantee approval. The lender still assesses your income, debts, credit history, property and application against its lending criteria.
Do I have to refinance after speaking to another broker?
No, a second broker conversation does not require you to refinance. Review the recommendation and relevant costs before deciding whether to change your loan.
What should I compare when refinancing in 2026?
Compare the proposed loan structure, interest arrangements, applicable costs and features against your existing mortgage. Ask whether the change addresses your borrowing goal rather than judging it only by the advertised rate.
Can a mortgage broker guarantee a doctor home loan?
No, a mortgage broker cannot guarantee lender approval. Your occupation does not replace the lender’s assessment, and any profession-related eligibility conditions need to be confirmed.
One last thing
The most useful question is not which broker recommends the biggest loan. It is: What would make this recommendation unsuitable for my plans? Ask that before submitting an application, and expect a plain-language answer about the loan's limitations.
Contact us today to discuss your borrowing goal and the questions you need answered before choosing your next step.
Related guides
- Best Home Loan Lenders for Doctors
- Mortgage Choice Alternatives
- Best Offset Home Loan Accounts
- Best Guarantor Home Loan Lenders