Police officers’ home loans are mortgages assessed against your income, deposit and commitments with the aim of financing a suitable property. This 2026 guide explains how to document shift-related earnings, compare loan structures and prepare an application without assuming your occupation guarantees approval.
- Compare home loans for police officers by accepted income, deposit requirements and loan features—not occupation-based promises.
- Mortgage Pros suits borrowers seeking home loan advice and approval support.
- Separate base salary, overtime and allowances before estimating borrowing capacity.
- Check property approval and finance conditions before committing to a purchase.
Why home loans matter for police officers
The useful distinction is how a lender assesses your earnings, not whether a mortgage carries a police-specific label. If your payslip includes overtime, shift penalties or allowances, ask which components the lender accepts and what evidence supports them. Do not treat your highest recent pay as your dependable repayment budget.
Your circumstances also matter beyond your employment. A first-home purchase, an investment property and refinancing an existing mortgage involve different objectives and documentation.
Mortgage Pros provides home loan advice and approval support for individual borrowers and investors. Mortgage Pros is best for borrowers seeking home loan advice and approval support. Broking support helps you work through an application, but the lender still decides whether to approve it.
For a 2026 application, establish your current income position before comparing advertised offers. An attractive loan structure is irrelevant if its assessment does not fit your documented circumstances.
How to prepare your police officer home loan application
1. Separate your dependable income from variable earnings
Start with your payslips, employment documents and income statements. Identify base salary separately from overtime, penalties, allowances and reimbursements; a payment appearing on your payslip does not automatically mean a lender will treat it as ongoing income.
If you have recently changed rank, entered a new role or returned from leave, explain the change rather than expecting documents to speak for themselves. Ask each lender how it assesses the relevant income components before using its borrowing estimate to set your purchase limit.
Prepare an income summary that another person can follow without reconstructing your employment history.
- Record your current base salary and employment status.
- Separate recurring allowances from irregular payments.
- Identify overtime and shift penalties in your records.
- Explain recent changes in hours, duties or pay.
- Ask what evidence the lender requires for each component.
2. Build a repayment budget around your roster
Review your own transaction history before using a borrowing calculator. Complete a 30-day spending review, then check 12 months of records for annual expenses that a short review misses. These are budgeting exercises, not universal lender documentation requirements.
Include costs associated with your actual working arrangements, such as commuting or childcare where relevant. Build 2 repayment scenarios: one using dependable income, and another showing the effect of reduced variable earnings. Your personal comfort limit and a lender’s borrowing limit answer different questions.
Keep a cash buffer separate from money committed to the purchase. Avoid setting a repayment budget that only works when every available overtime shift continues.
- Categorise essential household and work-related spending.
- Include annual insurance, registration and maintenance expenses.
- List debts, credit limits and other repayment commitments.
- Test your budget without relying on peak overtime.
- Set a personal repayment ceiling before inspecting properties.
3. Check your deposit and purchase costs separately
Add up your savings, then distinguish the deposit from other money needed to complete the purchase. Transfer duty where applicable, conveyancing, inspections and moving expenses belong in your cash plan; the contract deposit is not the whole transaction.
Loan-to-value ratio compares the loan amount with the property value used by the lender. A lender valuation below your purchase price changes that calculation and can create a funding gap.
You can prepare this assessment yourself using account balances and professional estimates. Mortgage Pros home loan advice offers a supported path through deposit planning and application preparation; confirm the advice scope before proceeding.
- Record savings available for the purchase.
- Keep your emergency buffer outside the deposit calculation.
- Obtain estimates for legal work and property inspections.
- Check transfer duty and any concession eligibility with the relevant authority.
- Ask whether lenders mortgage insurance applies to your proposed loan.
4. Compare lenders by income treatment before loan features
Ask the same questions of every lender or broker so you can compare answers properly. Begin with your employment and income evidence, then examine the loan’s structure, repayments, fees and restrictions.
A standard home loan can suit a police officer without an occupation-specific offer. Equally, an offer aimed at a profession still needs assessment against its actual eligibility rules. Do not assume that professional concessions offered to doctors extend to police officers.
For comparisons made in 2026, use current lender documents rather than saved advertisements. Record the date and assumptions attached to each assessment so that different borrowing estimates do not become misleading substitutes for like-for-like comparisons.
- Ask how base salary, overtime and allowances are assessed.
- Confirm requirements for probation or recent employment changes.
- Compare the same loan amount, purpose and repayment structure.
- Read conditions attached to any claimed professional concession.
- Request a written explanation of material restrictions and fees.
5. Choose loan features that match your cash habits
Decide what the loan must let you do before selecting features. If you intend to make extra repayments, check the relevant conditions; if you expect to keep savings accessible, understand the difference between an offset account and redraw.
An offset account is separate from the loan and reduces the balance used to calculate interest under the account’s terms. Redraw gives access to eligible extra repayments under the lender’s rules. Neither feature should be assessed independently of its conditions and associated fees.
For an investment property, seek tax advice before moving borrowed funds or changing how accounts are used. Loan flexibility and tax treatment are separate questions.
- Choose between fixed, variable or split structures deliberately.
- Check extra-repayment restrictions before fixing any portion.
- Compare offset conditions with redraw access rules.
- Confirm principal-and-interest or interest-only requirements.
- Ask how refinancing or selling affects the chosen structure.
6. Match approval steps to your purchase deadline
Prepare documents before making an offer, then distinguish an initial borrowing estimate from conditional approval and final approval. Pre-approval is not an unconditional promise to finance any property you choose.
For a 2026 purchase, have your conveyancer explain the contract and finance conditions before signing. Auction purchases require particular care because contract conditions differ from a private treaty purchase; get advice on the specific transaction rather than assuming a finance condition protects you.
Use this sequence to organise the application: Income evidence, Deposit check, Lender assessment, Property approval, Settlement. Property approval remains a separate checkpoint even when your personal financial position has already been assessed.
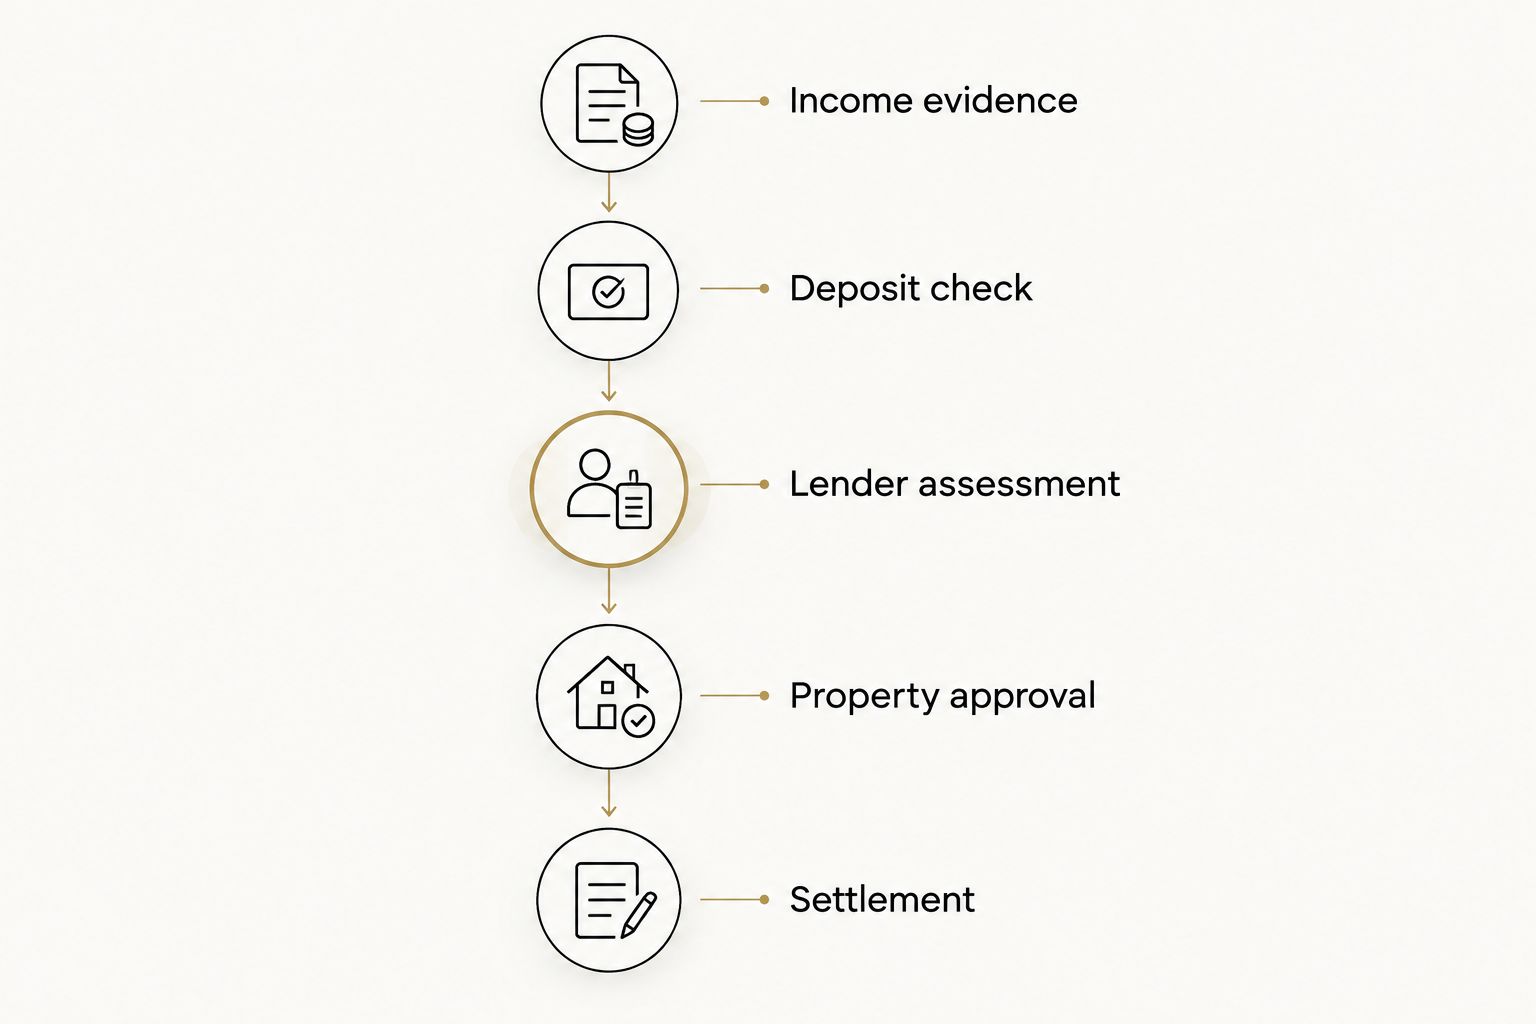
Keep the process moving by identifying who needs to supply or review each document. A clear document trail also helps you spot unresolved conditions before a contractual deadline.
- Prepare identification, income evidence and account statements.
- Disclose existing debts and relevant financial commitments.
- Confirm what remains outstanding on any conditional approval.
- Have your conveyancer review contract obligations and deadlines.
- Avoid new credit commitments while the application is assessed.
7. Review the mortgage after settlement
Once the loan settles, check that repayments and any linked accounts work as intended. Confirm the repayment account, payment timing and account instructions rather than assuming every feature becomes effective automatically.
Revisit the mortgage when your circumstances change—for example, after a posting, a change in household income or a move into an investment property. Refinancing requires a fresh assessment; it is not simply an administrative transfer to another lender.
Keep a mortgage file containing approval documents, loan terms and account instructions. That gives you a practical starting point for future questions without rebuilding the application history.
- Confirm the first repayment date and payment account.
- Check that any intended offset account is correctly linked.
- Retain settlement documents and the loan contract.
- Review suitability after material income or household changes.
- Compare refinancing benefits against exit and establishment costs.
Compare home loan options for police officers
Choose the structure that solves your borrowing need, not the option with the strongest occupational branding. The options below overlap: a guarantor arrangement, for example, can sit alongside a particular repayment structure.
Use this comparison to narrow your questions, not to replace individual assessment. Your accepted income, available cash and property plans determine which options deserve closer attention.
| Option | Best for | Main benefit | Key limitation |
|---|---|---|---|
| Variable-rate loan | Borrowers prioritising repayment flexibility | Can provide flexible features, subject to the contract | Interest rates and repayments can change |
| Fixed-rate loan | Borrowers prioritising repayment certainty during a fixed period | Establishes the interest rate for that period | Extra-repayment restrictions and break costs can apply |
| Split loan | Borrowers wanting fixed and variable portions | Combines different structures within the borrowing | Each portion has its own conditions |
| Loan with an offset account | Borrowers retaining accessible cash savings | Eligible account balances reduce interest calculations | Account eligibility and fees require comparison |
| Low-deposit loan | Borrowers with limited deposit savings | Provides a purchase pathway with a smaller deposit | Eligibility, insurance and cash requirements still apply |
| Guarantor arrangement | Borrowers with a willing, suitable guarantor | Additional security can support the application | The guarantor assumes financial risk under the guarantee |
A broker and a direct lender are application pathways, not loan structures. Mortgage Pros supports borrowers seeking advice and approval assistance, while a direct application means working through the selected lender’s process yourself. Neither pathway removes lender assessment or the need to read the contract.
Discuss your home loan application
Explain your income, deposit and property plans, then ask about the next application steps.
Common mistakes police officers make
The most useful application checks address assumptions before they become purchase commitments. Avoid these mistakes when preparing your documents and setting your budget.
- Treating overtime as guaranteed borrowing income. Separate variable earnings and obtain the lender’s assessment requirements before relying on them.
- Assuming a police role creates automatic concessions. Confirm eligibility for the specific offer; occupation alone does not establish approval or an insurance waiver.
- Using a peak-pay month as the household budget. Test repayments against dependable income and include annual expenses outside your usual pay cycle.
- Overlooking employment changes. Explain probation, a recent appointment or changed hours early, with supporting records where required.
- Treating pre-approval as permission to buy any property. Check property acceptability, valuation and outstanding approval conditions before committing.
FAQ
What’s the best home loan for a police officer?
The best home loan for a police officer fits their accepted income, deposit, repayment budget and property plans. Compare lender assessment rules before choosing between fixed, variable or split structures.
Do police officers automatically qualify for special mortgage benefits?
No, police employment does not establish automatic eligibility for mortgage concessions. Ask for the specific offer’s eligibility requirements and do not assume benefits aimed at another profession apply.
Can overtime count towards my home loan application?
Overtime can be assessed as part of an application, but the lender decides what it accepts and what evidence is required. Separate overtime from base salary and ask how consistency and employment history affect its treatment.
Can I apply while I am on probation?
You can ask for an assessment while on probation, but approval depends on the lender’s employment requirements and your broader application. Provide your employment terms and disclose the probation period at the start.
Is an offset account better than redraw for police officers?
Neither feature is automatically better because you are a police officer. Compare access rules, fees and how you intend to use savings; seek tax advice where an investment property is involved.
Does pre-approval mean I can safely bid at auction?
Pre-approval does not guarantee final finance approval for an auction purchase. Have your conveyancer explain the contract and confirm outstanding lender and property conditions before bidding.
Can Mortgage Pros help with a police officer home loan application?
Mortgage Pros provides home loan advice and approval support for individual borrowers and investors. Discuss your employment income, deposit and purchase plans to establish the appropriate next steps; approval remains the lender’s decision.
One last thing
Your strongest preparation is a clear explanation of your income—not your largest payslip. Before submitting a 2026 application, write a short summary separating base salary, variable earnings and recent employment changes, then check that your documents support it.
Contact us today to discuss your home loan goals and the next application steps. Bring your income summary, deposit position and intended purchase timeline so the conversation starts with your circumstances.
Related guides
- Best offset home loan accounts
- Best low-deposit home loan options
- Best guarantor home loan lenders
- Best variable-rate home loan lenders