Best overall approach: choose a lender whose policy matches your medical income. Best for hospital employees: a lender that assesses regular variable pay. Best for private practitioners: a lender that assesses self-employed income. This 2026 guide explains how to shortlist the best home loan lenders for medical professionals; Mortgage Pros provides mortgage broking advice, not lending.
- Choose the best home loan lenders for medical professionals by income assessment, eligibility and loan structure—not brand recognition.
- Mortgage Pros specialises in doctor home loans, including support for dentists and surgeons.
- Hospital employees, private practitioners and locums need different lender-policy checks.
- Confirm any lenders mortgage insurance concession before relying on it in your deposit plan.
Why this matters
A doctor's salary, a dentist's practice earnings and a locum's contract income require different evidence. A lender that suits one medical borrower is not automatically the right choice for another.
The best medical home loan is one you qualify for, can service comfortably and can manage as your circumstances change. Start with those tests before comparing optional features or a familiar bank name.
Mortgage Pros is best for doctors, dentists and surgeons seeking specialist home loan advice. The lender shortlist should follow your circumstances—not substitute for assessing them.
What makes the best medical home loan lender?
Use these six criteria to assess a 2026 shortlist:
- Occupation eligibility: Does the lender recognise your exact profession and registration status for any professional lending concession?
- Income assessment: How does the lender assess salary, overtime, on-call payments, contracts and practice earnings?
- Deposit requirements: What deposit, security and supporting evidence does your application require?
- Repayment suitability: Do repayments fit your household budget, existing commitments and income variability?
- Useful features: Do offset, redraw, repayment flexibility or split lending serve a clear purpose?
- Application evidence: Can you supply the documents needed for the lender to assess your circumstances?
No single criterion settles the decision. A concession has little practical value if the lender's income assessment does not support the borrowing you need.
Medical home loan lender profiles at a glance
These are ranked lender profiles, not endorsements of named banks or claims about current offers. Each profile addresses a different borrowing situation; your occupation alone does not determine the result.
| Lender profile | Best for | Standout selection criterion | Key limitation |
|---|---|---|---|
| Medical-professional policy fit | Eligible borrowers comparing professional concessions | Written confirmation that your occupation and application qualify | A concession does not establish borrowing capacity |
| PAYG variable-income fit | Hospital employees receiving overtime or on-call pay | Assessment of documented recurring employment income | Not every income component receives identical treatment |
| Self-employed income fit | Dentists and doctors operating private practices | Assessment of personal income alongside business financials | Business turnover is not personal disposable income |
| Contract-income fit | Locum doctors and contractors | Assessment of contracts and income continuity | Gaps and changing arrangements need explanation |
| Refinance structure fit | Existing borrowers reviewing their mortgage | Suitability of the replacement loan and switching decision | Switching can introduce costs and disrupt useful features |
1. Medical-professional policy fit: best for concession checks
Start here if a professional lending concession is central to your buying plan. Ask the lender to confirm your exact occupation, registration, employment arrangement and proposed loan against its current criteria.
Do not treat “medical professional” as a universal eligibility category. A doctor, dentist, nurse and pharmacist should each have their own eligibility checked rather than relying on another profession's experience.
Medical-professional policy fit pros:
- Focuses the shortlist on your actual professional status.
- Identifies whether a concession applies to your proposed borrowing.
- Separates deposit questions from the repayment assessment.
Medical-professional policy fit cons:
- Eligibility remains subject to the lender's full assessment.
- A professional concession does not remove ordinary application requirements.
Best for: Eligible medical borrowers who need to establish whether professional lending terms apply.
For your 2026 application, ask for the concession and its conditions to be explained before you organise your purchase around it. Verdict: Buy into this approach when eligibility is confirmed; skip assumptions based on your job title.
2. PAYG variable-income fit: best for hospital employees
A hospital employee's payslip can contain more than base salary. This lender profile prioritises how recurring overtime, shift allowances and on-call payments are assessed alongside ordinary earnings.
Prepare evidence that explains each income component. Payslips, employment information and income history help distinguish recurring earnings from an isolated payment; the lender decides what it accepts.
PAYG variable-income fit pros:
- Makes the assessment of variable earnings explicit.
- Keeps base salary separate from additional payments.
- Helps identify evidence needed before an application.
PAYG variable-income fit cons:
- Extra earnings do not automatically increase assessed borrowing capacity.
- A changed roster or employment arrangement needs explanation.
Best for: Salaried hospital doctors and other employed medical professionals whose earnings include regular additional payments.
Ask which income components enter the assessment and what evidence supports them. Do not compare borrowing estimates without checking whether both lenders used the same income assumptions. Verdict: Buy into this profile for recurring hospital income; hold if the assessment depends on payments you cannot document.
3. Self-employed income fit: best for private practitioners
Private-practice borrowers need an assessment that connects business performance with personal income. Practice revenue, business profit, drawings and salary describe different things; they are not interchangeable.
Prepare personal and business financial information relevant to your structure. If you operate through a company or trust, explain how income reaches you and identify business liabilities that affect the assessment.
Self-employed income fit pros:
- Addresses the relationship between business and personal finances.
- Makes ownership structure part of the assessment.
- Encourages early identification of document requirements.
Self-employed income fit cons:
- Preparation involves more than presenting practice turnover.
- Changes in ownership or trading conditions require context.
Best for: Dentists, doctors and surgeons earning through an established private practice.
Choose the assessment approach before choosing the loan features. A convenient offset account cannot compensate for an income calculation that does not support the application. Verdict: Buy into this profile when practice earnings fund repayments; skip comparisons based on turnover alone.
4. Contract-income fit: best for locum doctors
Locum and contract borrowers need to explain both current work and income continuity. A contract records an engagement, but the lender also needs to understand the wider employment or business arrangement.
Organise contracts, payment evidence and work history so the sequence is clear. Identify whether you receive wages or invoice through a business, because that distinction affects the documents needed.
Contract-income fit pros:
- Focuses on the evidence behind contract earnings.
- Brings gaps and changes in work into the discussion early.
- Distinguishes employee arrangements from self-employment.
Contract-income fit cons:
- A current contract does not guarantee approval.
- Different payment structures complicate direct lender comparisons.
Best for: Locum doctors and medical contractors whose earnings do not follow a conventional permanent salary arrangement.
Ask how the lender will assess your work history before submitting the full application. Verdict: Buy into this profile for contract-based work; hold until the income evidence tells a consistent story.
5. Refinance structure fit: best for existing borrowers
An existing medical borrower needs a replacement loan that improves the overall arrangement, not simply a different lender. Compare the proposed mortgage with your current loan, including remaining term, features and switching implications.
If your employment or practice structure has changed since approval, explain the change before relying on a refinance estimate. The replacement lender conducts its own assessment.
Refinance structure fit pros:
- Tests whether switching serves a specific objective.
- Includes loan term and features in the decision.
- Prompts a fresh review of income and commitments.
Refinance structure fit cons:
- Switching involves application work and associated costs.
- Extending the repayment term can increase total interest paid.
Best for: Medical professionals reviewing an existing owner-occupier or investment mortgage.
A 2026 refinance comparison should explain what improves and what you give up. Verdict: Buy into refinancing only when the overall case supports switching; hold when the benefit is unclear.
How to turn the shortlist into an application
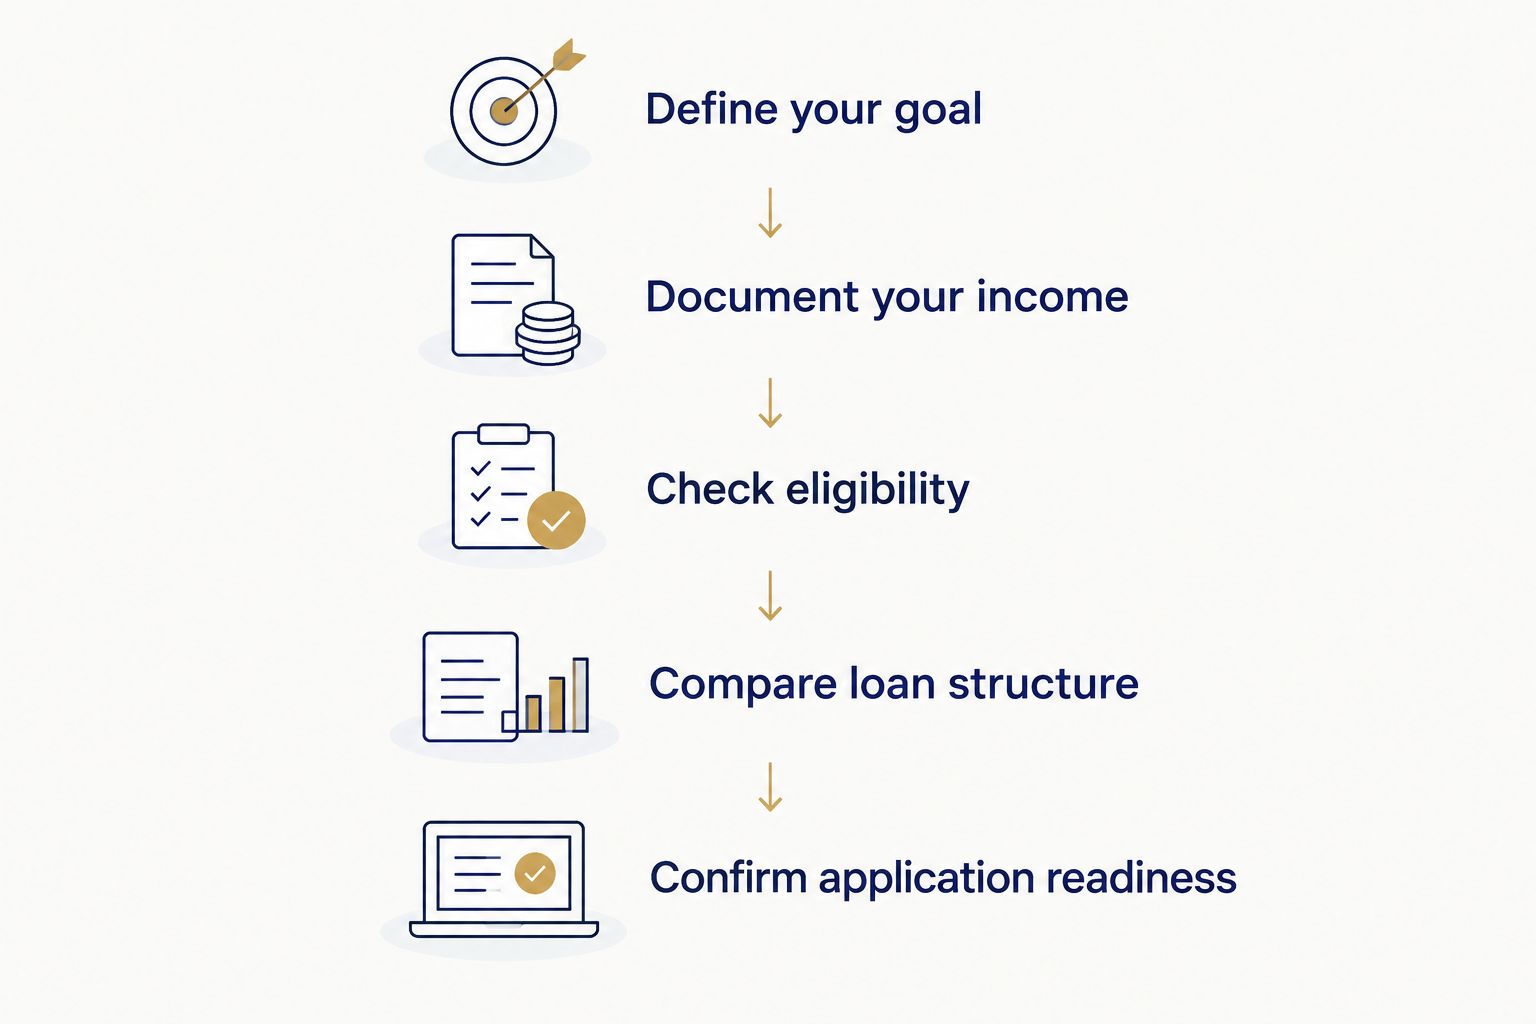
Use the following sequence before authorising an application. It keeps policy eligibility, income assessment and property requirements in the same decision rather than treating them as separate surprises.
- Define your goal: State whether you are buying, refinancing or accessing equity, and identify the intended property use.
- Document your income: Separate salary, variable pay, contracts and business earnings, with evidence for each source.
- Check eligibility: Confirm occupation requirements, deposit expectations and any professional concession conditions.
- Compare loan structure: Review repayments, term, offset or redraw needs, and switching implications where relevant.
- Confirm application readiness: Check outstanding documents and approval conditions before proceeding.
Ask Mortgage Pros to assess your circumstances against suitable lending options. Bring a clear summary of your occupation, income sources, deposit and existing debts so the discussion starts with the facts that determine suitability.
Discuss your medical home loan
Ask about lender suitability for your profession, income arrangement and borrowing goal.
Three figures to understand before choosing
An 80% loan-to-value ratio means the loan equals 80% of the lender's assessed property value. Loan-to-value ratio, or LVR, describes the relationship between debt and security; it does not measure whether repayments fit your income.
At that LVR, the remaining 20% of the assessed value is outside the loan. That does not mean your total cash requirement ends there: purchase expenses and a difference between price and valuation also affect the calculation.
A 100% offset account uses the full eligible account balance to offset the linked loan balance when calculating interest. Check the account's actual terms and whether its benefits suit how you manage cash.
None of these figures establishes eligibility for a medical-professional concession. Keep the deposit calculation, loan features and lender approval assessment separate.
How the lender profiles are ranked
The order prioritises eligibility and income assessment before loan features. Professional-policy checks come first, followed by distinct employment arrangements, then the separate decision facing existing borrowers.
This is a suitability framework, not a claim that one bank approves every doctor or offers the best terms to every profession. For a 2026 decision, compare current written information for your actual application.
Which medical home loan lender should you choose?
Choose the lender that accepts your documented income, fits your deposit position and supports a manageable loan structure. If you are undecided, start with occupation eligibility and income assessment; those checks determine which options deserve further comparison.
For doctors, dentists and surgeons, Mortgage Pros provides a specialist advice starting point. Ask for the reasons behind the recommendation, the relevant conditions and the alternatives considered—not just a lender's name.
FAQ
What’s the best home loan lender for medical professionals?
The best lender is the one whose eligibility rules, income assessment and loan structure suit your application. Compare your documented circumstances rather than assuming one bank suits every medical profession.
Is Mortgage Pros a bank or a mortgage broker?
Mortgage Pros is a mortgage broking firm, not a bank. It helps borrowers with home loan advice and approval support, with a particular focus on doctors, dentists and surgeons.
Can medical professionals get a home loan without lenders mortgage insurance?
Eligibility for a lenders mortgage insurance concession depends on the lender and the application. Confirm your exact occupation, registration and proposed borrowing before relying on a concession.
Will a lender count my overtime and on-call pay?
The lender decides how to assess overtime and on-call pay. Provide evidence of the payments and ask which components are included in its borrowing assessment.
How do lenders assess a self-employed dentist’s income?
Lenders assess self-employed income using financial evidence relevant to the borrower’s business and ownership structure. Practice turnover alone does not establish personal income available for repayments.
Can a locum doctor apply for a home loan?
A locum doctor can apply for a home loan, subject to lender assessment. Contracts, payment evidence and work history help explain income continuity and the employment or business arrangement.
Should I refinance into a doctor home loan in 2026?
Refinance only when the replacement loan suits your circumstances and the overall switching case is sound. Compare loan features, remaining term, associated costs and current eligibility before deciding.
One last thing
Ask what happens if the property valuation is below the purchase price. Your occupation does not remove that risk, and a valuation difference changes the deposit calculation even when your income assessment is satisfactory.
Before committing to a purchase, contact us today to discuss your medical home loan circumstances and the checks needed for your application.
Related guides
- Best home loan lenders for doctors
- Best home loan lenders for surgeons
- Best home loan lenders for dentists