Yes, you can refinance before your fixed rate term ends in Australia, provided the replacement lender approves your application and your existing loan is paid out under its contract. Your current lender can charge a break cost, so the decision in 2026 depends on whether the benefits outweigh that charge and the other switching costs—not simply whether another loan has a lower interest rate.
- Can I refinance before my fixed rate term ends? Yes, but approval and the economics of switching both matter.
- Request a dated break-cost quote before comparing early refinancing with waiting until your fixed term expires.
- Compare the same loan balance and remaining term; lower repayments alone do not prove savings.
- Mortgage Pros provides home loan refinancing advice for borrowers who want help assessing their next move.
Can I refinance before my fixed rate term ends?
You do not have to wait until your fixed rate expires to refinance. However, leaving early means settling the existing loan according to its terms, including any applicable break cost. Approval for the replacement loan is a separate requirement.
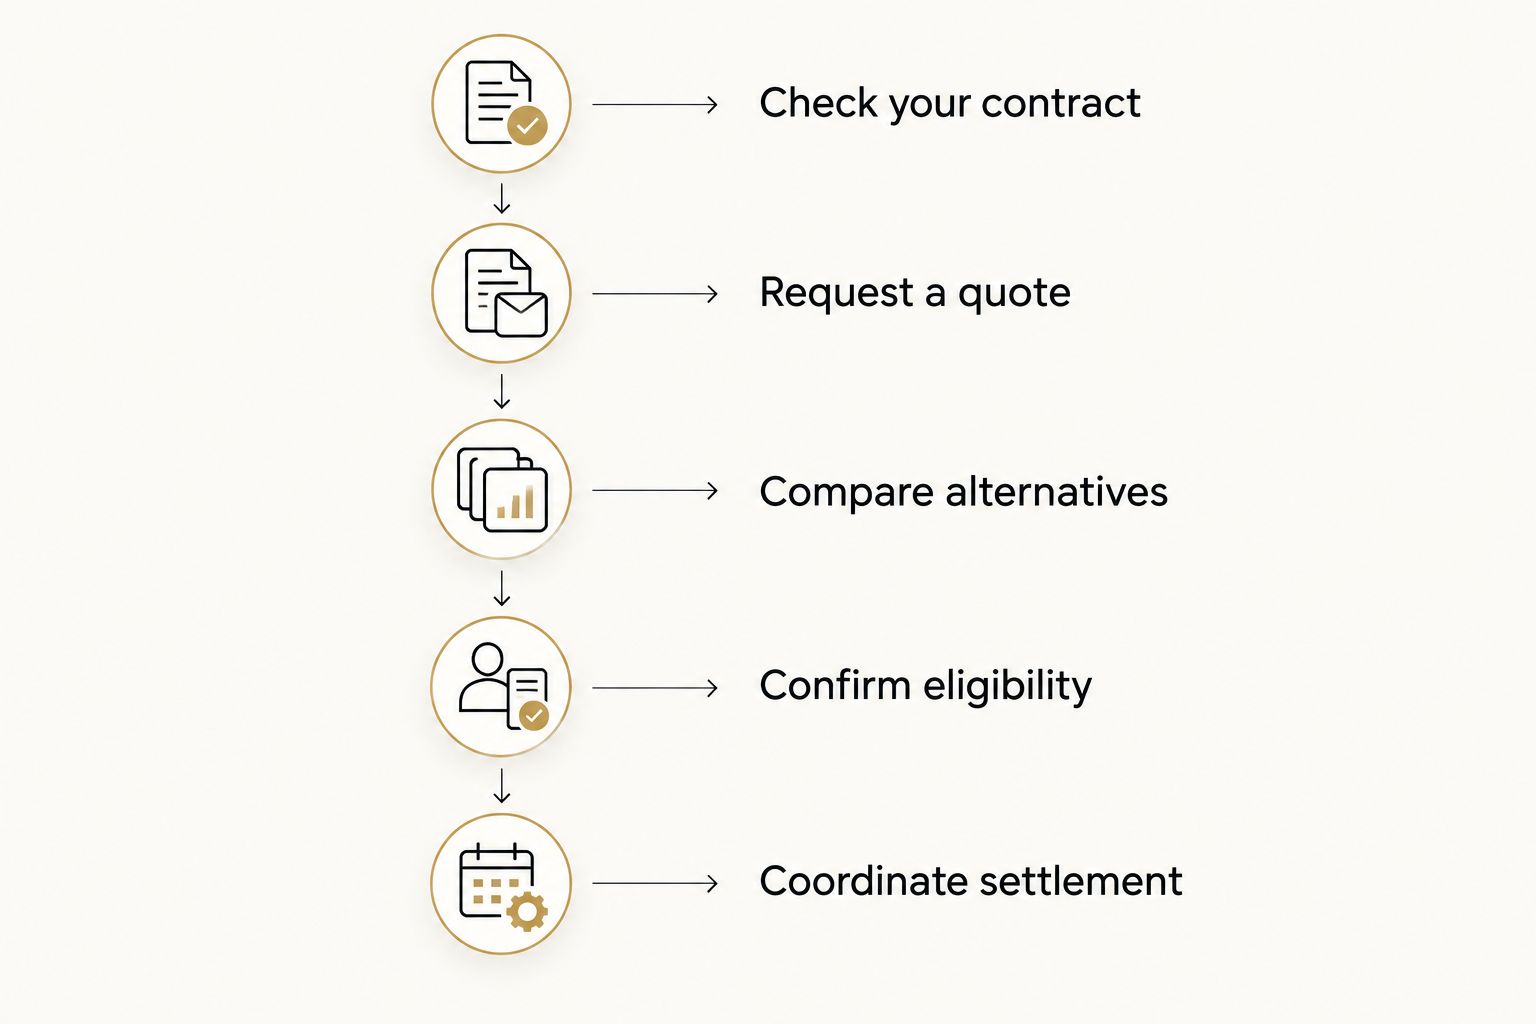
Use this sequence before committing to a switch:
- Check your contract. Confirm the fixed expiry date, outstanding balance, repayment conditions and any separate loan splits.
- Request a quote. Ask your existing lender for a written payout estimate that identifies the break cost and other discharge charges separately.
- Compare alternatives. Assess refinancing now, waiting until expiry and discussing an internal change with your existing lender.
- Confirm eligibility. Have the replacement lender assess your income, commitments, property and proposed borrowing.
- Coordinate settlement. Confirm the final payout amount and settlement date before the old loan is discharged.
For the broader financial decision, read is refinancing worth it?. This page focuses on the extra decision created by leaving a fixed term early.
Why this matters
A lower advertised interest rate does not establish that refinancing early will leave you better off. You need to account for the cost of leaving, the replacement loan's conditions and how long you expect to keep it.
For a 2026 refinancing decision, compare two timelines: switching now and keeping your current loan until its fixed expiry. The existing fixed rate only applies until that expiry date, so do not assume it continues throughout a long-term savings calculation.
Compare the whole transaction, not just the repayment shown on a calculator. That includes any costs added to the new balance, because borrowed switching costs also attract interest.
Refinance now, wait or speak to your current lender?
The right route depends on your objective and the written figures available for your loan. Each option has a benefit and a limitation.
| Option | Best for | Main benefit | Main limitation |
|---|---|---|---|
| Refinance before expiry | Borrowers whose verified benefits outweigh early-exit and switching costs | Changes the loan before the fixed term ends | Can trigger a break cost and requires a fresh lending assessment |
| Wait until expiry | Borrowers who do not need an immediate change and cannot justify breaking early | Avoids ending the fixed arrangement prematurely | Keeps the existing fixed conditions until expiry; the next rate still needs review |
| Discuss an internal change | Borrowers who want to check what their current lender permits | Establishes whether an external refinance is necessary | A product change can still trigger break costs and does not compare other lenders |
Ask your existing lender what happens automatically when the fixed period ends. Check the proposed replacement rate and repayment arrangement rather than assuming the loan closes or remains fixed.
Do not break a fixed loan just to secure a lower headline rate. Establish the net benefit first, then decide whether that benefit supports the disruption and expense of switching.
What is a fixed rate break cost?
A break cost is a contractual charge that can apply when you end or alter a fixed rate arrangement early. It is different from an ordinary discharge administration charge.
The calculation depends on the lender's contract and methodology. It can reflect changes in relevant funding or wholesale interest rates, the fixed balance and the time left in the fixed period; it is not simply the interest remaining on your repayment schedule.
Ask for the following in writing:
- The break-cost estimate for your proposed settlement date.
- The date until which the estimate applies.
- The other charges included in the total payout.
- The events that require a revised quote.
- Whether a partial repayment or internal product change would trigger the charge.
A break-cost quote is date-sensitive, not a permanent figure. If settlement moves, ask whether the amount needs updating before relying on the earlier estimate.
Why the cost and outcome vary
There is no universal answer to whether breaking a fixed loan is worthwhile in 2026. These factors determine the comparison:
- Contract terms: Your loan agreement determines which changes trigger a break cost and how the lender calculates it.
- Remaining fixed period: The time left affects both the lender's calculation and the period over which you compare staying with switching.
- Outstanding fixed balance: The amount being repaid or changed forms part of the early-exit assessment.
- Relevant market-rate movements: Changes in the rates used by the lender's calculation affect the break-cost quote.
- Replacement loan structure: The new term, repayment type, fees and features determine whether the proposed change meets your needs.
- Property and borrower assessment: The valuation, equity, income and liabilities affect approval and the conditions available to you.
Your current loan's repayment history does not replace a new lender's assessment. A change in employment, income or commitments needs to be considered before you commit to a discharge.
How do I compare the financial benefit of switching early?
Use the same loan balance and remaining repayment term for the initial comparison. Otherwise, a lower monthly repayment can simply reflect paying the debt back over a longer period.
Build the comparison in this order:
- Record the current balance, fixed expiry date and remaining loan term.
- Obtain the break-cost quote and identify the other switching charges.
- Calculate the replacement loan's repayments using the same remaining term.
- Compare interest and applicable fees over a clearly stated period.
- Include interest on switching costs if you intend to add them to the new loan.
- Test what happens if you sell, refinance again or repay early.
A simple break-even calculation divides total switching costs by the ongoing monthly saving. That shortcut only works when the saving is reasonably consistent and the comparison includes the relevant costs.
If your fixed term expires before the calculated break-even date, revisit the assumptions. The comparison after expiry must use an explicitly stated rate assumption, not pretend the old fixed rate continues.
For a 2026 assessment involving a variable replacement loan, test repayment affordability if its rate rises. An initial saving does not remove exposure to future rate changes.
Can I refinance only the variable part of a split loan?
A variable split does not automatically make part of the loan independently transferable. Ask how the lender's security arrangements connect the splits and what must be discharged when another lender takes over.
If replacing the variable portion also requires paying out the fixed portion, the transaction can still trigger a break cost. Confirm the proposed structure with both lenders before treating it as a way around the fixed contract.
Start by listing every split, its balance, rate type and expiry date. Also identify any other property securing the borrowing, because the refinance needs to address the security arrangement as well as the individual loan accounts.
Can I refinance before my fixed term ends without a break cost?
Refinancing early does not always produce a break cost, but only your lender's current calculation confirms the amount. Do not assume there is no charge because the fixed period is nearly over or because retail interest rates have risen.
Ask whether other discharge or switching charges still apply even if the break-cost component is nil. Keep the lender's written response with the proposed settlement date so the comparison remains tied to the actual transaction.
Waiting until the fixed arrangement expires avoids ending that arrangement early. It does not automatically remove the other expenses associated with changing lenders.
What should doctors check before refinancing a fixed loan?
If you are a doctor, dentist or surgeon, check how the replacement lender assesses your actual income structure. Hospital salary, overtime, on-call payments, locum earnings and private-practice income need to be presented accurately rather than treated as interchangeable.
Also check whether any profession-based conditions on your existing loan would carry across to the replacement arrangement. Do not assume that an existing lenders mortgage insurance waiver or other concession transfers automatically.
Mortgage Pros is best suited to medical borrowers seeking home loan advice on refinancing and approval. Mortgage Pros specialises in home loans for doctors, dentists and surgeons; that specialisation does not remove lender approval requirements or contractual break costs.
Have your current loan statement, fixed expiry date, income documents and written break-cost quote ready for the discussion. If your income has changed since the original application, explain the change before selecting a replacement loan.
Review your refinancing options
Discuss your fixed expiry, break-cost quote and borrowing needs before deciding whether to switch.
What should I do if my fixed term is almost over?
Prepare before expiry, but separate preparation from settlement. You can gather documents and compare options without instructing your lender to discharge the fixed loan immediately.
Ask your broker or replacement lender how approval conditions, document expiry and settlement timing affect the application. A proposed settlement after the fixed expiry needs to be coordinated; submitting an application does not determine when the old loan ends.
Before a planned 2026 settlement, confirm the precise date on which the fixed arrangement finishes and obtain an updated payout figure. Do not rely on a remembered month or an approximate anniversary.
If you decide to stay temporarily, check the rate and repayment that will apply after expiry. Waiting should be an informed choice, not the result of overlooking the lender's expiry notice.
FAQ
Can I refinance before my fixed rate term ends in Australia?
Yes, you can refinance before your fixed rate term ends if the replacement lender approves the application and the existing loan is paid out under its contract. Obtain a written break-cost quote before deciding whether switching early is worthwhile.
Will I definitely pay a break cost if I refinance early?
No, an early refinance does not always produce a break cost. Your lender’s current calculation determines the amount, and other discharge or switching charges can still apply.
Is refinancing with my current lender a way to avoid break costs?
An internal refinance does not automatically avoid break costs. Ask whether the proposed change ends or alters the fixed arrangement and request written confirmation of the applicable charges.
Can I apply now but settle after my fixed rate expires?
You can prepare and apply before expiry while requesting settlement after the fixed arrangement ends. Approval conditions, document validity and the discharge process still need to support that timing.
Will a lower repayment mean refinancing saves me money?
A lower repayment does not necessarily mean refinancing saves money. Extending the loan term or adding switching costs to the balance can reduce the immediate repayment while increasing the amount repaid over time.
Can a doctor refinance a fixed home loan after changing jobs?
A doctor can apply to refinance after changing jobs, but approval depends on the replacement lender’s assessment. Provide current employment and income documents, including evidence of variable or private-practice earnings where relevant.
What happens if I do nothing when my fixed rate ends?
What happens at fixed expiry depends on your loan contract and any instructions accepted by your lender. Check the expiry notice for the rate, repayment and arrangement that will apply rather than assuming another fixed period begins.
One last thing
Your break-cost quote and your approval need to work for the same settlement date. An attractive comparison is not enough if the payout figure changes or the replacement loan cannot settle as planned.
Before authorising discharge, confirm the final payout, approved loan conditions and settlement instructions. To discuss that decision with Mortgage Pros, contact us today with your fixed expiry date and latest loan statement.
General information only. Suitability depends on your circumstances, loan contract and lender assessment.
Related guides
- How much does it cost to refinance a home loan?
- Refinancing a doctor home loan to a standard loan
- Can I refinance while on an interest-only loan?