Refinancing is worth it in 2026 when the interest and fee savings exceed the costs of switching, without extending your debt longer than necessary. A lower repayment alone does not prove you are better off: resetting the loan term can increase the total interest you pay. Compare the proposed loan with both your existing loan and a repricing offer from your current lender before deciding.
- Is refinancing worth it? Compare total interest, switching costs and the remaining loan term—not just repayments.
- Mortgage Pros helps Australian borrowers assess home loan refinancing, including doctors with changing income arrangements.
- Ask your existing lender to reprice your loan before committing to a refinance.
- Keep the remaining loan term unchanged when comparing offers so repayment differences mean something.
Why this matters
Your refinance decision should solve a specific problem: unnecessary interest, unsuitable features or a loan structure that no longer matches your circumstances. Replacing a loan without defining that problem makes it harder to judge the result.
For doctors, dentists and surgeons, the review also needs to account for income structure and any profession-specific lending arrangements. Read the guide to refinancing a doctor home loan to a standard loan before assuming a standard replacement loan is the better choice.
Is refinancing worth it in 2026?
Refinancing is worthwhile when the replacement loan improves your overall position after switching costs, ongoing fees and loan-term differences are included. Start with a like-for-like comparison, then assess any changes you actually want to make.
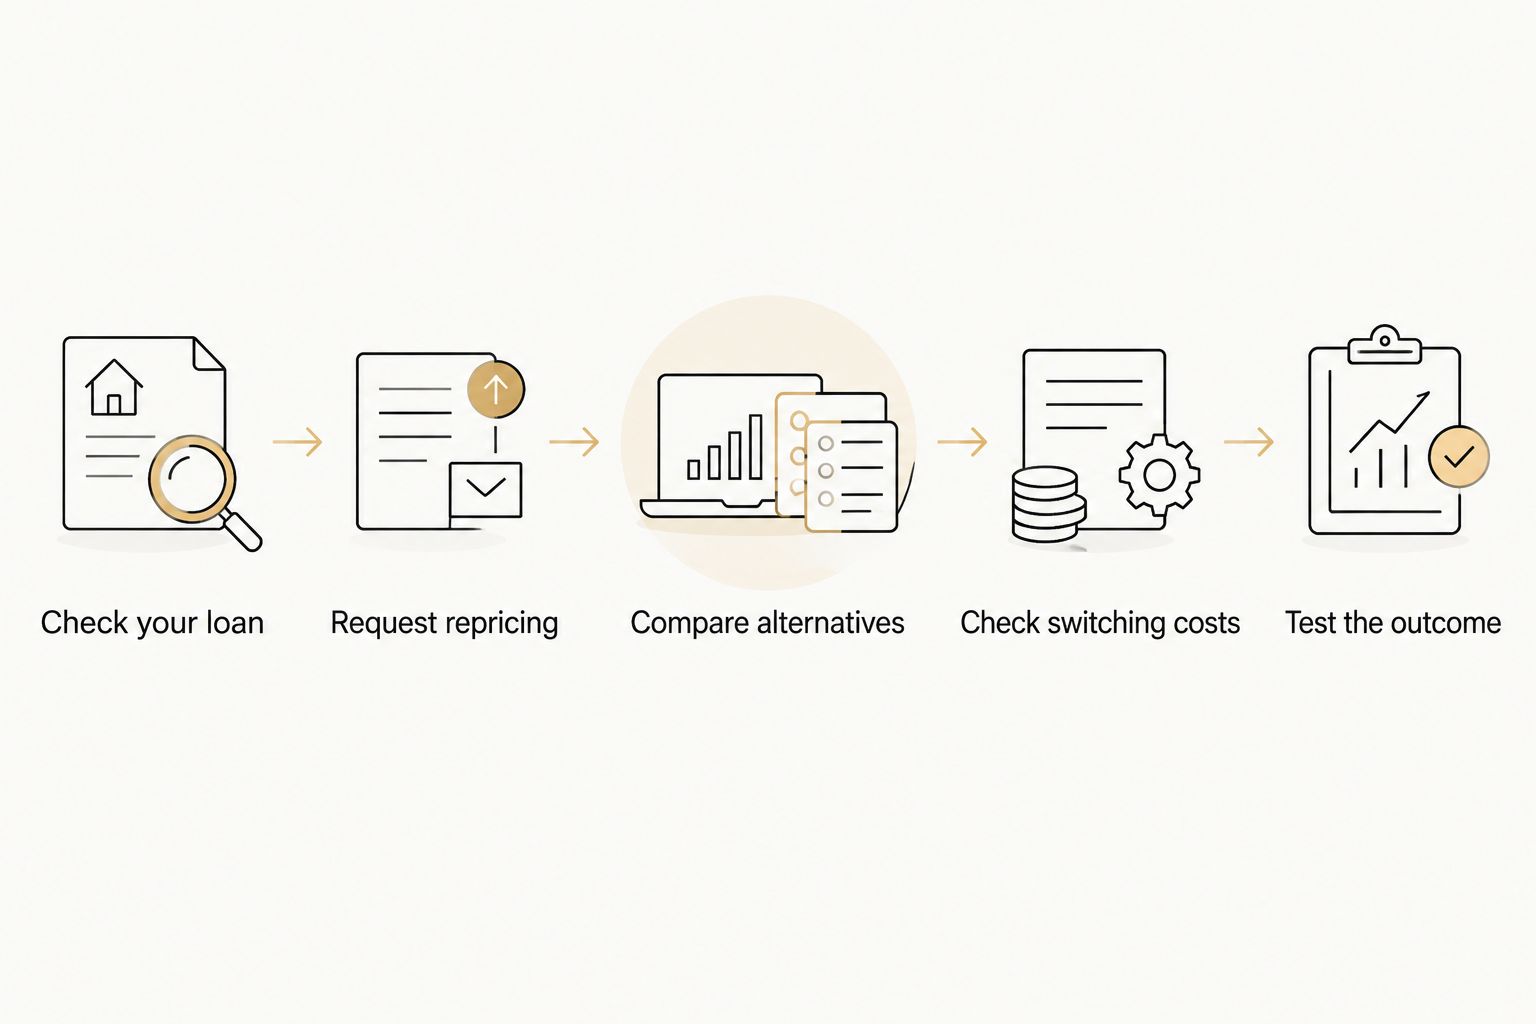
Use this sequence to separate genuine savings from a lower repayment created by a longer term:
- Check your loan. Record your outstanding balance, remaining term, repayment type, interest rate, ongoing fees and offset balance.
- Request repricing. Ask your current lender to review your rate and confirm whether changing it affects your loan features.
- Compare alternatives. Assess a replacement loan using the same balance, remaining term and repayment type.
- Check switching costs. Obtain the applicable discharge, application, registration and settlement charges, plus any fixed-rate break cost.
- Test the outcome. Compare total costs over your expected holding period and check that the proposed repayment suits your budget.
The test is not whether a new lender advertises a lower rate. It is whether the loan offered to you produces a better result on the terms you intend to use.
Compare staying, repricing and refinancing
You have more than a choice between keeping an expensive loan and changing lenders. Repricing deserves its own place in the comparison because it tests whether your current lender will improve the existing arrangement.
| Option | Best for | Main advantage | Main limitation |
|---|---|---|---|
| Keep the existing loan | Borrowers whose current arrangement still meets their needs | Avoids a lender change | Does not address an uncompetitive rate or unsuitable features |
| Reprice with the current lender | Borrowers satisfied with their loan structure | Tests an improvement without replacing the lender | Does not necessarily resolve product limitations |
| Refinance to another lender | Borrowers seeking a better overall loan arrangement | Allows a fresh assessment of rate, features and structure | Requires approval and an assessment of switching costs |
Choose the strongest documented outcome, not the most appealing headline. If repricing achieves your objective without a lender change, refinancing needs an additional benefit to justify the work and expense.
When refinancing for savings makes sense
A savings-led refinance needs a clear baseline. Compare what your current loan would cost over your expected holding period with what the replacement would cost over that same period.
Include interest, ongoing loan fees and switching costs. If you intend to maintain an offset balance, incorporate that balance consistently rather than comparing an offset-adjusted existing loan with an unadjusted replacement.
For your 2026 assessment, request written loan details rather than relying on a search result or an advertised rate. The approved terms determine the value of the refinance.
Calculate your break-even point
A simple starting calculation is:
Break-even period = total switching costs ÷ monthly net saving.
Monthly net saving means the reduction in interest and ongoing fees under comparable loan settings. It is not automatically the difference between the old and new repayments, because those repayments can contain different amounts of principal.
This calculation assumes the monthly saving remains constant. For variable-rate loans, treat it as a starting estimate and reassess if either rate changes. If the proposed loan does not produce a positive net saving, there is no savings-based break-even point.
When refinancing for better features makes sense
Refinancing can be worthwhile even when reducing interest is not your only objective. You might need an offset account, a different repayment structure or a loan arrangement that better separates personal and investment borrowing.
However, a useful feature still needs to justify its associated costs. An offset account has value when you hold money in it; access alone is not a saving.
Ask what you will actually do differently after settlement. If you cannot identify a practical use for a feature, exclude it from the reasons to switch.
For investment borrowing or changes involving redraw, obtain tax advice before moving money. The purpose of borrowed funds matters for interest deductibility; refinancing does not automatically make a private expense deductible.
When staying with your current lender makes sense
Staying is a valid outcome when the existing loan remains suitable or repricing closes the meaningful gap. Refinancing is not a requirement simply because another lender offers a different rate.
A near-term sale also changes the calculation. If switching costs would not be recovered before you sell, a savings-led refinance does not meet its objective.
Fixed-rate borrowers should obtain a current break-cost quote before making a decision. Do not assume a lower replacement rate offsets the cost of leaving the fixed arrangement early.
Wait when you cannot establish the net benefit. Resolve the uncertain costs or loan terms before submitting an application, rather than expecting settlement to reveal whether switching was worthwhile.
Why refinancing value varies
The same advertised loan can produce different outcomes for different borrowers. These factors explain why a refinance that suits another household is not automatically suitable for yours:
- Outstanding balance: A rate difference applies to the balance on which interest is calculated. Compare the actual debt, not the original loan amount.
- Remaining term: Extending repayment over a longer period changes both the scheduled repayment and total interest.
- Switching costs: Exit and establishment charges reduce the benefit of moving lenders. Fixed-rate break costs need separate confirmation.
- Offset use: Savings depend on the money you actually keep in an eligible linked account and the applicable loan terms.
- Equity and valuation: A new lender's valuation affects the loan-to-value ratio and the lending options available to you.
- Income and commitments: Your current earnings, expenses and debts affect approval and borrowing capacity, even if your existing repayments are manageable.
For a 2026 comparison, use current statements and a current assessment of your circumstances. An approval obtained when you bought the property is not evidence that a new lender will approve the refinance today.
Is refinancing worth it for doctors with changing income?
Refinancing is worth assessing when a doctor's income or employment structure changes, but the replacement loan must still pass the same cost-and-suitability test. Moving from hospital employment into locum work or private practice changes the evidence a lender needs to assess.
Separate your base salary, overtime, on-call payments and self-employed earnings before comparing lenders. Provide documents that show the source and continuity of each income component rather than assuming every payment will be treated alike.
If your existing loan includes profession-specific arrangements, establish whether the replacement preserves the benefits you need. A lower rate is not enough if the new structure introduces an expense or restriction that outweighs the saving.
Mortgage Pros is suited to doctors seeking mortgage broking advice on home loan refinancing. The value is help assessing the loan and approval requirements; the limitation is that advice does not replace lender approval or establish savings before the actual terms are compared.
Will refinancing lower my repayments?
Refinancing lowers scheduled repayments when the new rate, term and repayment structure produce a smaller required payment. That does not necessarily mean the debt becomes cheaper overall.
A longer replacement term spreads principal repayments further into the future. You can therefore receive a lower monthly repayment while taking longer to repay the balance and paying more total interest.
For your 2026 review, request a comparison using your existing remaining term first. Assess a longer term separately if cash-flow relief is your objective, and make the extra repayment time an explicit part of the decision.
Can I refinance before my fixed rate ends?
You can apply to refinance before a fixed rate ends, but approval and any break cost determine whether switching is practical. Obtain the break-cost quote before treating a replacement loan as a saving.
Ask how long the quote remains valid and what other discharge requirements apply. If you decide to wait until the fixed period ends, review the proposed follow-on arrangements rather than assuming they will meet your needs.
What should you prepare before applying?
Prepare a clear picture of your current loan and household finances before authorising an application. This helps distinguish an attractive loan from one you can obtain and use effectively.
Gather:
- Your latest loan statement and current repayment details.
- Details of offset accounts, redraw and any fixed-rate portion.
- Income evidence appropriate to your employment or business structure.
- Information about credit cards, personal loans and other commitments.
- Your regular living expenses and any expected financial changes.
- Your reason for refinancing and expected plans for the property.
Ask for the proposed balance, remaining term, repayment type, features and applicable costs in writing. Confirm whether any fees are being added to the loan: financing a fee does not remove it from the comparison.
You can contact Mortgage Pros to discuss your refinancing objective and the information needed for an assessment. Ask for the existing loan, repricing option and proposed refinance to be compared on consistent terms.
Review your refinancing options today
Discuss your existing loan, refinancing goals and the documents needed for an assessment.
FAQ
Is refinancing worth it in 2026 if my repayments are affordable?
Refinancing is worth assessing in 2026 even if your repayments are affordable, because affordability does not establish whether the loan remains suitable. Compare net savings and useful features against switching costs before deciding.
Should I ask my bank for a better rate before refinancing?
Yes, request repricing before committing to refinancing so you can compare the current lender’s revised offer with the replacement loan. Check the features and ongoing fees as well as the rate.
Does refinancing restart my home loan term?
Refinancing does not require you to restart with a longer loan term. Request a replacement term that matches the time remaining on your existing loan, then assess any proposed extension separately.
Can refinancing cost more even with a lower interest rate?
Yes, refinancing can cost more if switching costs, ongoing fees or a longer repayment term outweigh the interest-rate benefit. Compare the same balance and remaining term before judging the saving.
Can I refinance a doctor home loan to a standard loan?
You can apply to refinance a doctor home loan to a standard loan, subject to the new lender’s approval. Compare the existing profession-specific arrangements with the proposed loan rather than assuming the standard option is better.
Is refinancing worthwhile if I plan to sell soon?
A savings-led refinance is not worthwhile if you sell before recovering the switching costs. Compare the expected holding period with the break-even period and consider asking your current lender to reprice instead.
Does refinancing let me access equity automatically?
No, refinancing does not automatically give you access to equity. Additional borrowing requires lender approval, an acceptable valuation and an assessment of your ability to repay the increased debt.
One last thing
Ask for the repayment on the same remaining term before asking how low the repayment can go. That question exposes whether a proposed improvement comes from a better loan or simply more time in debt.
Make it the first test in your 2026 refinance review. Then decide whether your priority is lower total interest, improved cash flow or a more suitable structure—and assess the offer against that priority.
Related guides
- Best offset home loan accounts
- Best home loan lenders for doctors
- How to choose a doctor mortgage broker for complex income