Yes, doctors can get a home loan during probation in Australia in 2026, but approval depends on the lender’s employment policy, your income evidence and your overall financial position. Probation is not an automatic rejection, and being a doctor is not an automatic exemption from income checks or other lending requirements.
- Doctor home loan probation applications need a lender that accepts your employment circumstances, plus evidence of affordable repayments.
- Mortgage Pros specialises in doctor home loans; seek advice before choosing a lender or submitting an application.
- Prepare your employment contract, available payslips and evidence of previous medical employment.
- Check probation acceptance separately from overtime assessment, deposit requirements and any professional eligibility criteria.
Why this matters
A new hospital appointment can improve your income while putting you back on probation. A lender still needs to assess whether your documented earnings support the proposed repayments; your job title alone does not settle that question.
Check employment eligibility before making a formal application. You can contact Mortgage Pros to discuss your doctor home loan circumstances and the evidence needed for an assessment. A policy check is not an approval, but it helps identify issues before you commit to a property purchase.
Can doctors get a home loan during probation?
Doctors can obtain a home loan during probation where the lender accepts their employment circumstances and the application satisfies its other requirements. The central issue is not simply whether your contract contains a probation clause; it is whether the lender accepts the employment and income evidence supporting your application.
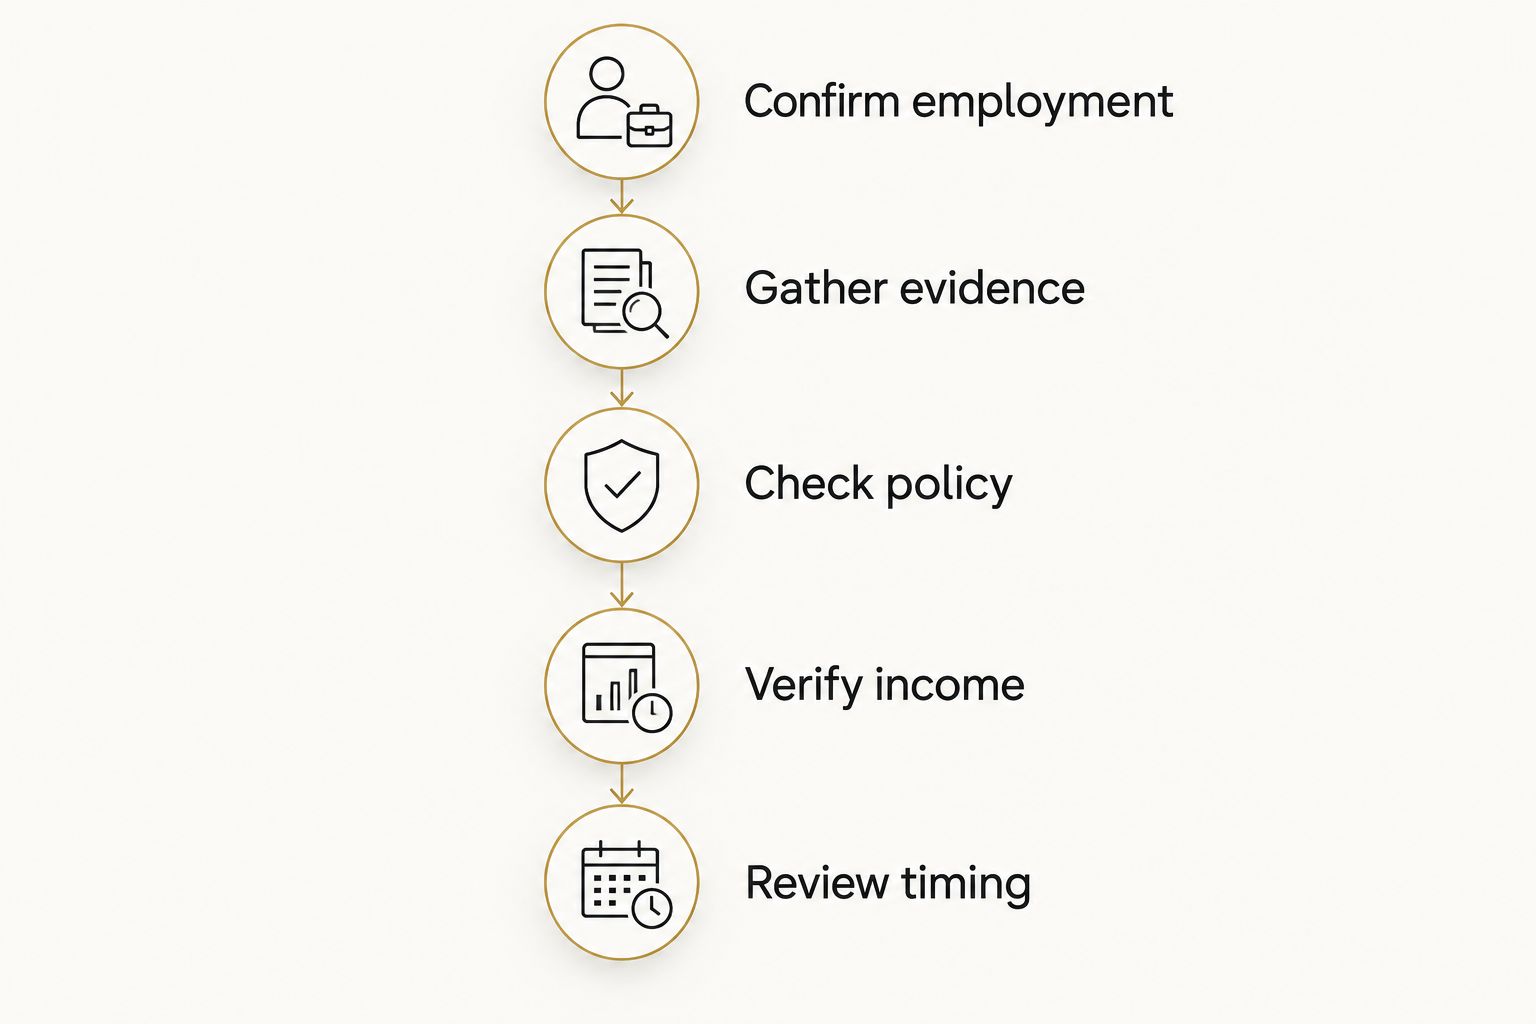
Use this sequence before choosing a loan:
- Confirm employment. Establish whether your position is permanent, fixed-term, casual or a locum engagement. Read the probation clause and any contract end date separately.
- Gather evidence. Collect your signed contract, available payslips and previous employment records. Explain any gap between appointments.
- Check policy. Ask whether the lender accepts your precise employment arrangement during probation and what supporting documents it requires.
- Verify income. Separate base salary from overtime, on-call payments, allowances and other earnings. Confirm which components the lender will assess.
- Review timing. Match the lender’s requirements to your property search, finance deadline and settlement obligations before proceeding.
These checks address eligibility, not just borrowing capacity. An income estimate is not useful if the lender does not accept the employment arrangement behind it.
Permanent employment with a probation period
A permanent position and a probation period describe different aspects of your employment. Permanent employment does not erase the probation clause, so provide the complete contract rather than relying only on an offer summary.
The useful evidence includes your commencement date, contracted salary, ordinary hours and probation terms. If you have moved directly from another medical position, provide that history as well so the lender can assess the transition.
Best for: doctors who can clearly document an ongoing salaried role. The strength is a defined employment arrangement; the limitation is that the lender must still accept the probation period and verify the income.
Fixed-term hospital contracts during probation
A fixed-term contract has an end date, which creates a separate assessment question from probation. A lender accepting probation does not establish that it will also accept your contract duration or renewal circumstances.
Provide the current contract and relevant previous contracts. If you have written confirmation of an extension or future appointment, include it; do not present an expected renewal as guaranteed employment.
Best for: doctors with documented hospital appointments and a clear employment history. Contracts help explain continuity, but future work that is not confirmed should not be treated as assured income.
Locum work or a move into private practice
Locum work and private-practice income need their own assessment. An employment offer does not necessarily describe how that income is earned, especially where you invoice through a business rather than receive a salary.
Explain whether you are an employee, contractor or business owner, and identify which income will support repayments. Ask for the document requirements for that arrangement rather than assuming a salaried probation policy applies.
Best for: doctors whose application needs to distinguish different sources of earnings. The benefit is a clearer income picture; the limitation is that a new income source without an established record requires specific lender confirmation.
Should you apply during probation or wait?
Apply when the employment policy and evidence support the application—not simply because you have found a property. Waiting is useful when it resolves a specific issue, such as a lender requiring probation to end; it does not automatically resolve affordability or deposit concerns.
| Approach | Best for | Main benefit | Main limitation |
|---|---|---|---|
| Apply during probation | Doctors whose employment arrangement is accepted and documented | Allows assessment without waiting solely for probation to finish | Acceptance still depends on the full application |
| Wait until probation ends | Doctors targeting a lender that requires completed probation | Removes that lender’s probation-related obstacle | Does not fix unrelated income, debt or deposit issues |
| Seek an assessment before deciding | Doctors with unclear contract terms or mixed income | Identifies the evidence or employment issue to resolve | An initial assessment is not formal loan approval |
For a 2026 purchase, ask what would materially change if you waited. A completed probation period, additional payslips or written contract confirmation are specific changes; waiting without identifying the problem gives you no clear decision point.
If a finance deadline is already approaching, tell your broker immediately. Ask your conveyancer or solicitor about the contract obligations rather than assuming a pending application protects your position.
Why doctor home loan probation assessments vary
Probation is only part of a home loan application. These factors explain why an answer based on another doctor’s approval is not enough:
- Employment arrangement: permanent, fixed-term, casual and contracting work require different evidence. Describe your actual arrangement accurately.
- Employment continuity: previous roles and gaps help explain how the current appointment fits your work history. Supply records rather than relying on a verbal summary.
- Income composition: base salary is distinct from overtime, on-call earnings and other payments. Ask which components support the lender’s repayment assessment.
- Deposit and borrowing level: accepting employment during probation does not establish that the proposed loan meets the lender’s other criteria.
- Existing commitments: debts, living expenses and other obligations remain part of the affordability assessment.
- Application timing: a future commencement date, contract expiry or upcoming employment change needs to be disclosed and considered.
Do not confuse professional eligibility with income acceptance. A loan feature offered to eligible medical professionals does not, by itself, confirm acceptance of probation or every part of your earnings.
What documents should you prepare in 2026?
Start with documents that explain your employment and financial position. The lender sets the final requirements, so treat this as a preparation checklist rather than a guaranteed approval package.
Employment evidence
Prepare your signed employment contract, available payslips and relevant previous employment records. Include written variations where your salary, hours or appointment terms have changed.
Check that the documents tell the same story. If the salary in your contract differs from your payslip, identify whether the difference reflects part-time hours, allowances, deductions or another documented change.
Income evidence
Separate ordinary salary from variable earnings. Your budget should distinguish what you expect to earn from what the lender has confirmed it will use.
For roster-dependent earnings, read the guide to using overtime and on-call pay for a home loan. Probation acceptance and variable-income acceptance are separate checks; a positive answer to one does not answer the other.
Financial evidence
Have your deposit records, existing loan details and information about other financial commitments ready. Disclose credit facilities and expenses accurately, even where they do not appear in your salary account.
If your deposit includes a gift or another person’s contribution, explain its source and any repayment obligation. That distinction matters to the overall assessment and should not emerge late in the application.
What should you ask a doctor mortgage broker?
Ask questions that produce a clear next step rather than a general reassurance. For a doctor home loan probation enquiry in 2026, the useful questions are:
- Does the lender accept my employment type while I am on probation?
- Which documents establish that acceptance?
- Does my contract end date create a separate issue?
- Which parts of my income will support the repayment assessment?
- What would need to change if I cannot apply now?
- What conditions remain before I can rely on an approval?
Mortgage Pros is best suited to doctors seeking specialist mortgage-broking support for a doctor home loan enquiry. Broking support helps you work through the application questions; the lender still makes the credit decision, and approval is not guaranteed.
Discuss your probation and home loan
Contact Mortgage Pros today to discuss your employment contract, income evidence and home loan plans.
Do doctors need to finish probation before applying?
Doctors do not always need to finish probation before applying; the requirement depends on the lender and the application. Ask whether completing probation is necessary for the lender being considered, rather than treating it as a universal rule.
Can doctors apply before their first payslip?
A doctor applying before receiving a first payslip needs confirmation that the lender accepts the available employment evidence. A signed contract does not automatically replace every income-verification requirement, so check before submitting an application.
Does pre-approval mean probation has been accepted?
Pre-approval is not a substitute for reading its conditions. Ask whether your probation status and income documents have been assessed, what remains outstanding and whether any employment change needs to be reported.
FAQ
Can I get a doctor home loan while I’m on probation in 2026?
Yes, a doctor home loan during probation is possible where the lender accepts your employment circumstances and the application meets its other requirements. Confirm the policy against your contract and income evidence before applying.
Do I have to wait until my probation period ends?
You do not always have to wait until probation ends. Waiting is relevant when it resolves a specific lender requirement, but it does not automatically resolve affordability or deposit concerns.
Will a hospital employment contract be enough for a home loan?
A hospital employment contract is not automatically enough to establish home loan eligibility. Ask which payslips, employment records and other financial documents the lender requires for your circumstances.
Can a doctor on a fixed-term contract apply during probation?
A doctor on a fixed-term contract needs the lender to assess both probation and the contract arrangement. Provide the contract end date, employment history and any written confirmation of future appointments.
Will the lender count my overtime and on-call income?
Overtime and on-call income require separate lender assessment. Do not include all variable earnings in your borrowing expectations until the lender confirms how it will assess them.
Does being a doctor guarantee home loan approval?
Being a doctor does not guarantee home loan approval. The lender still assesses employment, acceptable income, financial commitments, the deposit and the proposed property.
Should I tell the lender if my employment changes before settlement?
Tell your broker and lender about employment changes before settlement. Ask whether the change affects the assessment, approval conditions or documents required.
One last thing
The end of probation is not the same as home loan approval. Before you decide to wait, ask which exact obstacle waiting would remove and what evidence will demonstrate the change.
For your 2026 application, give Mortgage Pros the complete employment picture and ask for a clear next step. Contact us today to discuss your circumstances before relying on an assumed borrowing amount or committing to a purchase.
This article provides general information, not personal financial advice. Lending criteria and individual circumstances determine eligibility.
Related guides
- How to choose a doctor mortgage broker for complex income
- How locum doctors can document income for a home loan
- Is a no-LMI loan better for doctors than saving a bigger deposit?