Mortgage pre-approval has no fixed turnaround time: the wait depends on the lender, the completeness of your application and the checks your circumstances require. Ask for an estimate based on your submitted file, not a general advertised timeframe. Pre-approval is conditional, so receiving it does not mean the lender has approved the property or committed to funding your purchase.
- How long does mortgage pre-approval take? Your lender’s assessment process and application completeness determine the wait.
- Mortgage Pros helps borrowers prepare home loan applications; the lender makes the approval decision.
- A borrowing estimate is not the same as an assessed mortgage pre-approval.
- Before making a purchase commitment in 2026, check your approval conditions and obtain legal advice.
How long does mortgage pre-approval take?
The useful timeframe starts with a complete application and ends with a written decision that explains its conditions. An online borrowing estimate, an application acknowledgement and an assessed pre-approval are different milestones. Confirm which milestone the lender’s estimate covers.
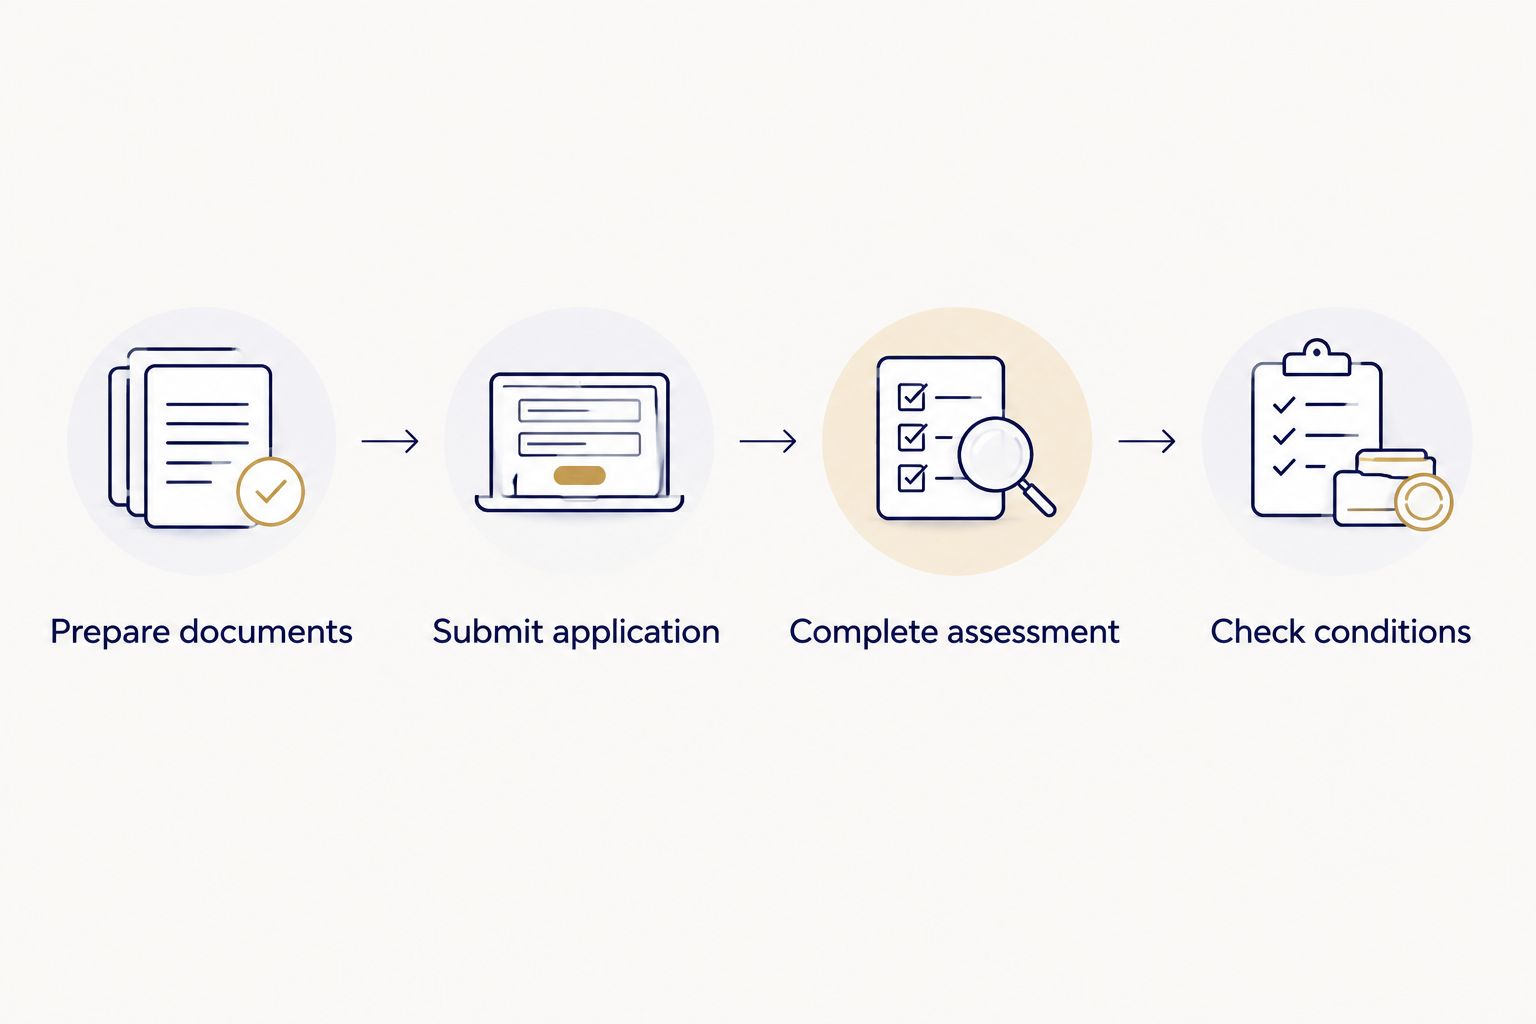
For a 2026 purchase, use this sequence to establish where your application stands:
- Prepare documents. Gather the evidence requested for your income, deposit, debts, expenses and identity.
- Submit application. Confirm that the lender has received the application and supporting documents, rather than only an initial enquiry.
- Complete assessment. Respond to questions about your finances and supply any further evidence requested.
- Check conditions. Read the written outcome, including the approved amount, expiry date and outstanding requirements.
Ask your broker or lender whether the file is awaiting allocation, under assessment or waiting for information from you. Each status requires a different response. Repeatedly asking whether approval is close is less useful than identifying the outstanding task and who must complete it.
Mortgage Pros is a mortgage broker for doctors who want help preparing and progressing a home loan application. A broker helps coordinate the application; the lender controls its assessment and decision.
Why this matters before you make an offer
A property deadline and a lending decision do not automatically align. If you make a commitment before understanding your finance position, you risk having contractual obligations while lending checks remain outstanding.
Pre-approval helps you plan a property search, but it does not replace advice about the purchase contract. Ask your solicitor or conveyancer how finance conditions, auction terms and settlement obligations apply before you sign or bid.
For your 2026 buying plan, work backwards from the purchase deadline rather than forwards from an advertised approval promise. Tell your broker about the intended auction, offer deadline or settlement date at the start. The broker can then identify what needs checking, without treating an estimate as a guarantee.
Which type of approval are you waiting for?
The word approval can describe very different stages. Read the actual document rather than relying on a label in an email, calculator result or phone conversation.
| Stage | Best for | What it tells you | Main limitation |
|---|---|---|---|
| Borrowing estimate | Early budget planning | An indicative borrowing amount based on the information entered | It is not a lending commitment |
| Conditional pre-approval | Planning your property search | A conditional assessment of your borrowing position | Outstanding conditions and property checks still matter |
| Formal approval | Confirming finance for a specific purchase | The lender’s decision on the submitted loan and property | Loan documents and settlement requirements remain |
A fast borrowing estimate is useful for orientation, but speed does not make it equivalent to an assessed application. Conditional pre-approval gives you a clearer basis for planning, while still requiring you to understand what has not been approved.
Formal approval concerns the specific transaction. Do not assume that pre-approval means every property, purchase price or loan structure will be acceptable to the lender.
Why mortgage pre-approval timing varies
The lender’s workload matters, but so does the work required to understand your application. These factors explain why another buyer’s experience is not a reliable deadline for yours:
- Document completeness. Missing statements, unreadable files or unanswered questions leave parts of the application unresolved.
- Income structure. Salary, overtime, contract work and business income require evidence that explains how you earn and what the lender can assess.
- Employment changes. A new role, probation or a different employment arrangement requires the lender to consider the applicable policy and supporting documents.
- Debts and expenses. The lender needs a consistent picture of your commitments, including credit facilities and ongoing living costs.
- Application structure. A guarantor arrangement, business ownership or multiple applicants adds information and parties to the assessment.
- Assessment workload. The lender’s queue and requests for further review affect when the file reaches a decision.
These are not reasons to rush into a different application without checking the consequences. Start by finding the unresolved issue. Changing lenders does not remove a documentation problem, and a fresh application involves its own assessment.
How to reduce avoidable delays
You cannot control the lender’s queue. You can make the application easier to assess by submitting consistent information and answering the question actually asked.
Prepare a complete document pack
Use the lender’s current checklist rather than a generic list saved from an earlier enquiry. Check that statements include all requested pages, identity documents are readable and names match across the application.
Explain unusual transactions or differences between documents before submission. A payslip, bank credit and employment contract do not always present income in the same way; give the assessor the information needed to reconcile them.
Explain income instead of only uploading payslips
Separate regular salary from overtime, allowances, bonuses and other earnings. For a medical borrower, explain whether income comes from hospital employment, locum work, private practice or a combination.
Do not assume every income component will receive the same treatment. Ask which evidence the proposed lender requires and which earnings support the borrowing assessment.
Disclose commitments accurately
Include the debts and credit facilities requested in the application, even when you do not use them regularly. Tell your broker about changes before the file reaches a decision.
Avoid altering information simply to make the application look stronger. A complete explanation gives the lender a clearer basis for assessment than figures that conflict with statements or credit information.
Reply with the full answer
When the lender asks for a document or explanation, establish exactly what is needed. A partial response leaves the original question open and creates another exchange.
Keep a record of what you supplied and when. If a request repeats, your broker can check whether the document was received, whether it was sufficient and whether something different is now required.
What changes for doctors, dentists and surgeons?
Medical borrowers need the same core assessment of income, expenses and commitments as other applicants. The practical difference is explaining employment and earnings clearly when the evidence spans different roles or income sources.
A doctor starting a hospital position should identify any probation period and provide the relevant employment evidence. Read the guide to whether doctors can get a home loan during probation before assuming a new role either prevents approval or guarantees acceptance.
For a surgeon combining hospital employment and private practice, distinguish employment earnings from business income. For a self-employed dentist, make sure the application explains the relationship between the practice, business records and personal income.
Mortgage Pros provides home loan support for doctors, dentists and surgeons; lender approval still depends on the individual application. The benefit of broker support is help presenting your circumstances and understanding requirements. It does not remove credit checks, property assessment or outstanding conditions.
If you are applying in 2026, disclose an upcoming contract change or move into private practice before submission. An application based on your current position needs to account for relevant changes the lender asks you to disclose.
Discuss your pre-approval application
Explain your income, purchase plans and deadlines before submitting a home loan application.
Can I get mortgage pre-approval before finding a property?
You can seek conditional pre-approval before choosing a property. Its purpose is to help establish your borrowing position while you search, subject to the lender’s conditions.
Once you identify a property, the lender still needs to consider the proposed security and transaction. An approval amount is not permission to buy any property up to that amount without further checks.
Ask which property types or transaction features need discussion before you make an offer. This is particularly important when the purchase differs from the scenario used in your original application.
Does pre-approval mean I can bid at auction?
Pre-approval alone does not establish that you can safely make an unconditional purchase commitment. Auction conditions and your obligations depend on the contract and applicable state or territory rules.
Before bidding, have your solicitor or conveyancer review the contract and ask your broker what lending checks remain. Confirm whether the lender has considered the property and whether the proposed purchase fits the approval conditions.
Do not substitute a verbal reassurance for a clear explanation of outstanding risks. If the transaction requires you to commit before final lending checks, understand that gap before deciding to proceed.
What should I check in the approval letter?
For a 2026 application, use the written approval as your reference point rather than an earlier conversation. Read the conditions together; the borrowing amount alone does not describe the lender’s decision.
Check:
- The approved amount and the applicants named.
- The expiry date and any requirements for renewal.
- The loan purpose and assumptions used in assessment.
- Any documents or checks still outstanding.
- Requirements relating to the property and valuation.
- What you must report if your circumstances change.
Ask your broker to explain anything unclear before using the approval to guide an offer. Keep the letter accessible so you can check it against the property and purchase arrangements you eventually choose.
FAQ
How long does mortgage pre-approval take in Australia?
Mortgage pre-approval has no fixed turnaround time across Australian lenders. Ask for a current estimate based on a complete application and confirm whether it covers an indicative result or an assessed conditional approval.
Can I get mortgage pre-approval immediately online?
An immediate online result does not, by itself, establish that a lender has assessed and conditionally approved your application. Read the result’s wording and check which documents and lending checks remain outstanding.
Does mortgage pre-approval guarantee my home loan?
Mortgage pre-approval does not guarantee final home loan approval. The lender still needs to be satisfied with the property, outstanding conditions and any relevant changes to your circumstances.
How long does mortgage pre-approval last?
The expiry date is stated in your lender’s approval letter. Check the renewal requirements before the approval expires, and do not assume an extension is automatic.
Will changing jobs affect my pre-approval?
A job change can affect the lender’s assessment of your income and employment. Tell your broker before changing the information relied on in your application and ask what evidence the lender requires.
Can a doctor apply for pre-approval during probation?
A doctor can apply during probation, but acceptance depends on the lender’s policy and the individual application. Provide your employment contract and requested income evidence rather than assuming your profession removes the assessment requirements.
Can Mortgage Pros guarantee a faster pre-approval?
The lender controls its approval decision and assessment timing. Mortgage Pros helps borrowers prepare and progress home loan applications, but broker support does not remove the lender’s checks or conditions.
One last thing
Ask what remains unapproved, not just whether you are pre-approved. That question turns a reassuring label into a practical list of tasks, conditions and decisions.
Before making your next property commitment in 2026, confirm the application stage, outstanding requirements and approval expiry. Contact us today through the enquiry option above to discuss your home loan plans. This article provides general information, not personal financial or legal advice.
Related guides
- How to choose a doctor mortgage broker for complex income
- How locum doctors can document income for a home loan
- How self-employed dentist income is assessed for a home loan