Surgeons can combine hospital salary and private practice income for a home loan when the lender accepts and verifies each income source. The assessment must account for practice expenses, business debts and overlapping payments, so adding your hospital salary to gross private billings does not establish your borrowing capacity.
- Surgeon home loan income assessments separate hospital salary from private practice earnings before combining accepted amounts.
- Private billings are not personal income: practice expenses and business structures affect the assessment.
- Mortgage Pros helps medical borrowers prepare home loan applications involving hospital and private income.
- Confirm the lender’s evidence requirements before relying on private earnings to set your property budget.
How do surgeons combine hospital and private income for a home loan?
Document each income stream separately, reconcile the figures, then have the lender assess the combined accepted income. Hospital employment and private practice need different supporting evidence, even when both relate to your work as a surgeon.
For your 2026 application, start with income treatment rather than a headline borrowing estimate. The guide to home loan lenders for surgeons provides related reading once you understand how your earnings need to be presented.
| Income source | Evidence to prepare | What it helps establish | Main limitation |
|---|---|---|---|
| Hospital base salary | Payslips, employment contract and salary credits | Current employment income | A contract alone does not explain every payment |
| Hospital overtime or on-call pay | Payslips and an earnings history | Payment frequency and consistency | Variable earnings need separate assessment |
| Private sole-trader income | Tax returns, notices of assessment and business financial information | Earnings after business expenses | Gross receipts do not equal personal earnings |
| Private income through a company or trust | Personal and entity records, financial statements and relevant distribution information | How business earnings reach you | Transfers between accounts can duplicate income already recorded |
These are preparation categories, not a universal lender checklist. Ask which documents the proposed lender requires and how it treats each source before submitting an application.
Why this matters
Your hospital income can provide a clear employment record while private practice adds another layer of assessment. That additional income only helps the application to the extent the lender accepts it after reviewing the supporting records.
A strong surgeon home loan income application explains the money; it does not simply display a large total. If your private practice has expanded while your hospital hours have reduced, the assessment needs to reflect both changes rather than combining an old salary with newer private earnings.
For a 2026 property purchase, establish an evidence-based budget before making commitments. A promising income profile is not the same as a completed credit assessment.
Hospital income: separate fixed pay from variable earnings
Your hospital payslips should distinguish base salary from overtime, on-call payments, allowances and other earnings. This makes it easier to explain which payments form your regular employment income and which fluctuate.
Prepare your current employment contract alongside recent payslips and the bank statements showing salary credits. If your appointment, hours or pay arrangement has changed, provide the records that explain the change rather than expecting the assessor to infer it.
What works in your favour
Clear payroll records connect your employment arrangement with actual payments. Consistent descriptions across your contract, payslips and application reduce ambiguity about where the income comes from.
What needs extra explanation
A payslip containing back pay or an unusually large on-call payment does not establish that the same amount recurs. Identify exceptional payments and ask how the lender will treat them.
Salary packaging also needs a clear explanation. Provide the package details so the assessor can distinguish salary, benefits and deductions without counting the same remuneration twice.
Private practice income: show earnings after expenses
Private billings measure practice revenue, not the amount automatically available for mortgage repayments. Rooms, staff, insurance and other practice expenses affect the earnings left after operating the business.
Prepare records that connect revenue, expenses and the income attributable to you. Depending on your structure, relevant documents include tax returns, notices of assessment, financial statements, business bank statements and business activity statements.
Use business records to explain private earnings, not gross billings as a substitute for earnings. Bank deposits help substantiate cash receipts, but they do not explain every business expense or ownership arrangement.
What works in your favour
Records that reconcile with each other make the income easier to assess. An accountant can explain differences between the tax return, financial statements and current trading records.
What needs extra explanation
Recent growth does not automatically establish the income figure a lender will accept. For a 2026 application, ask whether current trading information is relevant alongside completed financial records and what further evidence is required.
Company and trust income: trace the payment to you
If your private practice operates through a company or trust, explain both the entity’s earnings and how you receive income. A salary, dividend, distribution and transfer between accounts are not interchangeable descriptions.
The application should identify your ownership or beneficiary position, relevant business obligations and the records supporting payments to you. The lender’s assessment determines which amounts it accepts; money retained in a business is not automatically available as personal borrowing income.
Prevent double counting
If your company pays you a salary, that salary can already appear as an expense in the company accounts. The assessment must reconcile the salary with business earnings rather than treating every figure as separate additional income.
Likewise, transferring money from a business account into your personal account does not create another income source. Ask your accountant to identify drawings, loan-account movements and income payments accurately.
Why accepted surgeon home loan income varies
The same surgeon’s records can require different treatment under different lending policies. Focus your comparison on how the lender assesses your actual arrangement, not on a general promise to accommodate medical professionals.
- Employment terms: Permanent employment, fixed-term appointments and changing hours require an accurate explanation of your current position.
- Variable hospital earnings: Overtime and on-call payments need evidence of their nature and payment history.
- Private practice history: Established financial records and recent trading figures provide different evidence about business earnings.
- Business structure: Sole-trader, company and trust arrangements determine which records explain the income attributable to you.
- Expenses and liabilities: Practice costs, business finance and personal commitments affect the assessment beyond gross earnings.
- Changes in workload: A move towards private work must be considered alongside any reduction in hospital earnings.
Ask for the proposed treatment of each income stream before choosing a lender. An unexplained borrowing estimate gives you less decision-making value than a clear explanation of the accepted figures.
How to prepare your combined-income application
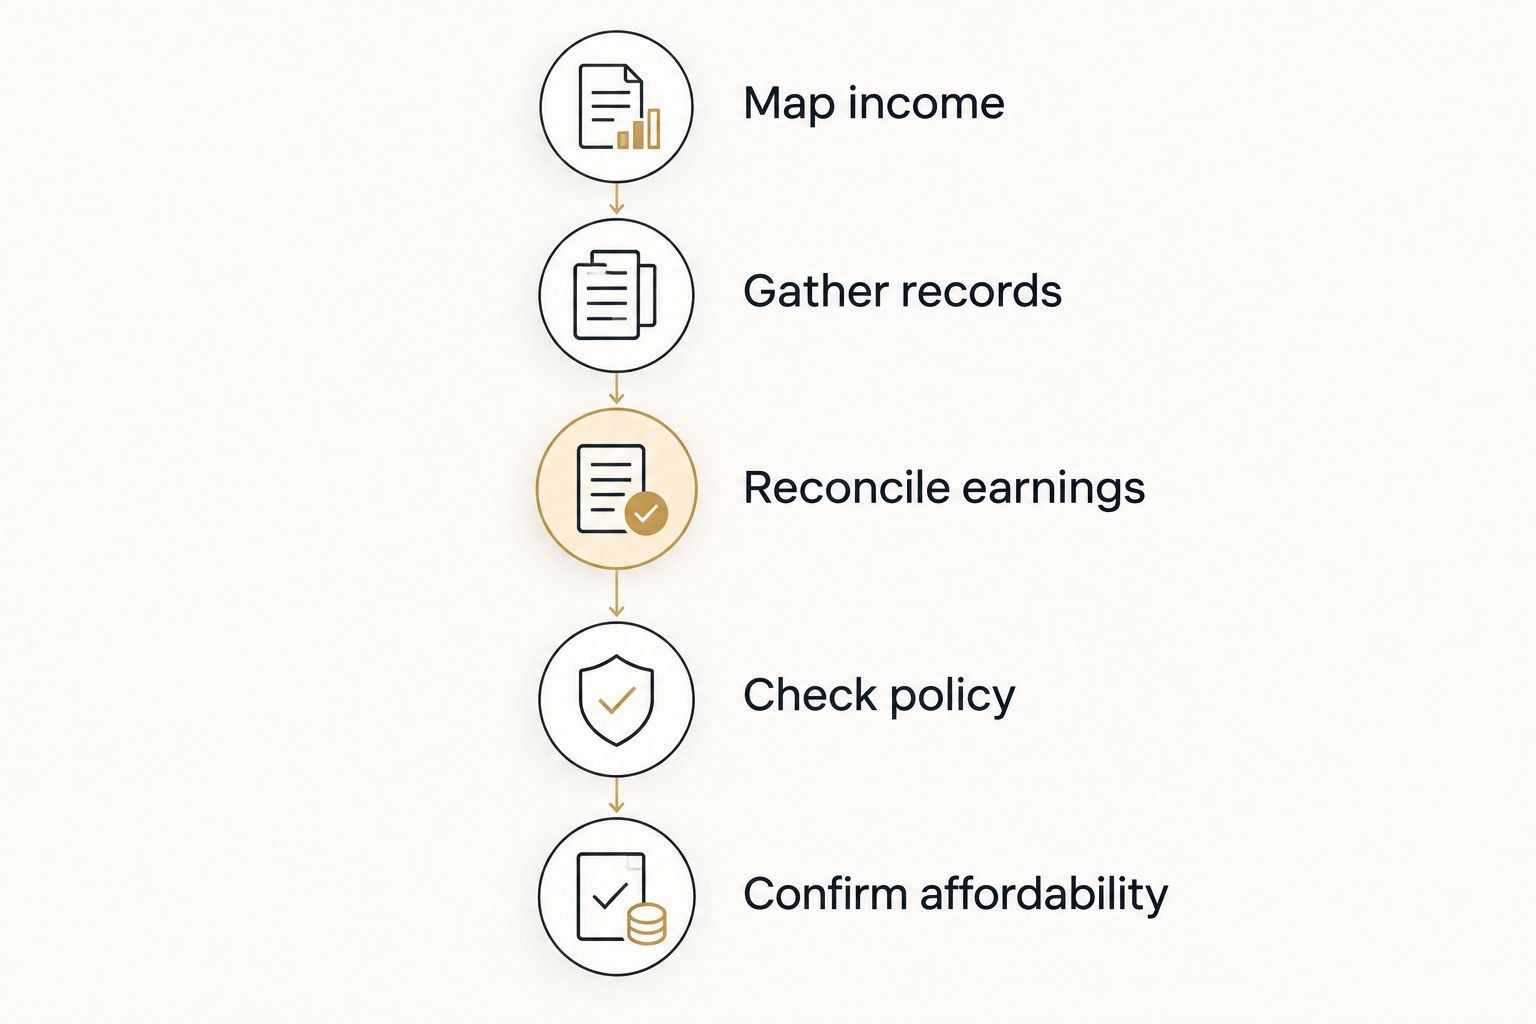
Use this sequence to organise your 2026 application. It helps keep the employment evidence, business records and proposed borrowing position consistent.
- Map income. List each hospital employer and private practice entity. Identify the type of payment you receive from each.
- Gather records. Collect employment documents, tax records, financial statements and supporting account information. Confirm the lender’s required reporting periods.
- Reconcile earnings. Ask your accountant to explain business expenses, payments to you and differences between records. Flag exceptional receipts and transfers.
- Check policy. Have the proposed lender’s treatment checked against your employment and business arrangement before relying on an estimate.
- Confirm affordability. Review the proposed repayments alongside household spending, tax commitments and business obligations before proceeding.
Keep a short written explanation of your working arrangement with the documents. For example, explain that hospital employment continues alongside private practice, or identify when hospital hours changed. The explanation should match the records rather than replace them.
Mortgage Pros is best suited to medical borrowers seeking home loan advice and application support. A broker helps organise the application and assess lender fit; the lender still decides whether to approve the loan and which income it accepts.
Discuss your combined income today
Ask Mortgage Pros about documenting hospital salary and private practice earnings for your home loan.
Can I use private income if I have only recently started practising?
Recently established private income needs a lender-specific assessment; do not assume projected billings will be accepted as established earnings. Explain your transition, provide the records already available and ask what evidence the lender requires.
If your private work has replaced hospital sessions, disclose that change at the same time. Continuing to use the previous hospital salary alongside projected private earnings would misrepresent your current position.
Will all my hospital overtime and on-call pay count?
Hospital overtime and on-call pay require separate assessment from your base salary. Provide a payment history and an explanation of the work arrangement so the lender can determine its treatment.
Ask which earnings the borrowing estimate includes and whether the estimate depends on those payments continuing. That distinction matters when deciding whether the proposed repayments suit your household budget.
Does combining income guarantee a larger loan?
Combining accepted income does not guarantee a larger loan or approval. The lender also assesses expenses, debts, dependants, credit history and the proposed property and loan arrangement.
For your 2026 budget, separate the lender’s borrowing assessment from your own comfort with repayments. Private practice cash flow and tax commitments still need room in your finances after settlement.
What should you ask before submitting an application?
Get clear answers about the income calculation before authorising submission. A lender that understands your profession still needs evidence that supports your individual application.
Ask your broker:
- Which hospital payments are included in the assessment, and which are excluded?
- What private practice income figure is being used, and which records support it?
- How have salary, distributions and business earnings been reconciled?
- What additional documents are needed because of my business structure?
- Does the estimate reflect my current hospital hours and private workload?
- Which debts and ongoing commitments have been included?
Keep these answers with your application records. If your earnings or employment arrangements change before settlement, tell your broker promptly so the application remains accurate.
FAQ
Can a surgeon use hospital salary and private practice income for the same home loan?
A surgeon can use both income sources when the lender accepts and verifies them. Hospital employment and private practice require different evidence, and the assessment must avoid counting the same earnings twice.
Do lenders use my gross private billings as home loan income?
Gross private billings are not the same as personal income available for mortgage repayments. Practice expenses, business structure and payments to you need to be considered in the income assessment.
What documents should I prepare for a mixed-income surgeon home loan?
Prepare hospital employment records and the financial records supporting your private practice earnings. Confirm the lender’s checklist for payslips, contracts, tax returns, financial statements and relevant account records.
Can a surgeon apply while moving from hospital work into private practice?
A surgeon can seek an assessment during the transition, but approval depends on the lender’s requirements and supporting evidence. Disclose reduced hospital hours and ask how the lender will assess newly established private income.
Can I count company income as well as the salary my company pays me?
Company earnings and your salary need to be reconciled before they are combined in an assessment. The salary can already be recorded as a company expense, and account transfers are not automatically additional income.
Will an accountant’s letter replace my financial records?
An accountant’s letter does not automatically replace the records a lender requires. Use it to explain your structure or reconcile figures, and confirm which supporting documents must accompany it.
Can a mortgage broker guarantee that all my surgeon income will count?
A mortgage broker cannot guarantee that a lender will accept every income stream or approve the loan. The broker can explain the proposed treatment and help prepare supporting evidence before submission.
One last thing
Check that your income documents describe the same working arrangement. An older hospital contract and newer private accounts can each be accurate for their own period while presenting an incomplete picture of how you earn now.
Before your 2026 application, mark any changes in hours, employment or practice ownership on a short timeline. Contact Mortgage Pros today to discuss the evidence needed for your combined-income home loan assessment.
Related guides
- Can doctors use overtime and on-call pay for a home loan?
- How to choose a doctor mortgage broker for complex income
- How is self-employed dentist income assessed for a home loan?