Yes, a doctor can get a home loan without contributing a saved cash deposit if a lender accepts another arrangement, such as a suitable family guarantee or equity in another property. Medical employment alone does not remove deposit requirements, and you still need to cover any purchase costs the loan does not fund and demonstrate that you can afford the repayments.
- Can a doctor get a home loan with no deposit? Yes, subject to lender approval and suitable alternative security.
- A family guarantee can replace a cash deposit, but it puts the guarantor’s property at risk.
- An LMI waiver does not remove the deposit requirement or guarantee approval for doctor home loans.
- Mortgage Pros helps medical borrowers assess home loan options; approval remains the lender’s decision.
Can a doctor get a home loan with no deposit?
A doctor can buy without a saved deposit, but the lender still needs an acceptable funding and security arrangement. A family guarantee, existing property equity or a genuine cash gift can change how you fund the purchase. These arrangements are not interchangeable.
For an individual assessment, contact Mortgage Pros about your home loan plans. Explain whether you have no savings, no accessible cash, or a deposit that falls short of the lender’s requirements.
| Arrangement | Best for | Main benefit | Main limitation |
|---|---|---|---|
| Family guarantee | Borrowers with an eligible, willing guarantor | Additional property security can support borrowing without a saved deposit | The guarantor takes on financial risk |
| Existing property equity | Borrowers who already own property | Equity can support deposit funding without using cash savings | Additional borrowing increases debt and repayments |
| Genuine cash gift | Borrowers receiving non-repayable family assistance | A gift can provide the deposit you have not saved yourself | The lender must accept and verify the funds |
| Low-deposit doctor loan | Doctors with some deposit funds | Medical-professional lending policies can be relevant | A smaller deposit is still a deposit; approval conditions apply |
Use this distinction when comparing options in 2026: no saved deposit is not the same as no deposit, no security or no upfront costs.
Why this matters
A deposit question is really several questions: how you fund the purchase, what property secures the debt, and whether your income supports the repayments. Solving one does not solve the others.
For doctors, employment contracts, on-call payments, locum work and private-practice income also affect the application. Your occupation provides context, but the lender assesses the documented financial position behind it.
Before signing a purchase contract in 2026, establish the cash you need at settlement and the conditions attached to any approval. A borrowing estimate is not confirmation that a particular property and funding arrangement will be accepted.
Family guarantee: buying without a saved deposit
A family guarantee allows a lender to take additional security over a guarantor’s property. Where the lender accepts the arrangement, that security can support a purchase that your cash savings alone would not support.
Best for: a borrower with an eligible family member who understands and accepts the guarantee. The guarantor needs to meet the lender’s requirements; willingness alone is not enough.
The benefit is a different way to address the lender’s security requirements. The drawback is serious: if you default, the guarantor can become liable under the guarantee, putting their property at risk.
Ask for the guarantee’s scope to be explained before anyone commits. The borrower and guarantor should understand the secured amount, obligations, enforcement risks and conditions for a future release.
Do not treat a guarantee as temporary simply because you expect your property’s value to rise. Release requires the lender’s agreement and an assessment against its requirements at that time. Independent legal advice helps the guarantor understand the commitment separately from your borrowing goals.
Existing equity: no cash deposit does not mean no debt
Existing property equity can support another purchase without requiring you to save the deposit entirely in cash. However, equity is not money sitting in a transaction account: accessing it generally requires an approved lending arrangement.
Best for: a property owner whose available equity and repayment capacity support additional borrowing. The lender assesses the existing property, current debt and proposed loan structure.
The benefit is preserving cash savings while using an existing asset. The limitation is that borrowing against equity adds debt, and the lender assesses the combined repayments rather than viewing the deposit funding in isolation.
Ask which properties secure each loan and what happens if you later sell or refinance one of them. A structure that supports today’s purchase can also affect your future choices.
Gifted deposit: no savings, but still a deposit
A genuine cash gift can fund a deposit even when you have not saved the money yourself. That makes it a no-saved-deposit purchase, not a purchase without a deposit.
Best for: a borrower receiving non-repayable assistance that the lender accepts. You need to establish where the funds came from and whether any repayment obligation exists.
The benefit is deposit funding without an additional family debt. The limitation is that a gift does not automatically satisfy every lender’s funds-verification or genuine-savings requirements.
Be accurate about the arrangement. If your family expects repayment, disclose that obligation rather than describing the money as a gift. A family loan changes your financial commitments and must be assessed accordingly.
Low-deposit doctor loans: an LMI waiver is not a deposit waiver
A low-deposit loan requires some contribution towards the purchase. An eligible medical borrower can also be assessed for a professional lending policy, including an exemption from lenders mortgage insurance where the lender’s criteria are met.
Best for: a doctor who has some deposit funds and wants the applicable professional policies assessed. The benefit is access to a different set of lending criteria; the limitation is that professional eligibility does not establish repayment capacity or guarantee approval.
Lenders mortgage insurance, or LMI, protects the lender rather than the borrower. An LMI waiver does not cancel your debt, cover your repayments or automatically fund your purchase costs.
Keep three concepts separate when assessing a doctor home loan in 2026:
- Deposit: the contribution towards the purchase that does not come from the purchase loan itself.
- LVR: the loan-to-value ratio, calculated by dividing the loan amount by the lender’s property valuation.
- LMI waiver: an exemption from an insurance requirement, subject to the lender’s policy.
A 100% LVR describes a loan equal to the property’s assessed value. An 80% LVR describes a loan equal to 80% of that value, leaving a 20% difference before purchase costs. These are mathematical relationships, not an offer or confirmation that a lender will approve either structure.
Why a doctor’s no-deposit eligibility varies
The answer depends on your application, not your job title alone. These factors determine whether a proposed funding arrangement works:
- Income evidence: salary, overtime, allowances, locum earnings and practice income need supporting documents and lender assessment.
- Existing commitments: personal loans, credit cards, study debt and other obligations affect repayment capacity.
- Security: the purchased property and any additional property security must meet the lender’s requirements.
- Funds source: savings, gifts and borrowed deposit funds need to be identified accurately.
- Purchase costs: transfer duty where applicable, legal work, inspections and lending-related charges affect the cash needed.
- Professional eligibility: registration, employment circumstances and the lender’s medical-professional criteria affect access to relevant policies.
A strong income does not replace acceptable security. Equally, substantial family property equity does not replace your ability to make the repayments.
How to prepare a no-deposit application
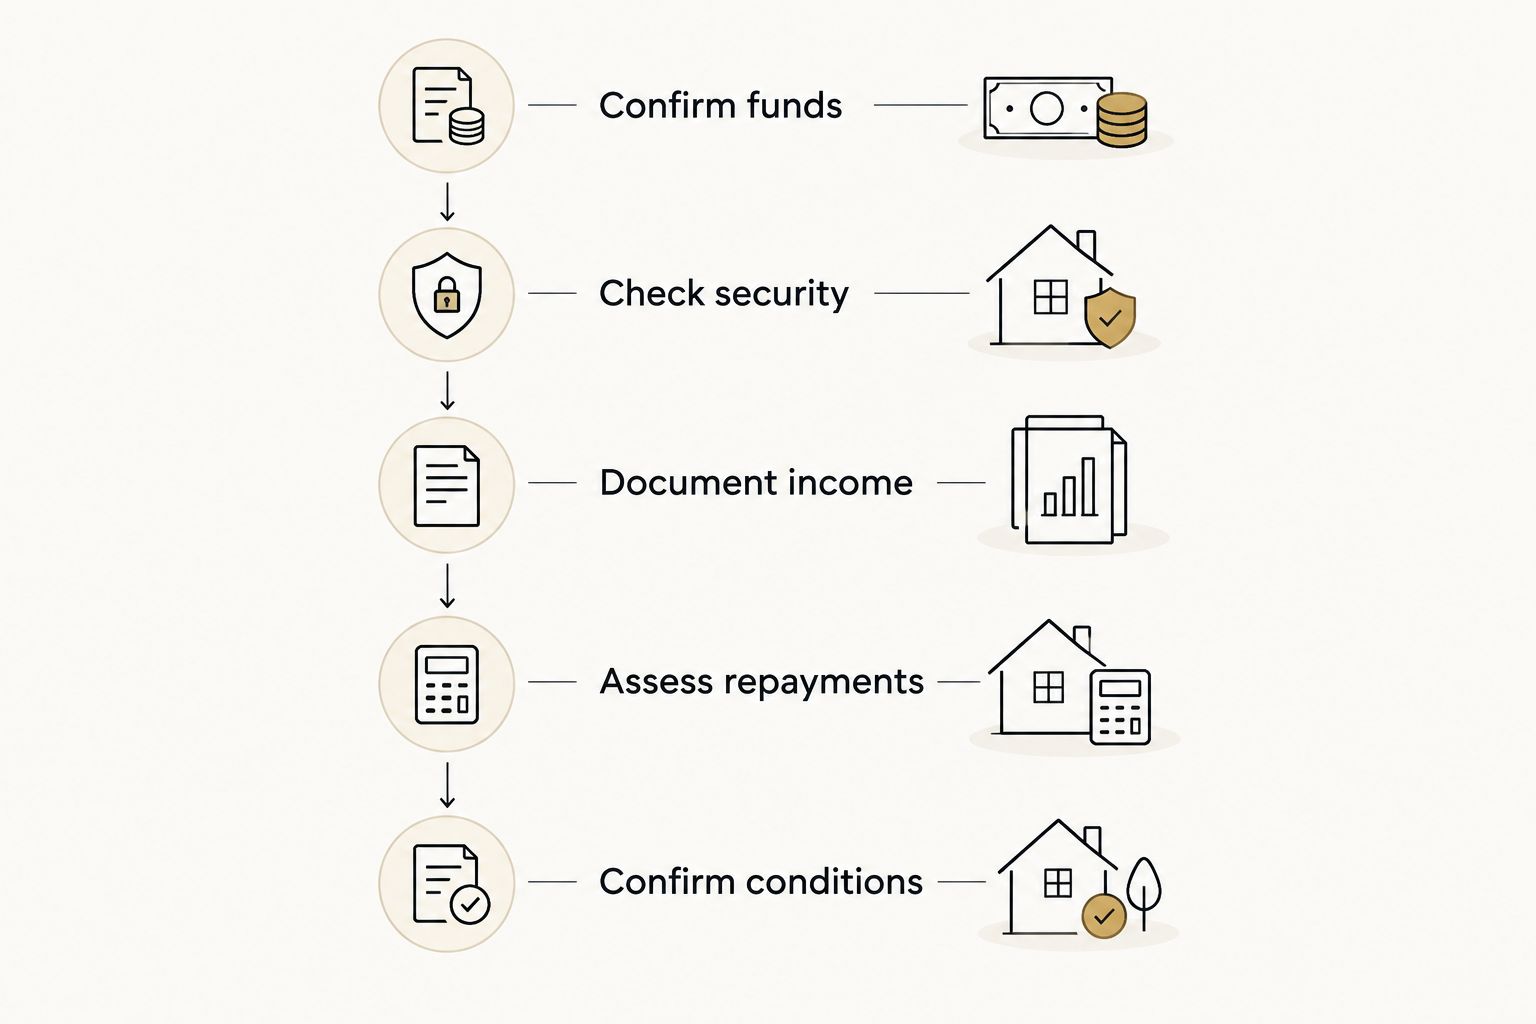
Follow this sequence before choosing a property or relying on a proposed loan amount. It separates the funding question from the approval question.
- Confirm funds. List accessible savings, any genuine gift and the source of every contribution. Identify money you cannot use at settlement.
- Check security. Establish whether the proposal relies on a guarantee, existing property equity or the purchased property alone. Identify the owners and existing loans attached to additional security.
- Document income. Gather the documents relevant to your employment or business structure. Disclose variable earnings separately so their treatment can be assessed.
- Assess repayments. Include existing debts, living expenses and the proposed borrowing. Do not use gross salary alone as your affordability test.
- Confirm conditions. Ask what remains outstanding, including property valuation, document verification and any guarantor requirements. Check contract deadlines with your solicitor or conveyancer.
The sequence matters: establish the funding structure before treating an indicative borrowing amount as a purchase budget.
Which documents should a doctor prepare?
Start with identification, evidence of income, bank statements and details of your debts and expenses. The exact document list depends on whether you are salaried, contracting, working as a locum or running a practice.
For employed doctors, payslips and an employment contract help explain base pay and employment terms. For variable income, supporting records help distinguish recurring earnings from isolated payments. Do not assume every component will be counted in full.
For self-employed doctors, the lender needs evidence appropriate to the business and application. Keep personal income, business revenue and business expenses distinct; practice turnover is not the same as income available for home loan repayments.
A guarantor or equity-backed application also needs property and loan information. Get the required document list before submitting so everyone understands their part in the application.
Can I borrow the full purchase amount and purchase costs?
Borrowing the full purchase amount and funding purchase costs are separate approval questions. A no-saved-deposit arrangement does not automatically cover every amount payable before settlement.
Ask for an itemised funds-to-complete calculation for your proposed purchase in 2026. It should distinguish the purchase amount, expected costs, approved borrowing and funds you must contribute.
Also clarify when each payment falls due. The deposit payable under the sale contract is not necessarily the same as the contribution required by the lender, so check the contract arrangements with your solicitor or conveyancer.
Does being a doctor guarantee approval?
Being a doctor does not guarantee approval, even where a lender has a medical-professional policy. The lender still assesses affordability, credit history, acceptable security and supporting evidence.
Mortgage Pros is best for doctors seeking mortgage-broking support to assess home loan options, rather than assuming their profession guarantees approval. A broker can help assess the proposed structure, but the lender makes the credit decision.
Discuss your doctor home loan
Ask Mortgage Pros to assess your deposit position, income and proposed funding arrangement.
FAQ
Can a doctor get a home loan with no deposit in Australia?
Yes, a doctor can qualify without a saved cash deposit where a lender accepts an alternative arrangement, such as a suitable family guarantee. Approval still depends on repayment capacity, security and the lender’s requirements.
Does an LMI waiver mean I do not need a deposit?
No, an LMI waiver is not a deposit waiver. It removes an insurance requirement under the lender’s policy, not the need to satisfy funding and security requirements.
Can my parents help me buy without savings?
Parents can assist through a genuine gift or an eligible guarantee, subject to lender acceptance. A gift provides funds, while a guarantee exposes the guarantor to obligations under the guarantee.
Can I use equity instead of a cash deposit?
Yes, existing property equity can support deposit funding through an approved lending arrangement. Accessing that equity generally involves borrowing, which increases the debt assessed against your repayment capacity.
Will a lender count my on-call pay and overtime?
A lender assesses on-call pay and overtime under its income policy rather than automatically counting every payment in full. Provide supporting records so the recurring and variable components can be assessed.
Do I still need money for settlement if I have a guarantor?
You still need to account for every purchase and settlement cost, even with a guarantor. Ask which amounts the approved borrowing covers and which require your own funds.
Does pre-approval mean I can buy any property?
No, pre-approval does not establish that every property or funding structure is acceptable. Check the outstanding conditions and obtain advice on the purchase contract before committing.
One last thing
Ask for your required cash contribution, not just your maximum borrowing amount. That exposes the gap between an attractive borrowing estimate and a purchase you can actually complete.
Before committing in 2026, ask Mortgage Pros to assess the proposed funding structure and explain the next application steps. Contact the team today with your income details, available funds and any proposed family assistance.
Related guides
- Best home loan lenders for doctors
- Can doctors use overtime and on-call pay for a home loan?
- How can locum doctors document income for a home loan?
- How to choose a doctor mortgage broker for complex income