Best specialist shortlist: Heartland and Household Capital. Best government alternative to compare: the Home Equity Access Scheme. The best reverse mortgage lenders in 2026 are the ones whose loan structure, eligibility rules and long-term equity impact fit your retirement—not simply the lender with the most recognisable name.
- Compare Heartland and Household Capital when shortlisting the best reverse mortgage lenders in Australia.
- The Home Equity Access Scheme is a government alternative, not a private reverse mortgage lender.
- Compare projected debt, remaining home equity, repayment triggers and protections before choosing.
- Mortgage Pros is a mortgage broking firm, not a reverse mortgage lender.
If you are still deciding whether borrowing against your home is appropriate, start with how much equity you can release from your home. Equity is not the same as an approved borrowing limit, and releasing it creates obligations that need to fit your future housing needs.
Why this matters
A reverse mortgage lets eligible older homeowners borrow against their property without making the regular repayments associated with a standard home loan. Interest and applicable charges added to the balance increase the debt over time.
That changes the decision. You need to understand what happens when you sell, move into care, leave a partner in the home or pass away—not just whether the loan meets today's cash need.
Treat this 2026 guide as a starting shortlist, not a declaration that one lender suits every retiree. Obtain current documents and personalised projections before making a decision.
What makes the best reverse mortgage lender?
Use these criteria before comparing names:
- Eligibility fit: Check borrower age, ownership, property type, location and existing mortgage requirements.
- Funding structure: Match the way you receive funds to the expense you actually need to cover.
- Projected equity: Compare the debt and remaining home equity under consistent assumptions.
- Occupancy protections: Understand who can remain in the property and what happens when circumstances change.
- Exit conditions: Check repayment triggers, voluntary repayment rules and the process when selling or entering care.
- Advice and documentation: Request clear written explanations, an equity projection and independent legal advice before signing.
A familiar brand cannot compensate for unsuitable terms. Eliminate an option that fails your essential requirements before comparing its other features.
Reverse mortgage options at a glance
The order below is a comparison sequence, not a measured performance ranking. The Home Equity Access Scheme is included because it addresses a similar need, although it is not a private lender.
| Option | Best for | Standout comparison point | Key limitation |
|---|---|---|---|
| Heartland | Starting with a specialist reverse mortgage lender | A dedicated reverse mortgage proposition | Your property, circumstances and contract still determine suitability |
| Household Capital | Discussing home equity within retirement funding | A retirement-focused home equity proposition | A retirement focus does not replace independent financial advice |
| Home Equity Access Scheme | Checking a government alternative | Government-administered borrowing against Australian real estate | Separate eligibility and payment rules apply |
Do not assume the options offer identical payment structures, protections or eligibility. Ask each provider to explain its own terms in writing.
1. Heartland: best for a specialist reverse mortgage comparison
Heartland is a specialist reverse mortgage lender to include in an Australian shortlist. Its relevance here is straightforward: you can assess a reverse mortgage proposition rather than treating an ordinary home loan as an equivalent product.
Best for: Borrowers who want a dedicated reverse mortgage lender as their starting comparison.
Heartland pros
- A specialist reverse mortgage offering provides a relevant starting point.
- You can focus the enquiry on equity release and later-life borrowing.
- Its proposal can serve as a comparison against another specialist lender.
Heartland cons
- A specialist offering does not establish that its terms are best for you.
- Capitalised interest reduces remaining equity unless offset by repayments or other factors.
- Eligibility and property acceptance still require individual assessment.
Ask Heartland how the proposed loan behaves if you move permanently, sell the property or need to repay an existing mortgage. Where a partner or another person lives with you, request a written explanation of their position under the contract.
For a 2026 enquiry, use current documents rather than an older comparison article. Ask for projections based on the amount and payment pattern you actually need.
Verdict: Hold—keep Heartland on the shortlist until its written proposal passes your equity and occupancy checks.
2. Household Capital: best for retirement-funding discussions
Household Capital is another Australian specialist to include when comparing reverse mortgage options. Its retirement-funding focus makes it relevant when the question is how home equity fits alongside your broader retirement resources.
Best for: Homeowners who want to discuss equity release in the context of retirement spending and future needs.
Household Capital pros
- A retirement-focused proposition keeps later-life funding central to the discussion.
- It provides another specialist proposal to assess alongside Heartland.
- It gives you an opportunity to test whether the proposed borrowing matches your spending purpose.
Household Capital cons
- Retirement-focused lending is not a substitute for independent financial advice.
- Borrowing against the home reduces the equity left for other purposes.
- Suitability depends on current terms, your property and personal circumstances.
Explain whether you need to meet a specific expense, supplement ongoing income or preserve flexibility for future care. Those are different needs, and the proposed borrowing should reflect that difference.
Ask Household Capital to separate the lender's assessment from questions for your financial adviser. Pension treatment, estate planning and aged-care planning need attention beyond loan approval.
Verdict: Hold—compare Household Capital's proposal against the same funding needs and assumptions used for Heartland.
3. Home Equity Access Scheme: best government alternative
The Home Equity Access Scheme is an Australian Government loan scheme administered by Services Australia. It lets eligible older Australians access voluntary borrowing secured against Australian real estate, subject to the scheme's rules.
Best for: Homeowners who want to assess a government equity-release alternative before choosing private borrowing.
Home Equity Access Scheme pros
- It provides a government-administered alternative to private reverse mortgages.
- It is directly relevant to eligible older Australians considering home equity access.
- Comparing it broadens the decision beyond private lenders.
Home Equity Access Scheme cons
- Eligibility depends on the scheme's requirements, not just property ownership.
- Payment and borrowing rules are specific to the scheme.
- It remains debt secured against property and affects remaining equity.
Check the current Services Australia eligibility requirements and payment rules for 2026. Do not assume receiving a particular pension payment is the only eligibility question, or that the scheme will meet every funding purpose.
Compare the scheme with a private proposal using the same intended borrowing and time horizon wherever the structures permit. Different payment arrangements need explanation rather than a misleading like-for-like label.
Verdict: Hold—complete the government-scheme eligibility check before committing to a private reverse mortgage.
How these options are ranked
This shortlist prioritises relevance to Australian homeowners considering later-life equity release: specialist reverse mortgage lending first, followed by the government alternative.
It does not rank providers by independently measured service quality, approval speed or borrower outcomes. The deciding criteria remain eligibility, funding structure, projected equity, occupancy protection and exit conditions.
There is no justified universal winner without a borrower-specific comparison. A lender that suits one property owner can be unsuitable for another.
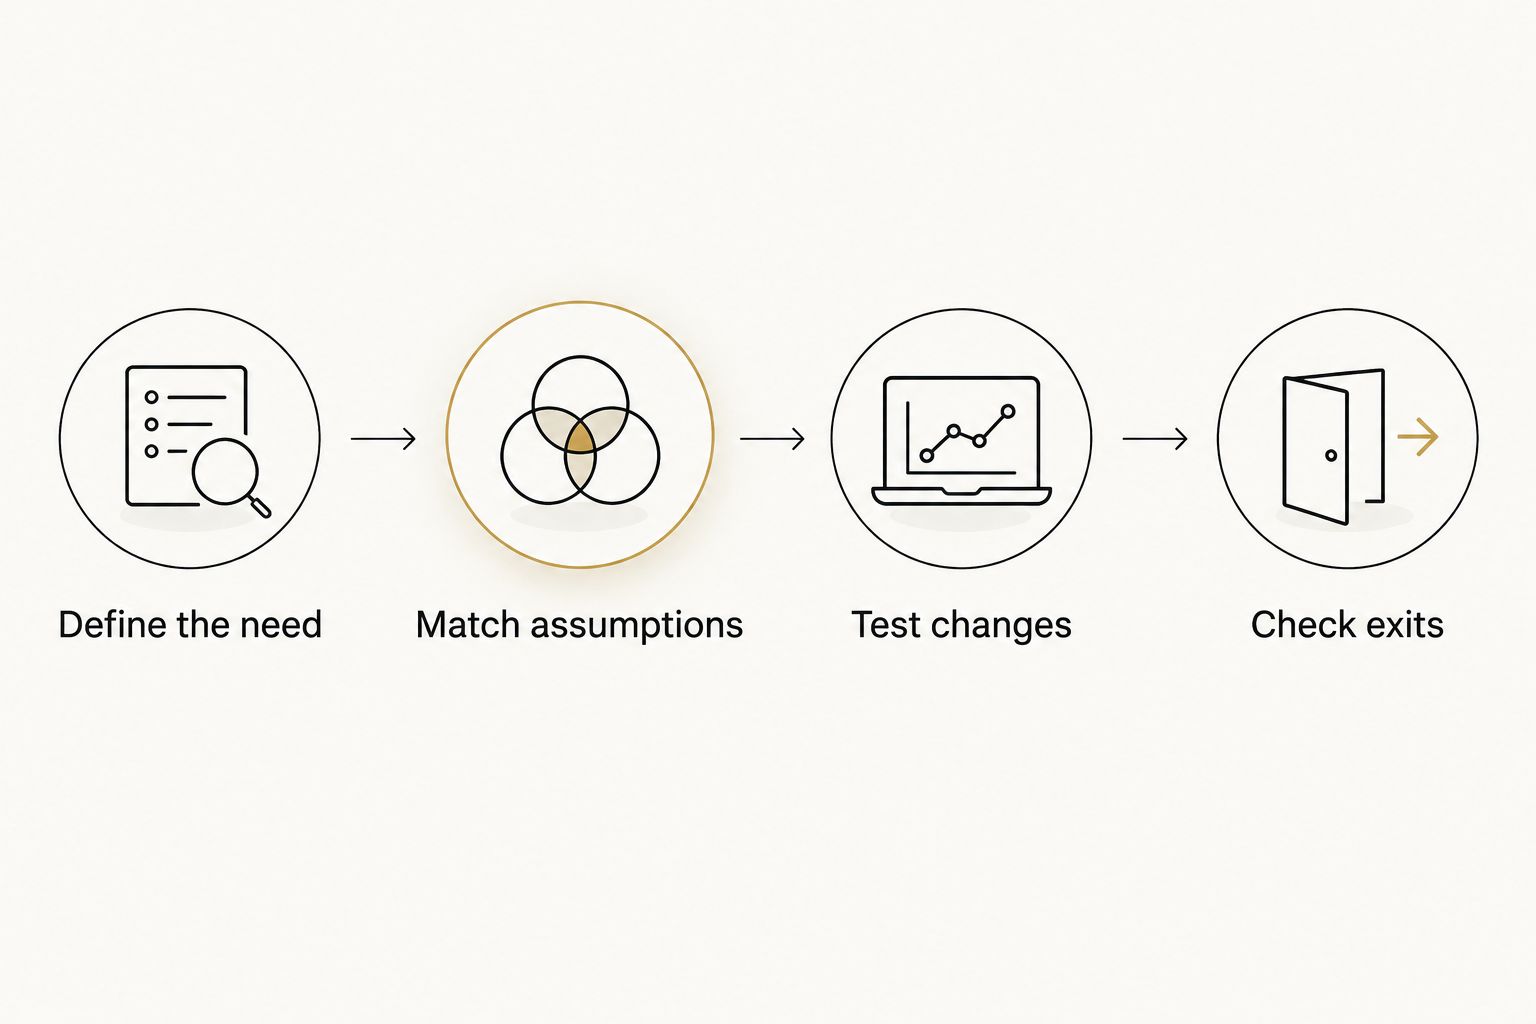
Compare proposals without misleading yourself
Use a consistent comparison process. Otherwise, a smaller initial advance or a different drawdown pattern can make one projection look more favourable without proving the loan is better.
Define the need
Write down the purpose of the borrowing and when you need the money. Separate an immediate expense from spending that will arise gradually.
Borrowing money earlier than necessary exposes that amount to interest for longer. Ask whether the proposed funding arrangement matches the timing of your expenses.
Match assumptions
Request projections over 10 years, 20 years and 30 years, where relevant to your circumstances. These are comparison horizons, not forecasts of how long you will live or remain at home.
Use the same intended advances and property-growth assumptions across proposals. Ask each provider to explain any assumptions that cannot be matched.
Test changes
Ask what happens if interest rates rise, property growth disappoints or you need to move earlier than planned. A projection based on favourable assumptions is not a guarantee.
Include a scenario where you need funds for future accommodation or care. The remaining equity matters as much as the amount you can access now.
Check exits
Read the events that make the loan repayable. Ask about selling, permanent moves, death, contract breaches and the treatment of other occupants.
Get explanations in writing before signing. Verbal reassurance does not replace the contract or independent legal advice.
Your 2026 comparison should leave you able to explain both the immediate benefit and the long-term trade-off in plain language. If the explanation still feels unclear, pause the application and ask further questions.
Understand the protections—and their limits
Australian reverse mortgages carry consumer protections, including statutory no-negative-equity protection for covered loans. ASIC's Moneysmart guidance explains reverse mortgages, their risks and the need to understand projected equity.
No-negative-equity protection does not mean your equity is preserved. It addresses a different risk: the debt exceeding the property's value, subject to the applicable legal framework and loan conditions.
Before accepting an offer, establish:
- Borrower protection: Who is named as a borrower, and what rights do they have?
- Other occupants: What happens to a partner or family member who is not a borrower?
- Property obligations: What maintenance, insurance and other obligations must you meet?
- Repayment events: Which circumstances trigger repayment, and what process follows?
- Future flexibility: What happens if you want to move or make voluntary repayments?
Take the contract to an independent solicitor. Ask a financial adviser about pension and retirement implications, and seek appropriate advice about aged-care and estate-planning consequences.
Which reverse mortgage option should you choose?
For an undecided borrower, start with comparable written proposals from Heartland and Household Capital, then check the Home Equity Access Scheme. Choose only after understanding the debt projection, occupancy position and exit terms.
A reverse mortgage is not automatically the right answer. Consider whether changing spending, using other resources or downsizing better addresses the underlying need, with professional advice where required.
Mortgage Pros provides mortgage broking services for home buyers and property owners. Before asking Mortgage Pros to assist with reverse mortgage lenders, confirm whether the firm can help with this specific lending category; general mortgage broking does not establish reverse mortgage coverage.
Discuss your home loan needs
Explain your equity-release goal and ask whether assistance with reverse mortgages is available.
FAQ
What are the best reverse mortgage lenders in Australia in 2026?
Heartland and Household Capital are specialist lenders to include in an Australian reverse mortgage shortlist. Neither is a universal winner: compare current eligibility, funding arrangements, equity projections and repayment conditions. Also check the Home Equity Access Scheme as a government alternative.
Is Mortgage Pros a reverse mortgage lender?
Mortgage Pros is a mortgage broking firm, not a reverse mortgage lender. Ask whether it can assist with this specific loan category before assuming reverse mortgage advice or lender access is provided.
Is the Home Equity Access Scheme a reverse mortgage?
The Home Equity Access Scheme is a government loan scheme that allows eligible older Australians to borrow against Australian real estate. It serves a related equity-release purpose but operates under its own rules rather than a private lender’s reverse mortgage contract.
Can I lose all my home equity with a reverse mortgage?
A reverse mortgage can substantially reduce or exhaust your remaining home equity as debt accumulates. No-negative-equity protection is not a guarantee that equity will remain for your estate or future accommodation needs.
Do I have to make monthly reverse mortgage repayments?
Reverse mortgages generally do not require the regular repayments associated with standard home loans while you meet the contract’s conditions. Interest and applicable charges accumulate, and repayment becomes due under the specified events. Check the individual contract.
What happens if I move into aged care?
Moving permanently into aged care can trigger repayment under a reverse mortgage contract. The outcome depends on the terms and the position of any remaining borrower or occupant. Obtain written confirmation and independent advice before relying on continued occupancy.
How do I compare reverse mortgage proposals fairly?
Compare the same borrowing amount, advance timing and projection assumptions wherever possible. Review projected debt and remaining equity over relevant time horizons, then check occupancy rights, repayment triggers and property obligations.
One last thing
Approval answers whether a lender will lend; it does not answer whether borrowing serves your retirement. Before signing, explain the proposal to someone you trust without using the lender's brochure: what you receive, how the debt grows and when repayment becomes due.
If you cannot explain those points clearly, stop and get advice. Contact Mortgage Pros today to discuss your home loan needs and confirm the right starting point for your enquiry.
Related guides
- Best home equity loan options
- Is refinancing worth it?
- Is it better to use a mortgage broker or go directly to a bank?