Best overall for straightforward extra repayments: a variable home loan with redraw. Best for everyday cash access: a variable loan with offset and redraw. Best for repayment certainty: a split loan with redraw on the variable portion. This 2026 guide ranks loan structures by borrower need, rather than naming a lender winner without verified product terms.
- The best redraw facility home loans match your repayment habits, access needs and future property plans.
- Variable home loans with redraw suit borrowers making extra repayments who do not need everyday access.
- Offset accounts keep savings separate from the loan; redraw accesses eligible extra repayments already paid in.
- Mortgage Pros suits medical borrowers seeking guidance on redraw home loans and application requirements.
Why this matters
Redraw lets you access eligible extra repayments you have made on a home loan, subject to the lender's terms. It is not a separate savings account, and the balance displayed is not a promise of unrestricted access.
The distinction matters when your emergency savings, future deposit or tax money sits inside your mortgage. Choose the access rules before choosing where to put your spare cash. Mortgage Pros provides home loan advice for borrowers comparing these arrangements, including doctors with changing income patterns.
A redraw feature also cannot rescue an unsuitable loan. In 2026, compare the whole loan: repayment obligations, interest calculation, fees, extra repayment restrictions and the conditions governing withdrawals.
What makes the best redraw facility home loans?
Use these criteria to assess a proposed loan before signing an application:
- Extra repayment flexibility: Check whether you can make additional repayments without restrictions or charges under the proposed terms.
- Access rules: Confirm withdrawal methods, minimum withdrawal requirements, processing arrangements and circumstances that restrict access.
- Available redraw calculation: Ask how the lender calculates the accessible amount and whether it changes as the loan progresses.
- Overall loan suitability: Compare the interest rate, comparison rate, fees and repayment structure together. Redraw is only one feature.
- Cash separation: Decide whether money for emergencies, tax or near-term spending belongs in a separate account instead.
- Future property use: Consider whether the home might become a rental property before making large extra repayments or redrawing for private spending.
A good answer is specific to the proposed loan. A general statement that a lender offers redraw does not establish how your account will work.
Redraw home loan options at a glance
These are configurations to discuss with a broker, not named products or a lender league table. Each serves a different purpose.
| Rank and loan structure | Best for | Standout feature | Key limitation |
|---|---|---|---|
| 1. Variable loan with redraw | Straightforward extra repayments | Extra repayments reduce the outstanding loan balance | Access remains subject to redraw conditions |
| 2. Variable loan with offset and redraw | Everyday cash management | Savings can remain separate from the loan | Offset eligibility, features and fees need checking |
| 3. Split loan with variable redraw | Partial repayment certainty | Fixed and variable portions serve different needs | Fixed-portion restrictions still apply |
| 4. Separate investment-purpose loan split with redraw | Keeping borrowing purposes distinct | Separate records can help trace borrowed funds | Redraw use can change interest deductibility |
1. Variable loan with redraw: best for extra repayments
A variable home loan with redraw suits you when your main aim is to reduce debt through extra repayments. Eligible additional payments reduce the outstanding balance; redraw provides a way to access an amount permitted under the loan terms.
Keep the distinction clear: making an extra repayment and depositing money into a savings account are different transactions. The lender's redraw rules determine what you can later withdraw.
Variable loan with redraw pros:
- Extra repayments reduce the loan balance used to calculate interest.
- You can direct surplus income towards debt reduction.
- Eligible redraw provides access without applying for a separate loan increase.
Variable loan with redraw cons:
- Withdrawal conditions can limit access when you need money.
- Redrawing increases the outstanding loan balance.
- Variable interest rates can change, affecting repayments.
Best for: Borrowers with a separate emergency reserve who want to put surplus cash towards their mortgage.
Before choosing this structure in 2026, ask the lender to explain what happens to available redraw over the loan term. Do not assume every extra dollar remains accessible indefinitely.
Verdict: Buy into this structure for debt reduction, after confirming the access conditions.
2. Variable loan with offset and redraw: best for everyday cash
An offset account is separate from the loan. With a 100% offset arrangement, the eligible account balance offsets an equal amount of the linked loan balance when interest is calculated.
Redraw works differently: it accesses eligible extra repayments already paid into the loan. A loan offering both features lets you choose where to hold money, but you still need to understand each feature's terms.
Variable loan with offset and redraw pros:
- An offset account keeps savings separate from the mortgage balance.
- Eligible offset funds reduce the balance on which interest is calculated.
- You can distinguish everyday cash from deliberate extra repayments.
Variable loan with offset and redraw cons:
- The overall loan terms and account fees need comparison.
- Not every offset arrangement offsets the full eligible balance.
- Easy access to savings requires spending discipline.
Best for: Borrowers who want accessible cash for household spending, irregular bills or income gaps.
Ask which account links to which loan portion. For doctors receiving different income streams, keeping a cash buffer accessible is a separate decision from making permanent progress on mortgage debt.
Verdict: Buy into this structure when separate cash access is the priority and the overall terms suit you.
3. Split loan with variable redraw: best for partial certainty
A split home loan divides borrowing between fixed and variable portions. In a 2-part split, the fixed portion provides repayment certainty during its fixed period, while the variable portion can provide extra repayment flexibility and redraw where offered.
The redraw feature does not automatically extend to the fixed portion. Check each portion separately.
Split loan with variable redraw pros:
- You can fix part of the borrowing while retaining a variable portion.
- Extra repayments can target the variable portion within its terms.
- You can allocate debt according to different repayment priorities.
Split loan with variable redraw cons:
- Fixed-rate terms can restrict additional repayments.
- Changing or ending a fixed arrangement can trigger break costs.
- A small variable portion can limit your extra repayment flexibility.
Best for: Borrowers who want some repayment certainty without placing all borrowing under fixed-rate conditions.
Before choosing a split in 2026, map expected surplus income against the variable balance. Do not choose the split simply because dividing the loan evenly feels balanced; the allocation should reflect your actual repayment plan.
Verdict: Hold until the split proportions and fixed-rate restrictions match your needs.
4. Separate investment-purpose split: best for tracing borrowing
A separate investment-purpose loan split can help keep borrowing for an investment distinct from private borrowing. Where redraw is permitted, the purpose of each withdrawal still matters.
Australian Taxation Office guidance treats the use of redrawn funds as relevant to interest deductibility. The property securing the loan does not, by itself, determine whether the interest is deductible.
Separate investment-purpose split pros:
- Separate loan records can make borrowing purposes easier to trace.
- You can distinguish investment repayments from household mortgage activity.
- Clear records support discussions with your accountant.
Separate investment-purpose split cons:
- Private redraws can create mixed-purpose borrowing.
- Separate accounts do not automatically make interest deductible.
- Additional loan portions require ongoing administration.
Best for: Property investors who need a clear distinction between investment and personal borrowing.
Ask your accountant about the structure before moving money. This is particularly important if you intend to rent out your current home later or use redrawn funds for private expenses.
Verdict: Hold until your broker and tax adviser have addressed the proposed use of funds.
Redraw versus offset: understand where your money sits
The practical difference is ownership and location of the cash. An extra repayment reduces your loan debt; an offset deposit remains in a separate account while affecting the linked loan's interest calculation.
That distinction matters beyond convenience. If you repay debt and later redraw for a private expense, the new use of borrowed money can affect the tax treatment of interest. Withdrawing your own savings from an offset is a different transaction.
Do not treat redraw as a guaranteed emergency account. Read the contractual access conditions and retain cash elsewhere if a withdrawal restriction would prevent you paying an essential bill.
A useful starting rule is simple: separate money you must access from money you intend to commit to debt reduction. Then check whether the proposed structure supports that distinction.
How to check a redraw loan before applying
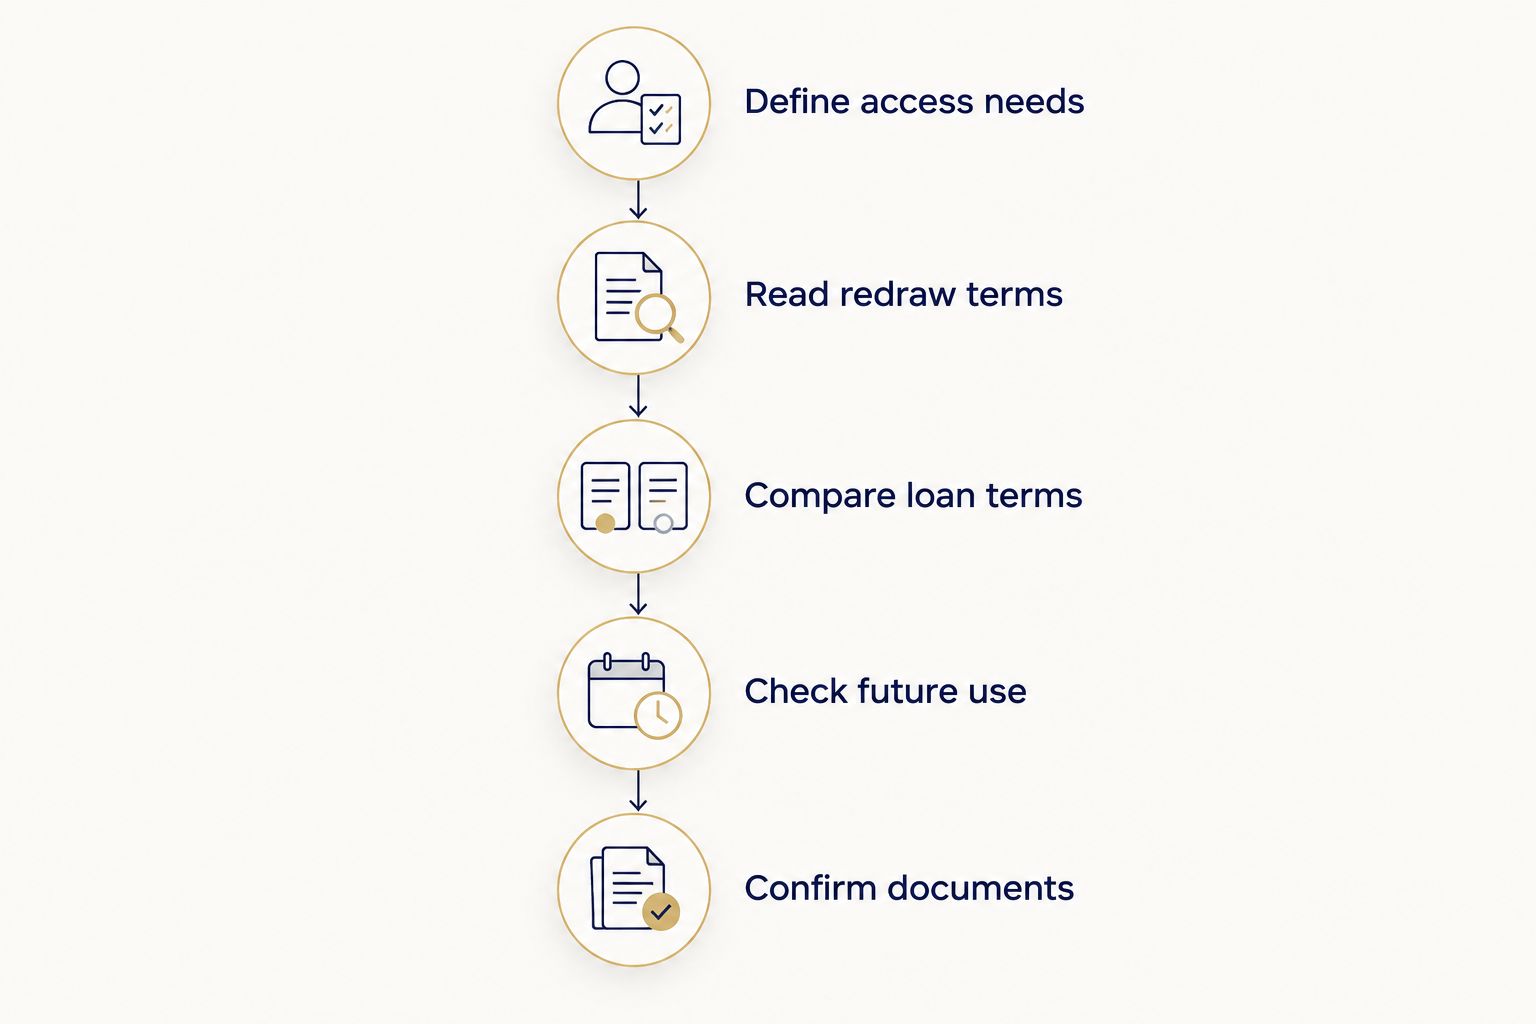
Use this sequence to turn a feature comparison into an application decision. The same checks apply whether you are buying, refinancing or reviewing an existing loan.
Define access needs
List what the money is for: debt reduction, an emergency reserve, tax obligations or a planned purchase. Identify which funds you cannot afford to have restricted.
Read redraw terms
Check eligibility, withdrawal channels, processing, limits and the calculation of available redraw. Ask for the relevant written terms rather than relying on a feature summary.
Compare loan terms
Assess the proposed rate, fees, repayment type and extra repayment rules together. A redraw feature is useful only within a loan that suits your finances.
Check future use
Discuss a possible move, investment purchase or change to rental use before transferring substantial savings into the loan. Get tax advice where borrowing purposes overlap.
Confirm documents
Ask what evidence supports your application and proposed repayment plan. If you are a doctor, explain salary, overtime, on-call earnings and any private or locum income separately.
For a 2026 comparison, request the current documents for the exact loan being proposed. A familiar product name is not a substitute for checking the applicable conditions.
Discuss your redraw loan options
Explain your income, repayment goals and cash-access needs before choosing a loan structure.
How the options are ranked
The ranking prioritises a straightforward match between borrower needs and loan structure: extra repayments first, separate cash access next, then partial rate certainty and investment-purpose separation. It does not rank lender approval prospects or claim a market-wide product winner.
Mortgage Pros is a mortgage broker, not the lender providing redraw. A broker recommendation should explain both why the loan fits and which restrictions you are accepting.
Which redraw home loan should you choose?
Start with a variable loan with redraw if your priority is making extra repayments and you keep emergency savings elsewhere. Compare an offset-linked alternative if accessible cash is central to your household finances.
Choose a split only after deciding how much flexibility you need. If investment borrowing or future rental use is involved, settle the tax and record-keeping questions before moving funds.
For medical borrowers comparing redraw home loans, Mortgage Pros provides home loan guidance. Bring your income evidence, existing loan information and access priorities, then contact us today to discuss a suitable structure.
FAQ
What’s the best redraw facility home loan in 2026?
A variable home loan with redraw is a useful starting point for borrowers prioritising extra repayments. The best fit depends on the exact access conditions, overall loan terms and whether you need separate access to savings.
Is redraw better than an offset account?
Neither is better for every borrower. Redraw accesses eligible extra repayments already paid into the loan, while an offset holds savings separately and reduces the linked balance used to calculate interest.
Can a lender restrict my redraw access?
Yes, redraw access is governed by the loan terms. Check withdrawal limits, processing arrangements and circumstances that allow access to be restricted before relying on the money.
Can I redraw from a fixed-rate home loan?
Redraw on a fixed-rate home loan depends on the specific loan terms. Do not assume a fixed portion has the same extra repayment or withdrawal features as a variable portion.
Does redrawing money increase my mortgage balance?
Yes, withdrawing through redraw increases the outstanding loan balance. That can increase interest compared with leaving the extra repayment in the loan.
Can doctors use overtime or on-call income when applying?
Whether overtime or on-call income is accepted depends on the lender’s assessment and supporting evidence. Provide a clear breakdown of your earnings and ask which income components the proposed lender will recognise.
Does using redraw affect investment loan tax deductions?
Using redraw can affect interest deductibility because the use of the redrawn funds matters. Ask a registered tax adviser before mixing private and investment borrowing or changing how a property is used.
One last thing
Paying ahead does not necessarily mean you can stop making scheduled repayments. Check whether your lender still requires them and how withdrawals affect your repayment obligations.
Before committing, ask these 3 questions: what can I withdraw, what can restrict access, and what repayments must I continue making? General information is not personal financial or tax advice; have the proposed arrangement assessed against your circumstances.
Related guides
- Compare offset home loan accounts
- Home loan lender options for doctors
- Check whether refinancing is worth it