Best overall: a full-documentation lender that accepts your business income. Best for incomplete tax records: an alternative-documentation lender. Best for medical practice owners: a lender with a suitable medical-professional policy. This 2026 guide compares those pathways and your existing lender, so you can shortlist home loans by income fit rather than brand recognition.
- The best home loan lenders for business owners assess sustainable income, business liabilities and supporting documents together.
- Compare full-documentation home loans first when your financial statements and tax returns support the application.
- Alternative-documentation lending changes the evidence required; it does not remove affordability checks.
- Mortgage Pros is a mortgage broking option for business owners seeking home loan advice and approval support.
Why this matters
Your business turnover is not your personal borrowing income. A lender needs to understand what remains after business expenses, how you receive that income and whether existing commitments leave room for mortgage repayments.
A sole trader, company director and medical practice owner can have similar household spending but very different financial records. The right shortlist starts with how your income is assessed, not which bank you already use.
Mortgage Pros helps individual borrowers and investors with home loan advice and approval support. For business owners, the starting point is explaining the income structure before choosing an application pathway.
What makes the best lender for business owners?
Use these six criteria to compare lenders in 2026:
- Income treatment: How does the lender assess salary, business profit, distributions and income movements?
- Evidence requirements: Which tax returns, financial statements, business activity statements and account records are required?
- Business commitments: How are business loans, equipment finance, overdrafts and guarantees treated?
- Ownership structure: Can the lender assess your actual company, partnership or trust arrangements?
- Loan suitability: Do repayment arrangements, offset access and extra-repayment rules suit your household cash flow?
- Approval conditions: What remains outstanding after an initial assessment, including property and document checks?
Do not confuse a lender accepting self-employed applications with that lender accepting your particular income calculation. Ask for the calculation, not just confirmation that business owners can apply.
Business-owner home loan options at a glance
These are ranked lending pathways, not a league table of named institutions. Choose the pathway that matches your evidence and purpose, then compare lenders within it.
| Rank and pathway | Best for | Standout feature | Key limitation |
|---|---|---|---|
| 1. Full-documentation lender | Established businesses with completed financial records | Assessment supported by tax returns and financial statements | Historical records must support the income relied on |
| 2. Alternative-documentation lender | Borrowers whose circumstances require different income evidence | Assessment using the lender's accepted alternative documents | Different documentation does not guarantee eligibility |
| 3. Medical-professional policy lender | Doctors, dentists and surgeons who own practices | Consideration of relevant professional eligibility alongside income | Professional status does not replace affordability assessment |
| 4. Existing lender | Refinancing borrowers checking whether a switch is necessary | A direct benchmark against the current mortgage | Familiarity does not prove the loan remains suitable |
1. Full-documentation lender: best for established businesses
A full-documentation home loan uses financial evidence such as tax returns and business financial statements to assess income. This is the clearest starting point when your records explain the business and support the repayments you want to take on.
Best for: Business owners with completed records and income that can be reconciled across their application documents.
Full-documentation lender pros:
- Tax records and financial statements give the assessment a documented foundation.
- Personal drawings can be distinguished from underlying business earnings.
- The application can address business liabilities alongside income.
Full-documentation lender cons:
- A recent improvement in trading needs evidence beyond an optimistic forecast.
- Differences between documents require explanation rather than selective disclosure.
- A full-documentation application still has to satisfy the lender's credit policy.
Ask whether the lender requires 1 financial year or 2 financial years of completed records, and how it treats changes between them. Neither document period is a universal approval rule. The relevant question is whether the lender's requirements match your evidence.
If profits increased after a difficult period, identify the reason and supporting records. If profits fell, explain the change accurately rather than asking the lender to ignore it.
Verdict: Skip this pathway if the required records are incomplete; otherwise, compare it first.
2. Alternative-documentation lender: best for different income evidence
Alternative-documentation lending assesses income using documents accepted under the particular lender's policy rather than the usual full-documentation package. Depending on that policy, the evidence requested can include business activity statements, business account statements or an accountant's declaration.
It is not a no-check mortgage. The lender must still assess whether the proposed loan is suitable and affordable.
Best for: Business owners with genuine, supportable income who need an assessment pathway based on different documentation.
Alternative-documentation lender pros:
- Creates an assessment pathway where standard documentation does not fit.
- Can bring business trading records into the income discussion.
- Makes the exact evidence requirements a clear shortlisting question.
Alternative-documentation lender cons:
- Accepted document combinations differ between lenders.
- A declaration alone should not be assumed sufficient.
- Incomplete tax records and unpaid tax liabilities are separate issues.
Ask what evidence is mandatory before arranging accountant correspondence. A document prepared without the lender's requirements in mind can leave the central income question unanswered.
Also ask whether completing outstanding records would change your options. Choosing between applying now and waiting for completed accounts should be a deliberate decision, not an assumption that alternative documentation is automatically better.
Verdict: Hold until the lender confirms the exact evidence required and your ability to provide it.
3. Medical-professional policy lender: best for practice owners
Doctors, dentists and surgeons who own practices should ask whether a relevant professional lending policy applies to their circumstances. The assessment still needs to separate professional earnings, practice expenses, ownership arrangements and personal commitments.
Best for: Medical practice owners checking professional-policy eligibility alongside a business-income assessment.
Medical-professional policy lender pros:
- Adds profession-specific eligibility to the lender comparison.
- Encourages a clear distinction between clinical earnings and practice revenue.
- Allows professional status and ownership structure to be discussed together.
Medical-professional policy lender cons:
- Occupation alone does not establish eligibility for a particular concession.
- Practice turnover is not automatically personal income.
- Different income sources still need evidence and reconciliation.
For a doctor combining hospital employment with private practice, identify each income source separately. Do not count practice receipts again if they already fund the salary or distributions included in your application.
Dentist practice owners should also examine how self-employed dentist income is assessed for a home loan. The distinction between practice earnings and money available to the borrower is central to the application.
Verdict: Hold until professional eligibility and the accepted income calculation are confirmed together.
4. Existing lender: best for testing whether refinancing is necessary
Your current lender provides a starting benchmark if you already have a mortgage. Ask what it can change within your existing arrangement and what requires a fresh application or assessment.
Best for: Business owners comparing a mortgage review with a move to another lender.
Existing lender pros:
- Provides a concrete baseline for comparing another offer.
- Lets you check whether existing loan features still meet your needs.
- Helps distinguish a simple review from a larger borrowing change.
Existing lender cons:
- An existing relationship does not guarantee additional borrowing.
- The lender's income policy might not suit your current business structure.
- Staying avoids a comparison, not necessarily an unsuitable loan.
For a 2026 refinance, compare the proposed loan against what you actually use. An offset account matters differently to someone holding household savings than to someone who keeps almost all cash inside a business.
Request written details of the proposed arrangements and conditions. Do not treat a verbal indication as approval for a refinance or equity release.
Verdict: Skip staying by default; keep the existing lender only if the comparison supports it.
How to prepare a business-owner application
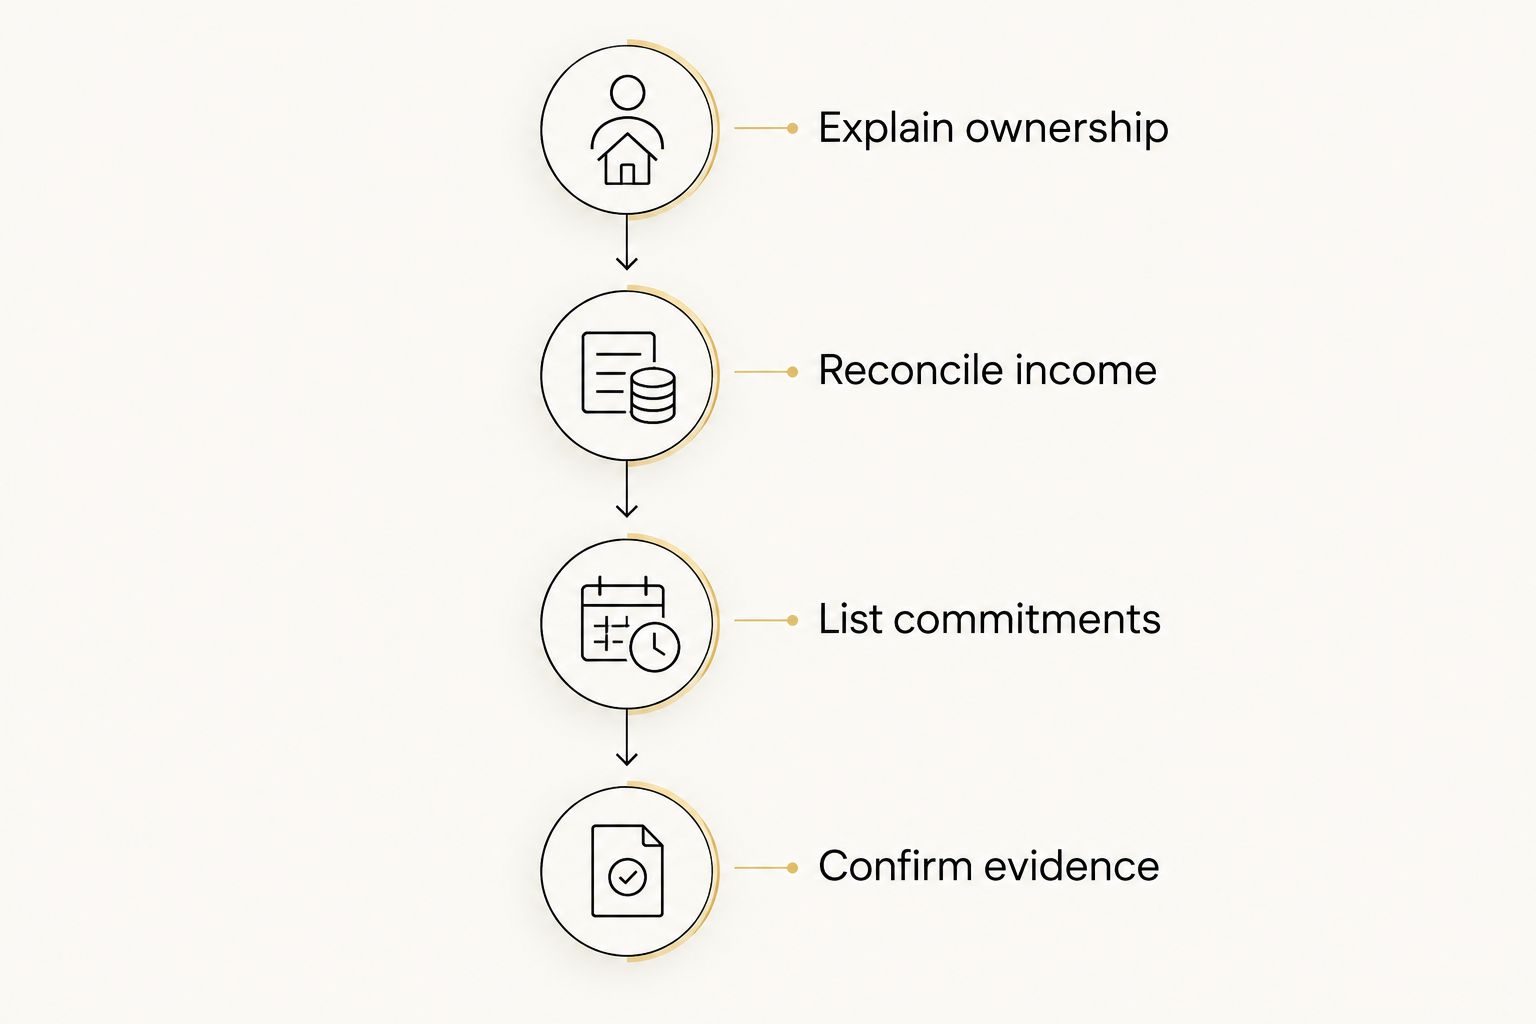
A lender shortlist becomes more useful when every candidate receives the same clear explanation. Prepare the following sequence before submitting applications.
Explain ownership
Identify the borrower, business entities, ownership interests and the people responsible for existing debts. Include relevant companies and trusts rather than describing every structure simply as self-employment.
Reconcile income
Show how business revenue becomes profit and how that profit reaches you. Distinguish salary, distributions and drawings, and flag any amounts already included elsewhere.
List commitments
Record personal debts, business borrowing, credit facilities and guarantees. Explain which entity makes the repayments and provide the evidence requested by the lender.
Confirm evidence
Ask the shortlisted lender which documents it requires and which periods those documents must cover. Resolve conflicting figures before lodging the application.
When comparing mortgage lenders for self-employed borrowers, distinguish general document-preparation principles from country-specific lending rules. Overseas lender comparisons do not establish eligibility for an Australian home loan; the relevant Australian lender must confirm its own requirements.
For your 2026 application, use a short written explanation alongside the documents. Describe material changes such as a new ownership interest, a discontinued contract or a shift from employment to private practice, and support each explanation with records.
Compare the income calculation, not just the loan features
Ask each shortlisted lender or broker to explain the income used in the borrowing assessment. The same set of financial records does not mean every lender will reach the same result.
Focus on these questions:
- Which income sources were accepted, and which were excluded?
- Were any business expenses adjusted in the calculation, and why?
- How were business debts and personal guarantees treated?
- Does the proposed loan depend on documents or conditions still outstanding?
Loan-to-value ratio, or LVR, is another separate test. An 80% LVR means the loan equals 80% of the lender's assessed property value; the remaining 20% of assessed value sits outside that loan. It does not mean your total cash requirement is limited to that proportion, because transaction costs also need consideration.
A larger deposit does not remove income assessment. Equally, a strong business does not remove the need for acceptable security and sufficient funds to complete the purchase.
How these pathways are ranked
Full-documentation lending comes first because completed financial records provide a direct starting point for assessing business income. Alternative documentation addresses a different evidence need, medical-professional policies address a specific eligibility question, and the existing lender provides a refinancing benchmark.
This is a fit-based order, not a claim that one lender approves more applications or offers better terms. Your strongest pathway depends on the documents, ownership structure, commitments and property involved.
Which lender pathway should you choose?
Start with full-documentation lenders when your records support the application. Investigate alternative documentation when there is a specific evidence mismatch, and ask about professional eligibility if you own a medical practice.
Mortgage Pros is a mortgage broking option for business owners seeking home loan advice and approval support. Bring your ownership structure, income records and borrowing goal to the first discussion so the lender shortlist addresses your circumstances.
Discuss your home loan today
Explain your business income and borrowing goal before choosing a lender pathway.
FAQ
What are the best home loan lenders for business owners in 2026?
The best home loan lenders for business owners are those whose income-assessment and documentation policies fit the applicant. Start with full-documentation options when your completed records support the loan, then investigate other pathways for a specific reason.
Can I get a home loan if I pay myself a small salary?
A small salary does not describe your entire financial position as a business owner. Ask whether the lender can assess other business income, taking account of ownership, business commitments and supporting evidence.
Can business owners get a mortgage without completed tax returns?
Some alternative-documentation pathways use other accepted evidence to assess income. Eligibility depends on the lender’s requirements, and you must still demonstrate affordability.
Is an alternative-documentation home loan better than a standard home loan?
Alternative documentation is better suited only when its evidence requirements fit your circumstances. It is not an automatic improvement over a full-documentation application, so compare the complete loan arrangements and conditions.
Does a business loan affect my home loan application?
Business borrowing is relevant to a home loan assessment because repayments and legal obligations affect the overall financial position. Disclose the facility, identify who owes it and provide evidence of how repayments are made.
Can a doctor who owns a practice apply under a medical-professional policy?
A doctor who owns a practice should ask whether the lender’s medical-professional policy covers their circumstances. Professional eligibility and acceptable business-income evidence both need confirmation.
Can Mortgage Pros help with a business-owner home loan?
Mortgage Pros provides mortgage broking services, including home loan advice and approval support. Explain your business structure and borrowing purpose when enquiring so the discussion starts with the relevant income and evidence questions.
One last thing
Money transferred from your business account is not automatically additional income. It might represent earnings already counted elsewhere, a loan or a transfer between accounts. Before applying in 2026, ask your accountant to explain material transfers and make sure the application does not count the same earnings twice.
Related guides
- Home loans for company directors
- Can self-employed borrowers get a loan without tax returns?
- How surgeons combine hospital and private income for a home loan