Best overall starting point: full-documentation lending for directors with established company accounts. Best for directors relying on salary: a lender that accepts their ownership and employment structure. Best for alternative income evidence: alternative-documentation lending. The best home loan lenders for company directors in 2026 are those whose assessment rules match how you earn and document your income—not simply the bank holding your business account.
- The best home loan lenders for company directors match verified income, company ownership and business liabilities.
- Full-documentation lending is the starting point for directors with established accounts and tax records.
- Salary-based assessment requires confirmation that the lender accepts the director’s ownership and employment structure.
- Alternative-documentation lending still requires evidence of income and an assessment of affordability.
- Mortgage Pros provides home loan advice and approval support; it is a mortgage broker, not a lender.
Why this matters
A company director’s payslip does not necessarily tell the whole borrowing story. Ownership, retained profits, business debts and personal guarantees can all affect how a lender assesses an application.
Mortgage Pros is a home loan broker for company directors seeking advice and approval support. You can ask Mortgage Pros to assess your circumstances before choosing where to apply.
This guide ranks assessment pathways rather than declaring an unsupported winner among individual banks. For your 2026 application, use the ranking to identify the right lending route, then compare lenders against your actual documents and requirements.
What makes the best home loan lender for company directors?
Judge a lender on these criteria before comparing loan features:
- Income recognition: How does the lender assess your salary, dividends and share of business earnings?
- Ownership treatment: Does your shareholding change whether the lender treats you as employed or self-employed?
- Evidence requirements: Which financial statements, tax records and supporting documents does the lender require?
- Business commitments: How does the assessment account for company debts, personal guarantees and ongoing expenses?
- Property and deposit fit: Does the proposed security, deposit and loan purpose meet the lender’s requirements?
- Loan suitability: Do repayment arrangements, offset access and other features suit your personal finances?
A lender that accepts your income evidence is a candidate, not an automatic recommendation. The loan must also suit your objectives and remain affordable after your commitments are included.
Company director lending options at a glance
| Rank and assessment pathway | Best for | Standout characteristic | Key limitation |
|---|---|---|---|
| 1. Full-documentation lending | Owner-directors with established financial records | Uses personal and business financial evidence to assess income | Company performance and liabilities require scrutiny |
| 2. Salary-based director assessment | Directors seeking assessment primarily on employment income | Focuses the application on salary where lender policy permits | Payslips alone do not establish eligibility |
| 3. Alternative-documentation lending | Self-employed directors needing another accepted evidence pathway | Uses alternative income documents under lender-specific rules | Alternative evidence does not remove affordability checks |
These are different assessment routes, not interchangeable product recommendations. A bank or non-bank lender can offer more than one route; confirm the current rules for the specific application.
1. Full-documentation lending: best for established owner-directors
Full-documentation lending assesses income using financial records such as tax returns, notices of assessment and business financial statements. It is the strongest starting point when you own part of the company and have records that explain both your personal earnings and the business behind them.
The key question is not just what the company earns. It is how much income the lender accepts for your application after considering ownership, expenses and commitments.
Full-documentation lending pros
- Provides evidence linking your personal earnings to company performance.
- Supports a detailed explanation of salary, dividends and business income.
- Gives the lender records against which to check unusual movements.
Full-documentation lending cons
- Requires preparation of personal and company documents.
- Falling earnings or unexplained inconsistencies need attention.
- Company profit is not automatically accepted as personal income.
Best for: Owner-directors with established accounts and a clear explanation of their income.
For a 2026 application, check which completed financial periods the proposed lender requires. Do not assume an accountant’s draft accounts or the most recent tax return will satisfy every lender.
Ask your broker to identify the income figure being used and explain how it was calculated. A large company turnover figure is not a substitute for this calculation.
Verdict: Buy—choose this assessment route first when your financial records support it, subject to loan suitability.
2. Salary-based director assessment: best for employment-led applications
Salary-based director assessment suits applications where employment income is the proposed basis for borrowing and the lender accepts that treatment. Being a director does not, by itself, establish whether the lender will assess you as a salaried employee or a self-employed borrower.
Your ownership, control of the company and employment arrangements matter. Disclose those details before relying on a borrowing estimate based only on payslips.
Salary-based director assessment pros
- Centres the application on identifiable employment income.
- Suits a focused document review where lender policy permits.
- Avoids relying on company profits you do not need to support borrowing.
Salary-based director assessment cons
- Is not accepted for every ownership structure.
- Does not guarantee exemption from business document requests.
- Salary payments still need to meet the lender’s verification requirements.
Best for: Directors whose employment and ownership circumstances qualify for salary-based assessment.
Ask a precise question: “Will this lender assess my salary on an employed basis given my shareholding and control?” That is more useful than asking whether a lender accepts company directors generally.
If your salary recently changed, provide the supporting records and explanation. Do not assume a new payslip settles questions about whether the income is sustainable.
Verdict: Hold—confirm the lender’s treatment of your directorship before choosing this route.
3. Alternative-documentation lending: best for different income evidence
Alternative-documentation lending provides another evidence pathway for eligible self-employed borrowers. Depending on the lender, supporting material can include business activity statements, business bank statements and accountant-provided information.
It is not a no-evidence loan. The lender still needs to verify the application and assess whether repayments are affordable.
Alternative-documentation lending pros
- Provides a route where standard financial documents do not fit the application.
- Allows accepted business records to support income assessment.
- Creates another option to assess before abandoning a borrowing plan.
Alternative-documentation lending cons
- Evidence requirements differ between lenders.
- Does not solve insufficient income or unaffordable repayments.
- Requires careful comparison of loan conditions and features.
Best for: Self-employed directors with verifiable income who need an alternative to standard documentation.
For 2026, ask for the exact document requirements before preparing an application. “Alternative documentation” describes an assessment approach, not a single set of rules shared by all lenders.
Your accountant’s explanation should agree with the underlying records. An unsupported income declaration is not a substitute for evidence the lender accepts.
Verdict: Hold—consider this route after checking whether full-documentation lending fits.
How the pathways are ranked
Full-documentation lending ranks first as the starting point for owner-directors with established records. Salary-based assessment serves directors whose employment and ownership arrangements qualify, while alternative-documentation lending addresses a different evidence need.
The ranking follows income recognition, ownership treatment, documentation, liabilities and suitability. It is not a lender approval ranking, a claim about application speed or a substitute for an individual assessment.
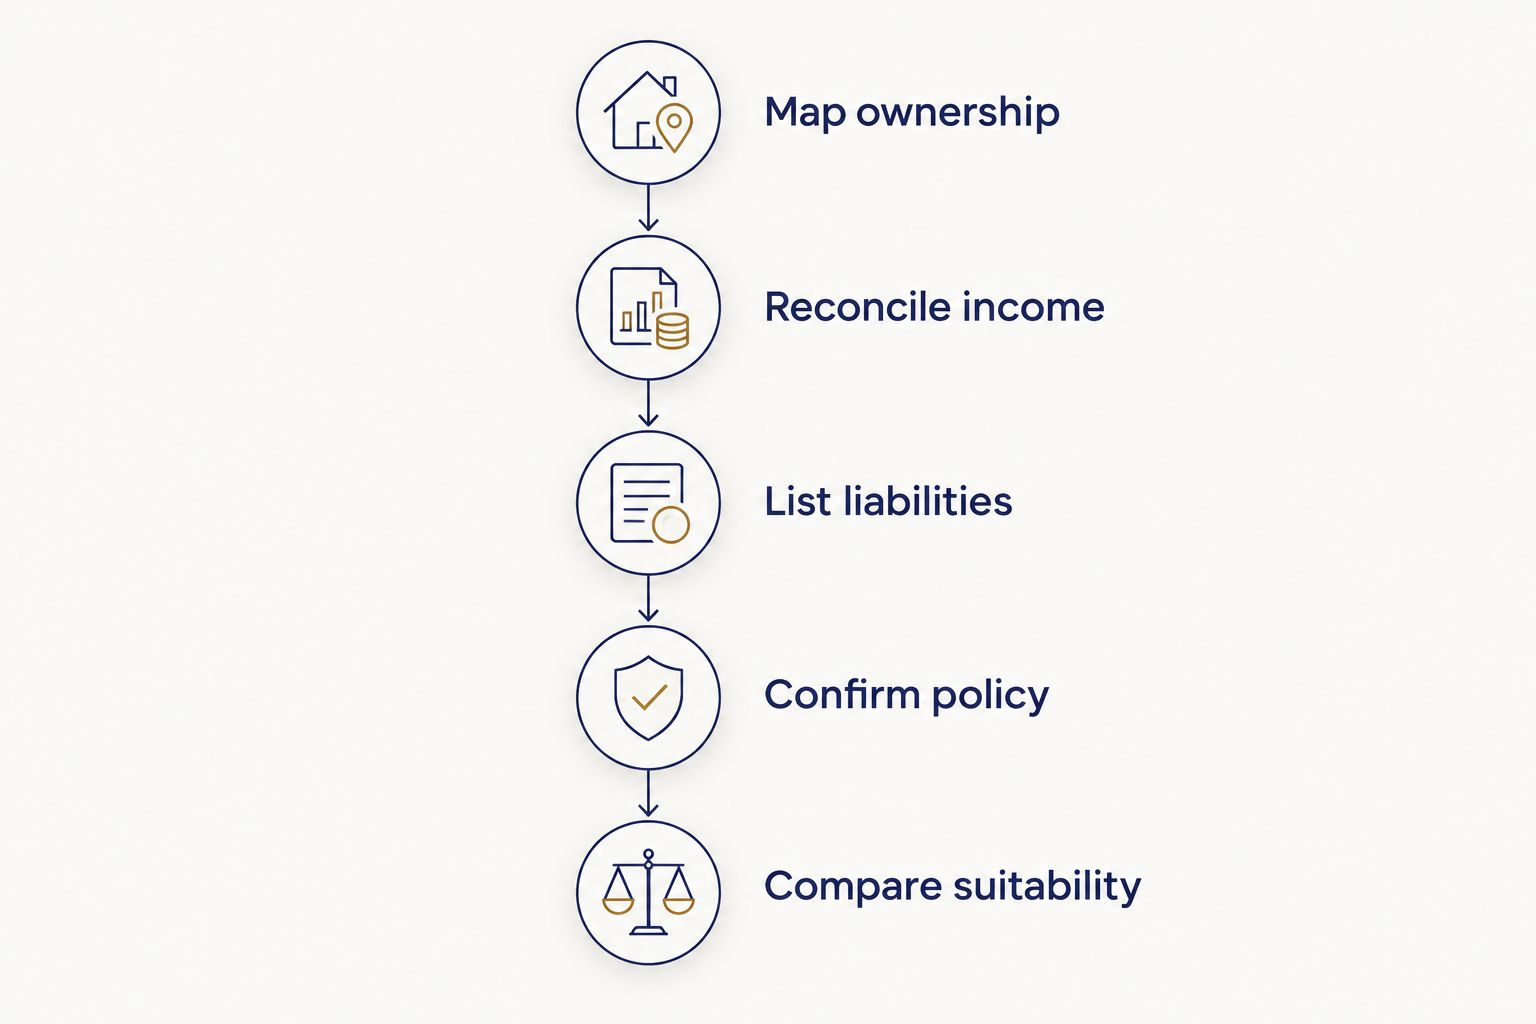
How to build your lender shortlist in 2026
Map ownership
Write down the companies you direct, your shareholdings and the entities that pay you. Distinguish being a director from being an owner: they are separate facts, and both belong in the application discussion.
Include related businesses and relevant trust arrangements. An incomplete structure creates questions later.
Reconcile income
Separate salary, dividends and business earnings, then identify the documents supporting each income source. Ask your accountant to explain inconsistencies between personal tax records and company accounts.
Do not count the same earnings twice. For example, salary paid by a company and the company’s profit require careful treatment because salary is an expense in calculating business profit.
List liabilities
Record personal loans, credit cards, business borrowing and personal guarantees. Identify which entity owes each debt and who makes the repayments.
A debt paid through the business still needs to be disclosed where relevant. The lender decides how it affects the assessment.
Confirm policy
Before submitting an application, confirm the proposed lender’s treatment of your ownership, income and evidence. Resolve questions about recently changed income or incomplete financial records at this stage.
Ask what remains subject to verification. A preliminary borrowing discussion is not unconditional approval.
Compare suitability
Once the assessment pathway fits, compare the loan’s repayments, features, conditions and suitability for your plans. Check how an offset account, redraw facility or fixed-rate structure would work for your circumstances rather than choosing features by name alone.
Keep company working capital separate from your personal deposit planning. Moving business money requires accounting and tax advice as well as a lending assessment.
Questions to ask before you apply
Take these questions to your broker so the recommendation rests on your circumstances rather than a generic lender list:
- Which parts of my income will this lender accept?
- Will my directorship or ownership trigger a self-employed assessment?
- How will company debts and personal guarantees be treated?
- Which documents remain outstanding?
- What assumptions underpin the borrowing estimate?
- What changes would require the application to be reassessed?
Request a clear explanation of the recommended route. You should understand why it fits and what could prevent approval before committing to a property purchase.
If you direct a medical practice, explain your clinical work and business interests separately. Hospital employment, private practice earnings and company distributions are distinct income sources; a professional title alone does not establish how a lender will assess them.
Which home loan pathway should you choose?
Start with full-documentation lending if you own the business and have established records. Check salary-based assessment if your employment and ownership arrangements qualify; consider alternative documentation when the standard evidence route does not fit.
Mortgage Pros provides mortgage broking services, not loan approvals. A lender remains responsible for its credit decision, and a broker recommendation does not guarantee acceptance.
For a 2026 purchase or refinance, contact us today to discuss your directorships, income sources and borrowing plans before submitting an application.
Discuss your director home loan
Explain your company structure, income sources and borrowing goals before choosing where to apply.
FAQ
What are the best home loan lenders for company directors?
The best home loan lenders for company directors are those whose assessment rules fit the borrower’s ownership, verified income and liabilities. Start by identifying whether full-documentation, salary-based or alternative-documentation assessment suits your circumstances, then compare suitable loans.
Can I get a home loan as a company director?
Yes, company directors can apply for home loans. Approval depends on the lender’s assessment of income, expenses, liabilities, credit history, security and other application requirements—not the directorship alone.
Will a lender accept my payslips if I own the company?
Payslips alone do not establish that a lender will assess a company owner as an employee. Disclose your ownership and control so the lender can confirm whether business financial records are also required.
Can retained company profits count towards my home loan?
Retained company profits are not automatically accepted as your personal income. The lender must assess its policy, your ownership and the supporting financial records before deciding what income it accepts.
Can I apply without completed tax returns?
Some alternative-documentation lending pathways use other accepted income evidence. Eligibility and document requirements differ, and the lender still assesses affordability and verifies the application.
Do business loans affect a director’s home loan application?
Business loans can affect a director’s home loan assessment. Disclose relevant debts, repayment arrangements and personal guarantees so the lender can determine their treatment.
Is Mortgage Pros a lender for company directors?
Mortgage Pros is a mortgage broking firm, not a lender. It provides home loan advice and approval support, while the lender makes the credit decision.
One last thing
Company turnover is not your borrowing income. Before discussing a maximum loan amount, ask for a breakdown showing the accepted income sources and the commitments included in the assessment.
That breakdown gives you something useful to check with your accountant. It also makes the next conversation about a suitable loan more productive. Contact us today to discuss your application.
Related guides
- Home loans for company directors: complete guide
- Best lenders for self-employed home loans
- How is self-employed dentist income assessed for a home loan?