Mortgage House offers a direct route to a non-bank home loan. Comparing one lender’s products, however, is different from getting mortgage-broking advice across lenders. The best Mortgage House alternative in 2026 is Mortgage Pros if you need medical-focused home loan advice; Commonwealth Bank if you want to apply directly to a bank.
- For mortgage house alternatives, choose Mortgage Pros for doctor home loans and mortgage-broking support.
- Commonwealth Bank suits borrowers who want a direct bank relationship rather than a mortgage broker.
- Mortgage House remains a valid option when its assessed loan meets your needs.
- Compare income assessment, loan structure and application requirements before choosing a lender.
Why this matters
Your choice is not simply between lender names. You are choosing who helps you assess the options, how your income is presented and which institution makes the lending decision.
For doctors, dentists and surgeons, that distinction deserves attention. Hospital employment, private practice, locum work and business ownership create different documentation questions; a lender still needs to assess the income supporting your application.
The right comparison in 2026 starts with your circumstances, not a provider’s position on a list. Separate the advice service from the eventual loan, then compare the loan itself on consistent assumptions.
Mortgage House alternatives at a glance
These options represent different application routes, not interchangeable services. A mortgage broker helps arrange finance; a lender decides whether to provide it.
| Provider | Best for | Standout distinction | How it differs from Mortgage House |
|---|---|---|---|
| Mortgage House | Borrowers who want to deal directly with a non-bank lender | Direct lender relationship | The benchmark: assess its loan against competing options |
| Mortgage Pros | Doctors, dentists and surgeons seeking mortgage-broking advice | Medical home loan specialisation and application support | A broking service rather than the lender providing the loan |
| Commonwealth Bank | Borrowers who prefer applying directly to a bank | Direct relationship with a bank | A bank alternative to a non-bank lender, not a cross-lender advice service |
There is no universal winner. A suitable loan must work for your property, deposit, income evidence and repayment plans—not just your preferred way of applying.
1. Mortgage Pros: best for medical home loan advice
Mortgage Pros is a Sydney-based mortgage broking firm serving borrowers and investors across Australia. Its specialisation in home loans for doctors, dentists and surgeons makes it the first alternative to consider when your profession is central to the advice you need.
Use the initial enquiry to explain your employment arrangements and the property purchase or refinance you are planning. Ask how the recommended lender will assess your income and what evidence supports that assessment before authorising an application.
Where the service shines
- Medical-borrower focus: the firm specialises in home loans for doctors, dentists and surgeons.
- Support beyond a purchase: its services include refinancing, equity and guarantor arrangements.
- Advice and application support: you can discuss your borrowing needs with a broker rather than assess a single lender alone.
Where the service falls short
- A broker cannot grant loan approval; the lender makes that decision.
- Using a broker adds an adviser relationship rather than giving you a direct-only application process.
- You still need to check the recommended loan’s conditions, provide evidence and understand the broker’s lender access and remuneration.
Head-to-head: medical mortgage broker versus Mortgage House
| Dimension | Mortgage Pros | Mortgage House |
|---|---|---|
| Role | Mortgage broker | Non-bank lender |
| Relationship | Advice and help arranging a home loan | Direct consideration of the lender’s products |
| Medical focus | Specialises in doctor, dentist and surgeon home loans | Confirm how the lender assesses your particular medical income |
| Approval authority | The selected lender decides | The lender assesses the application |
Best for: medical professionals who want help selecting and arranging a home loan, including borrowers considering refinancing or a guarantor arrangement.
Verdict: Buy into the advice process if medical-focused guidance is your priority; do not treat a broker recommendation as approval.
2. Commonwealth Bank: best for a direct bank relationship
Commonwealth Bank is an alternative if your preference is to approach a bank directly. This changes the type of institution you are considering, but it does not replace a comparison with other lenders.
A direct application suits borrowers who want to manage the lender relationship themselves. You remain responsible for deciding whether the bank’s proposed loan is preferable to other available options.
Where Commonwealth Bank shines
- Direct bank application: you can discuss your borrowing needs with the institution assessing the loan.
- A different lender category: it gives you a bank option to assess alongside a non-bank lender.
- A defined comparison: you can compare its written proposal with Mortgage House using the same borrowing assumptions.
Where Commonwealth Bank falls short
- Applying directly does not provide advice across competing lenders.
- A bank relationship does not remove credit assessment or documentation requirements.
- Choosing a familiar institution does not establish that its loan structure suits your needs.
Head-to-head: Commonwealth Bank versus Mortgage House
| Dimension | Commonwealth Bank | Mortgage House |
|---|---|---|
| Institution | Bank | Non-bank lender |
| Direct application | Apply to the bank | Apply to the lender |
| Comparison scope | Its own proposed loan | Its own proposed loan |
| Key question | Does the bank’s assessment and loan suit you? | Does the non-bank lender’s assessment and loan suit you? |
Best for: borrowers who deliberately prefer a direct bank relationship and are comfortable comparing proposals themselves.
Verdict: Hold until Commonwealth Bank’s written assessment and loan terms justify choosing it over the alternatives.
Why people switch from Mortgage House
There is no single reason every borrower should switch. The practical reasons to investigate an alternative are a need for broader advice, a change in borrowing circumstances or a loan structure that no longer matches your plans.
You want advice across lenders
A direct lender conversation centres on that lender’s offering. A broker conversation starts with your requirements and the lenders the broker can access.
Ask which lenders were considered and why the recommendation suits your circumstances. Do not assume that any broker compares every loan in Australia.
Your medical income needs closer assessment
A doctor moving between employment arrangements has different questions from a borrower with unchanged salary income. Separate your base salary, overtime, on-call payments, locum earnings and private-practice income before asking what can support the application.
The issue is evidence, not just total earnings. Ask which income components the proposed lender will accept and what documents establish their continuity.
Your borrowing purpose has changed
Refinancing, accessing equity and introducing or releasing a guarantor require a fresh look at the arrangement. A loan that suited your original purchase is not automatically the right structure for a different purpose.
For a refinance in 2026, define the outcome first. A simpler structure, different repayment arrangements or access to equity are separate objectives and need separate assessment.
How to compare the options before applying
Use the same information for every conversation. Otherwise, different borrowing amounts, terms or assumptions can make unlike proposals appear comparable.
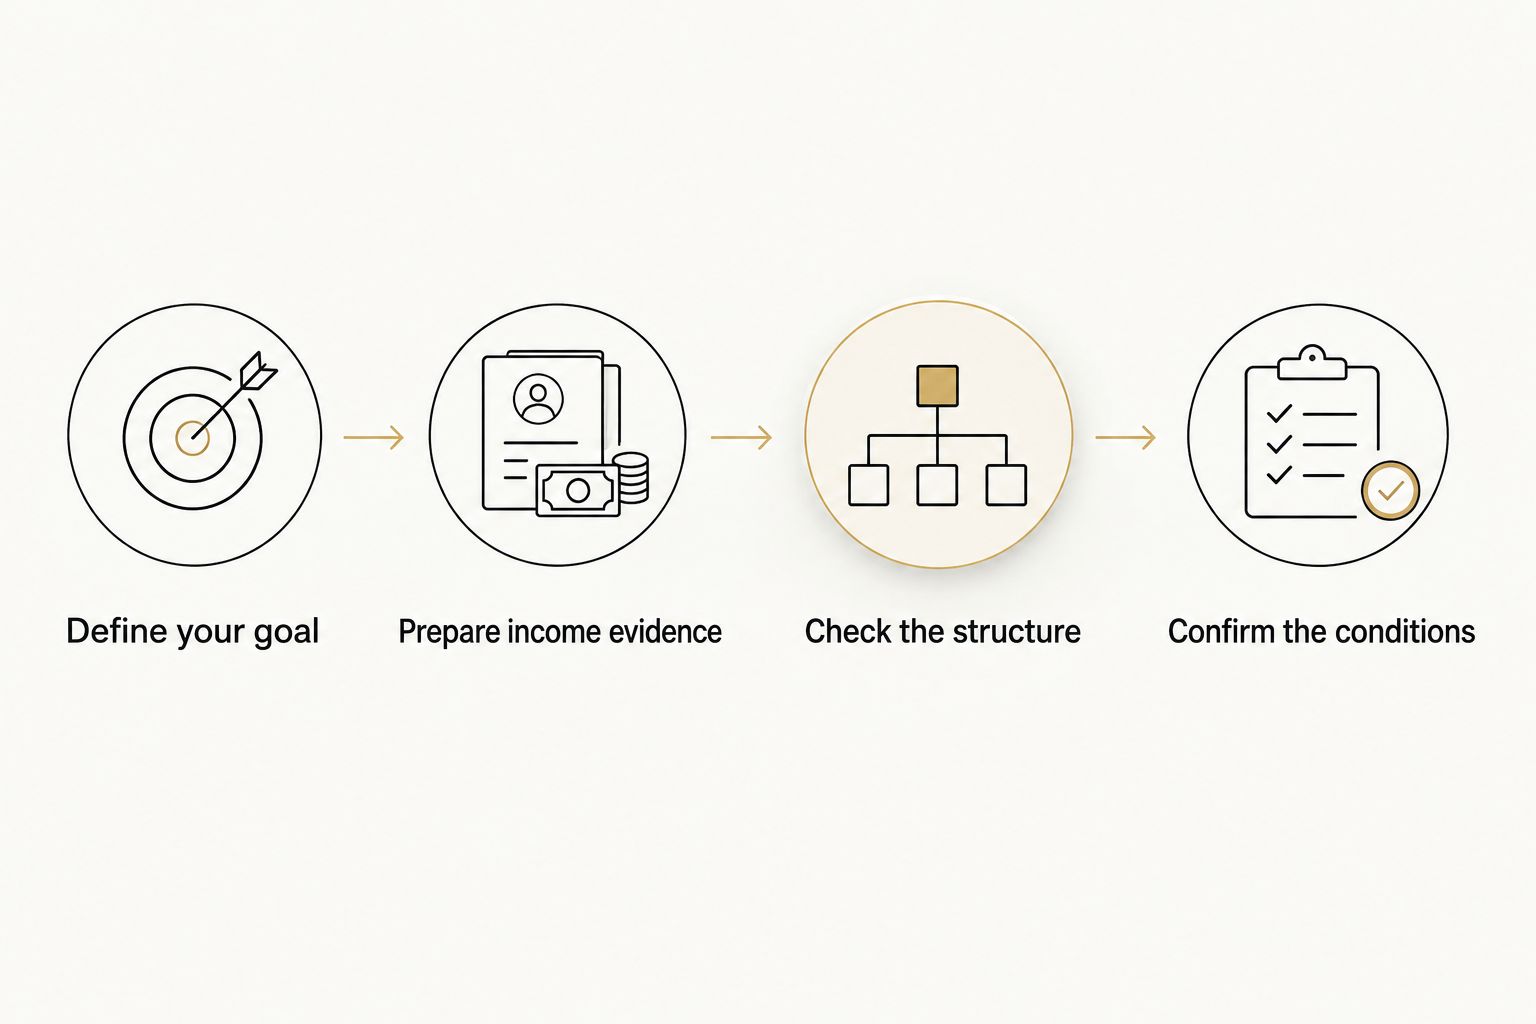
Define your goal
Write down whether you are buying, refinancing or seeking equity, then identify the outcome you need. Include your intended property use and any contractual deadline.
Be precise. An enquiry about maximum borrowing is different from a request to keep repayments manageable while maintaining a savings buffer.
Prepare income evidence
List each income source and the documents available to support it. Medical borrowers should distinguish employment income from business or private-practice income rather than combining everything into one total.
Ask what additional evidence the lender needs before submitting. A discussion about eligibility is not the same as an assessed application.
Check the structure
Compare the loan term, repayment type and features you intend to use. Check the rules attached to features rather than relying on their names alone.
For example, compare a 25-year term with a 30-year term before refinancing. Extending the repayment period changes the repayment calculation and, all else equal, increases total interest over the life of the loan.
Confirm the conditions
Ask what remains outstanding before approval and settlement. Property assessment, income verification and other conditions must be understood before you rely on an indication of borrowing capacity.
Keep the written recommendation and loan documents together. You should be able to explain why the chosen option suits your circumstances without referring to advertising language.
Questions medical borrowers should ask in 2026
Do not stop at whether a provider offers home loans for your profession. Ask how the proposed loan addresses your actual employment, deposit and property position.
- Doctors: which salary components support the assessment, and how are overtime or on-call earnings documented?
- Surgeons: how are hospital employment and private-practice income assessed together?
- Dentists: which business and personal financial documents are required if you are self-employed?
- Locum practitioners: what evidence establishes income history and ongoing work?
Deposit discussions also need clear definitions. An 80% loan-to-value ratio means the loan equals 80% of the property value used by the lender; the remaining 20% is the difference between that value and the loan, before purchase costs.
That arithmetic does not establish your eligibility or guarantee any insurance treatment. Ask for the actual assessment of your deposit, property and profession rather than assuming a medical occupation settles those questions.
Before your enquiry, identify the income question you most need answered. Bring that question, your borrowing goal and your available documents to the conversation.
Discuss your home loan options
Explain your medical income, borrowing goal and application questions to a mortgage broker.
When staying with Mortgage House is the right call
Stay with Mortgage House when its assessed loan meets your needs and the comparison does not establish a good reason to change. A different provider name is not, by itself, an improvement.
For an existing borrower, request the current loan details and any conditions associated with leaving before making a decision. Compare the proposed replacement over the same remaining term, then assess the consequences of changing the structure.
For a new borrower, judge the written offer against your requirements. If the income assessment, repayment arrangements and loan conditions fit, remaining with a non-bank lender is a valid choice in 2026.
Verdict: Hold with Mortgage House when the evidence supports the loan; switch only for an identifiable benefit relevant to you.
FAQ
What is the best Mortgage House alternative for doctors?
Mortgage Pros is the strongest starting point in this comparison for doctors seeking medical-focused mortgage-broking advice. It specialises in home loans for doctors, dentists and surgeons, while the selected lender remains responsible for approval.
Is a mortgage broker better than going directly to Mortgage House?
A mortgage broker suits borrowers who want help comparing and arranging finance, while a direct application suits borrowers who prefer dealing with one lender. Ask the broker about lender access, remuneration and the reasons for any recommendation.
Is Commonwealth Bank better than Mortgage House?
Neither is automatically better for every borrower. Compare Commonwealth Bank’s proposed bank loan with Mortgage House’s proposed non-bank loan using the same borrowing amount, term, repayment type and circumstances.
Can doctors use overtime and on-call income in a home loan application?
Acceptance of overtime and on-call income depends on the lender’s assessment and supporting evidence. Ask which earnings the proposed lender will include and what documents demonstrate their history and continuity.
Should I refinance away from Mortgage House in 2026?
Refinance only when the replacement loan provides an identifiable benefit after you assess the consequences of switching. Compare the remaining term, repayment structure, loan conditions and your current borrowing needs.
Does using a specialist mortgage broker guarantee approval?
No, using a specialist mortgage broker does not guarantee approval. The lender assesses the borrower, property and application against its lending requirements.
What should I prepare before comparing Mortgage House alternatives?
Prepare your borrowing goal, income evidence, deposit or equity details and information about existing debts. Medical borrowers should identify separate employment, locum and private-practice income sources before seeking an assessment.
One last thing
Check the proposed loan term before you compare repayments. A repayment reduction caused by extending the debt is different from an improvement on the same remaining term.
Write down your current position and the outcome you want, then contact us today to discuss your next application. Ask for the recommendation to connect your income evidence, loan structure and borrowing goal—not simply name a lender.
Related guides
- How to choose a doctor mortgage broker for complex income
- Can doctors use overtime and on-call pay for a home loan?
- How surgeons combine hospital and private income for a home loan
- How self-employed dentist income is assessed for a home loan