Yes, you can buy a home as a non-resident in Australia, but your citizenship, visa status and property choice determine whether the purchase is permitted. In 2026, foreign persons are generally banned from buying established homes unless an exception applies; eligible new dwellings and vacant residential land remain possible pathways, subject to approval requirements and conditions.
- Can I buy a home as a non-resident in Australia? Yes, but citizenship and foreign-investment rules determine your options.
- In 2026, foreign persons generally cannot buy established homes unless an exception applies.
- Australian citizens living overseas are not treated as foreign buyers simply because they live abroad.
- Mortgage Pros provides home loan guidance; legal purchase eligibility and lender approval remain separate checks.
Why this matters
Permission to buy and permission to borrow are separate decisions. A lender's willingness to consider your income does not establish that you can legally purchase a particular property.
Start with your buyer classification before choosing a home or submitting a loan application. For the finance assessment, Mortgage Pros provides mortgage broking services to home buyers and property owners across Australia.
Can I buy a home as a non-resident in Australia?
Yes, but “non-resident” is not a single legal category. Living overseas, being a non-resident for Australian tax purposes and being a foreign person under foreign-investment law are different things.
For residential purchases in 2026, Australian Treasury and Australian Taxation Office guidance distinguish foreign buyers from Australian citizens and other exempt purchasers. The following table shows the starting point, not a legal determination of your circumstances.
| Your circumstances | Starting position | Main limitation |
|---|---|---|
| Australian citizen living overseas | Generally exempt from residential foreign-investment approval | Overseas income still needs lender assessment |
| Australian permanent visa holder | Generally exempt from residential foreign-investment approval | Tax treatment and loan eligibility need separate checks |
| New Zealand citizen | Specific exemptions can apply, including for qualifying special category visa holders | Confirm the exemption relevant to your circumstances |
| Temporary visa holder | Generally subject to foreign-investment rules | Established-home purchases are generally prohibited in 2026 unless an exception applies |
| Foreign national living overseas | Generally subject to foreign-investment rules | Property type, approval and purchase conditions restrict your options |
Do not use your tax residency result as your property-purchase eligibility result. Give your conveyancer or solicitor your citizenship, visa details, ownership structure and intended property type before signing.
What counts as an established home?
An established dwelling is broadly an existing residential property that does not qualify as a new dwelling under the foreign-investment rules. Renovating an existing home does not automatically turn it into a new dwelling.
The restriction also matters if you want somewhere to live rather than an investment. A temporary visa, an Australian employment contract or an intention to occupy the home does not, by itself, create an exception.
Australian citizens overseas: broader purchase options
Best for: Australian citizens buying while living or working abroad. Australian citizenship generally removes the residential foreign-investment approval requirement, even when you live overseas.
That gives you a different starting point from a foreign national overseas. You still need to assess state taxes, the contract and financing, but living abroad alone does not put you inside the foreign-buyer established-home ban.
The main financing challenge is documenting income and commitments across countries. Ask the lender how it treats your salary currency, overseas debts, living expenses and evidence of employment before relying on a borrowing estimate.
Foreign buyers: new dwellings and vacant land
Best for: foreign buyers whose proposed purchase satisfies the applicable approval rules. New dwellings and vacant residential land are the main residential pathways to investigate in 2026 when an established-home purchase is prohibited.
These pathways have different obligations. Neither is an automatic approval, and an advertised property description is not enough to establish eligibility.
| Property pathway | Main advantage | Main drawback or condition |
|---|---|---|
| New dwelling | A potential purchase pathway for eligible foreign buyers | Confirm the legal classification and whether individual approval or a developer exemption certificate covers the purchase |
| Vacant residential land | A potential pathway to build a dwelling | Approval generally requires construction within a specified period |
| Established dwelling | An existing home can suit an immediate housing need | Generally prohibited for foreign persons in 2026 unless an exception applies |
Buying a new dwelling
A newly built appearance does not establish that a property qualifies as a new dwelling. Ask your solicitor to check the dwelling's construction, sale and occupation history against the applicable rules.
Some developers hold new dwelling exemption certificates that cover qualifying sales. Your solicitor should confirm whether a certificate actually covers your transaction and what obligations remain with you.
Buying vacant residential land
Vacant land approval generally comes with development conditions. ATO residential foreign-investment guidance commonly requires construction to be completed within 4 years of approval, subject to the conditions in the approval itself.
Land therefore requires a construction plan, not just a purchase deposit. Check planning controls, building feasibility and construction finance before committing; holding the block without meeting the conditions is not a substitute for building.
Why your eligibility and borrowing options vary
Your assessment changes with the buyer, the property and the proposed loan. These factors explain why another overseas buyer's approval does not establish your own eligibility:
- Citizenship and visa status: Australian citizens, permanent visa holders and temporary residents do not share the same foreign-investment starting point.
- Property classification: An established dwelling, a qualifying new dwelling and vacant residential land have different purchase rules.
- Ownership structure: Buying alone, jointly, through a company or through a trust changes the questions your legal adviser must resolve.
- Income evidence: Employment arrangements, income currency and document quality affect the lender's assessment.
- Property location: State and territory duties, foreign-purchaser surcharges and land tax rules require a location-specific check.
- Intended use: Living in the property, renting it out or leaving it vacant creates different financing, reporting and tax considerations.
A strong income does not override a purchase restriction. Equally, legal permission to buy does not establish that a lender will approve the amount you need.
How do I check whether I can buy before making an offer?
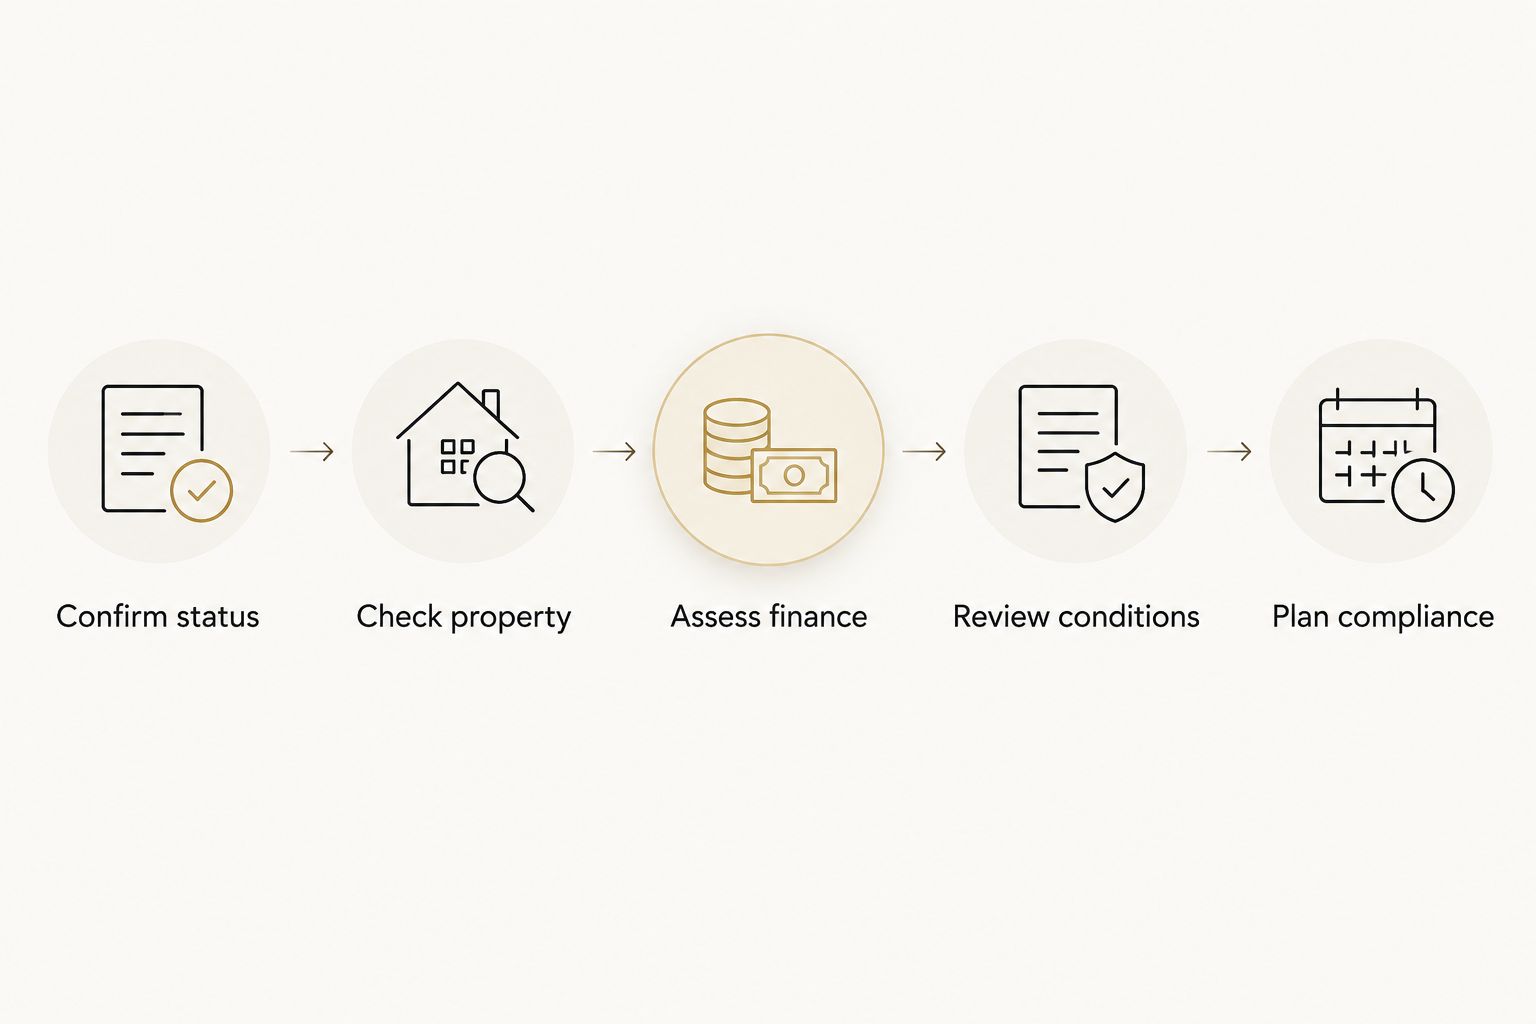
Check the legal pathway first, then match the finance to it. Use this sequence before you make a binding commitment in 2026.
- Confirm status. Give your solicitor your passport, citizenship and visa information. Ask whether you are a foreign person for this purchase and whether an exemption applies.
- Check property. Establish whether the home is an established dwelling, a qualifying new dwelling or vacant residential land. Obtain supporting documents rather than relying on the listing.
- Assess finance. Provide income evidence, debts, living expenses and deposit records. Ask the broker or lender to assess your actual residency and income circumstances.
- Review conditions. Have your solicitor check approval requirements, contract conditions and settlement obligations before you sign. Auction purchases need particular care because contractual protections can be limited.
- Plan compliance. Record approval conditions, registration requirements and any ongoing vacancy or development obligations.
Ask each adviser a separate question: your solicitor confirms the purchase rules, your tax adviser checks tax consequences, and your broker assesses finance options. Keep their answers together so the contract, ownership structure and loan application describe the same transaction.
Mortgage Pros is best for borrowers seeking home loan guidance, rather than a substitute for foreign-investment legal advice. Ask for a finance assessment alongside, not instead of, the legal eligibility check.
Check your home loan options
Discuss your residency, income documents and proposed property before applying for finance.
Can I buy an established home on a temporary visa?
In 2026, temporary residents who are foreign persons generally cannot buy an established dwelling unless a specific exception applies. Do not rely on older guidance suggesting that temporary residents can routinely obtain approval to buy an existing home to live in.
Ask your solicitor to identify the current exception that would permit your particular transaction before proceeding. An Australian job, a substantial deposit or a lender's conditional approval does not replace that requirement.
Can I get an Australian mortgage using overseas income?
Yes, some lenders assess overseas income, but acceptance depends on their lending policies and your circumstances. Your citizenship, visa status, income currency and employment evidence all matter.
Prepare employment contracts, payslips, tax documents, bank statements and details of overseas commitments. Ask which documents need translation or certification and whether the lender adjusts foreign-currency income when calculating borrowing capacity.
For doctors moving to Australia, separate the employment question from the residency question. A hospital contract, locum work or private-practice income needs its own lending assessment; a medical qualification does not override foreign-investment restrictions.
Does buying with an Australian partner change the rules?
Buying with an Australian partner can change the assessment, but the partner's citizenship alone does not settle every case. Some spouse-related exemptions depend on the relationship, the partner's status and the way you hold title.
Have your solicitor confirm the required ownership arrangement before signing. Do not assume that adding an eligible partner to a contract automatically resolves foreign-investment approval, state surcharge or lender requirements.
What obligations continue after settlement?
An approved purchase can carry obligations after you receive the keys. Check your approval letter and the ATO's residential foreign-investment guidance for the transaction rather than treating settlement as the end of the process.
For relevant foreign-owned residential dwellings, vacancy rules use an occupation or genuine rental-availability test of at least 183 days in a 12-month vacancy year. A vacancy return can still be required even when no vacancy fee is payable.
These are separate from ordinary rental and tax obligations. Keep records of occupation, genuine rental availability and any approval conditions, and ask your adviser which register notifications apply.
For vacant land, retain evidence that you have met the construction conditions. In 2026, the approval document remains the starting point for your deadline and any application to vary it.
FAQ
Can I buy a home as a non-resident in Australia in 2026?
Yes, but your citizenship, visa status and property type determine whether the purchase is permitted. Foreign persons are generally prohibited from buying established dwellings in 2026 unless an exception applies.
Can an Australian citizen living overseas buy an existing home?
Yes, Australian citizens living overseas are generally exempt from residential foreign-investment approval. The lender still needs to assess overseas income, debts and repayment capacity.
Can a temporary resident buy a home to live in?
A temporary resident who is a foreign person generally cannot buy an established home in 2026 unless an exception applies. A qualifying new dwelling can provide a different pathway, subject to the applicable approval requirements.
Does mortgage pre-approval mean I have permission to buy?
No, mortgage pre-approval does not establish foreign-investment eligibility. Have your solicitor confirm that you can purchase the specific property before making a binding commitment.
Do I need foreign-investment approval if I pay cash?
Paying cash does not remove foreign-investment restrictions or approval requirements. The rules concern the buyer and property, not simply whether a mortgage is involved.
How long do foreign buyers have to build on vacant land?
Construction generally needs to be completed within 4 years of approval under standard residential vacant-land conditions. Check the deadline and all other conditions in your actual approval document.
Can Mortgage Pros help with the home loan assessment?
Mortgage Pros provides mortgage broking services for home buyers and property owners. Discuss your residency and income circumstances, while using a solicitor to confirm purchase eligibility and contract requirements.
One last thing
A cash purchase still needs the same legal eligibility check. Removing the mortgage does not remove restrictions on who can buy an established home.
Before inspecting properties seriously, write down your citizenship, visa status, intended ownership structure and preferred property type. Give that same summary to your solicitor and broker, then contact the team today to discuss the finance assessment.
This article provides general information, not personal legal, tax or credit advice. Confirm the rules and approval conditions that apply to your transaction before committing.
Related guides
- How long does mortgage pre-approval take?
- Is it better to use a mortgage broker or go directly to a bank?
- How to choose a doctor mortgage broker for complex income