Investment property loan approval in Australia has no fixed turnaround: the timing depends on your lender’s assessment queue, your application documents and the property valuation. For a purchase in 2026, plan separately for formal approval and settlement, because an approved loan still needs loan documents and settlement arrangements completed.
- How long does investment property loan approval take? Timing depends on lender assessment, complete documents and property valuation.
- Mortgage Pros suits property investors seeking mortgage broking support, including doctors with complex income.
- Pre-approval is conditional; formal approval and settlement are separate milestones.
- Confirm your finance deadline before signing, and ask what remains outstanding on your application.
Why this matters
Your contract deadline matters more than a general approval estimate. A lender’s indicative turnaround does not extend your finance clause or change your settlement obligations.
If you are still property hunting, start by understanding how long mortgage pre-approval takes. Pre-approval helps establish a borrowing position, but it does not replace the lender’s assessment of the property you eventually choose.
For your 2026 purchase, ask your broker to work backwards from the contract dates. That separates the date you need a lending decision from the date the lender must be ready to advance funds.
How long does investment property loan approval take?
The approval period runs through several assessment tasks, not a single countdown. Some tasks happen together; others wait until a document, valuation or clarification arrives.
Use these 3 stages to understand where your application stands:
- Application review. The lender checks your identity, income, expenses, debts, deposit and proposed investment borrowing. Incomplete or inconsistent information creates follow-up requests rather than a final decision.
- Property assessment. The lender assesses the proposed security and its value. The valuation method and any access requirements depend on the property and lender.
- Credit decision. The lender considers the application against its credit requirements and resolves outstanding conditions. Ask for written confirmation of the decision and any requirements that remain.
An application being lodged is not the same as an application being ready for a decision. When requesting a timing update, ask whether the lender has everything needed to complete its assessment.
A meaningful estimate for your 2026 application should identify its starting point. An estimate measured from receipt of a complete application is different from an estimate measured from your first enquiry.
What should an approval estimate include?
Ask whether the estimate covers initial assessment, valuation and the final credit decision. Also ask whether it assumes that no further documents will be required.
Keep 2 dates visible: your finance deadline and your settlement date. Your conveyancer or solicitor should explain the contractual consequences if either deadline becomes difficult to meet.
Pre-approval versus formal approval versus settlement
These milestones answer different questions. Do not treat pre-approval as confirmation that a specific investment property is financed.
| Milestone | What it tells you | Best for | Limitation |
|---|---|---|---|
| Pre-approval | A conditional assessment of your proposed borrowing | Planning a property search | Conditions, expiry and property assessment still matter |
| Formal approval | The lender has approved the specified loan, subject to its documented terms | Confirming the lending decision for a purchase | Loan documentation and settlement requirements remain |
| Settlement | Funds are advanced and the purchase is completed | Completing the property transaction | It is not interchangeable with the approval date |
Read the actual approval letter rather than relying on a status label. Lenders use different wording, and the conditions attached to the decision determine what happens next.
An approval also depends on the circumstances assessed. Tell your broker about changes to employment, debts, deposit funds or the purchase before assuming the existing decision still applies.
Why investment loan approval timing varies
The main timing drivers concern the application, the property and the lender. A larger deposit does not remove the need to assess repayment capacity or acceptable security.
- Document completeness. Missing statements, unexplained transactions or inconsistent income information require clarification.
- Income structure. Salary, overtime, locum work, private practice and business income need supporting evidence appropriate to the lender’s requirements.
- Existing financial commitments. Other mortgages, credit facilities and investment properties add information the lender must assess.
- Property valuation. Access arrangements, property characteristics and questions about acceptable security affect the assessment process.
- Lender workload. The queue for assessment is separate from the quality of your application. Ask for the lender’s current position when you apply.
- Borrowing structure. Company or trust borrowers, guarantors and equity-funded deposits introduce additional documents and assessment requirements.
Choose a lender that fits your circumstances, not just one advertising a quick initial response. A fast first response has limited value if the application then needs substantial clarification.
Does a straightforward salary guarantee faster approval?
No. Clear salary evidence removes one potential source of complexity, but the lender still assesses expenses, liabilities, deposit funds and the property.
A salaried borrower can still face outstanding valuation or document requirements. Ask what is holding up your particular file rather than comparing your timeline with another borrower’s experience.
Does pre-approval guarantee formal approval?
No. Pre-approval remains subject to its stated conditions, and the lender still needs to accept the proposed property and confirm relevant application details.
Before making an offer, check whether your pre-approval remains current. Also confirm whether the purchase price, loan amount and ownership structure match what the lender assessed.
Can settlement happen immediately after approval?
Formal approval does not itself complete settlement. Loan documents, identity requirements, any mortgage discharge and coordination between the parties still need attention.
Ask your broker and conveyancer to distinguish outstanding credit requirements from settlement requirements. That makes the next action clear.
How to avoid preventable application delays
Preparation cannot control a lender’s queue or guarantee approval. It can reduce avoidable document requests and expose problems before a contract deadline becomes urgent.
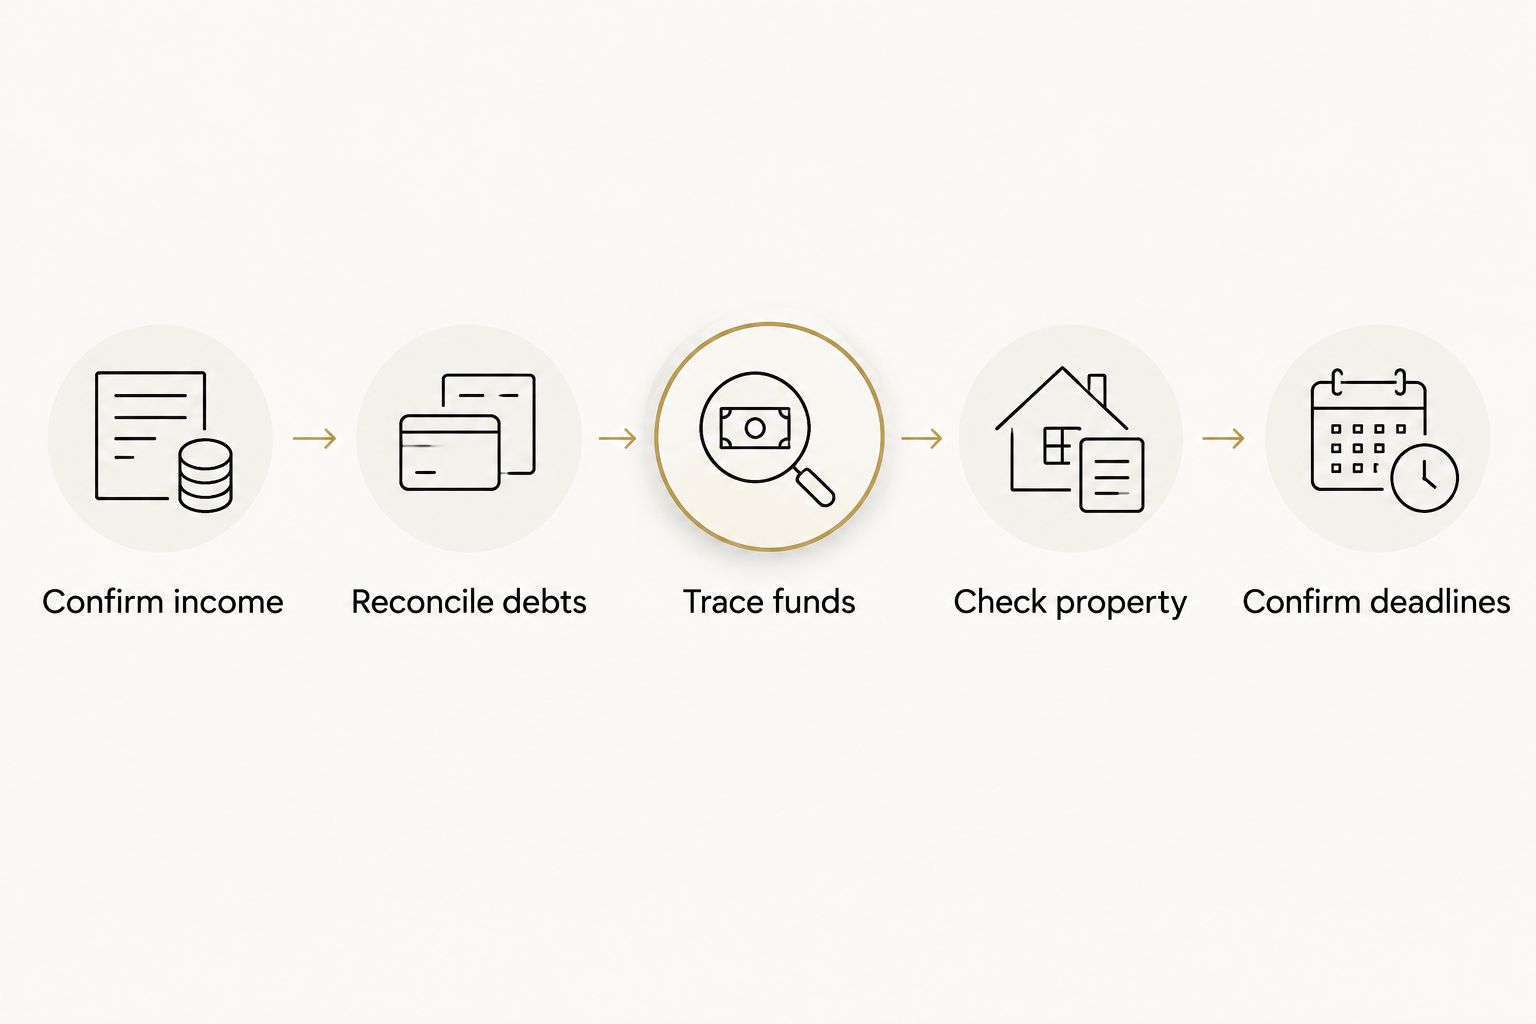
Use these 5 checks before lodging your investment loan application:
- Confirm income. Supply the employment or business evidence requested for your circumstances. Explain changes such as a new role, changed hours or a transition into private practice.
- Reconcile debts. Disclose existing mortgages, credit cards and other commitments accurately. Make sure the balances and limits in the application match the supporting records.
- Trace funds. Show where the deposit and purchase funds are coming from. If equity funds the purchase, explain the existing property and the proposed lending arrangement.
- Check property. Provide the contract and requested rental evidence when available. Tell the broker about features that need closer lender assessment rather than waiting for the valuation to raise them.
- Confirm deadlines. Give your broker the finance and settlement dates and your conveyancer’s details. Ask who will monitor outstanding requirements and communicate any timing problem.
Keep a copy of the document list and track what you have supplied. If the lender asks for something again, establish whether it needs an updated document, a different format or an explanation of the original information.
Respond to the actual request, not just the document name. A bank statement does not resolve a question about an unexplained transfer unless you also explain the transfer and provide any requested evidence.
Property valuation and inspections are different jobs
A lender’s valuation supports its lending decision. A building or pest inspection examines different property risks and does not replace that valuation.
For a residential investment purchase in 2026, coordinate inspection access with the selling agent while your broker follows the lender’s valuation requirements. Keep each booking and its purpose separate so an inspection report is not mistaken for progress towards credit approval.
Commercial investment purchases require the same distinction: commercial property inspection turnaround times concern the inspection schedule, not the lender’s credit decision or valuation timetable. An inspection booking alone does not establish when finance will be approved.
Ask who needs access, who arranges it and which report remains outstanding. If the lender raises a concern about the property, find out whether it needs clarification, additional evidence or a different lending approach before making further commitments.
Your conveyancer should advise on contractual protections and due diligence. Mortgage assessment and legal advice have different roles; neither replaces the other.
Doctors and other borrowers with complex income
For a doctor buying an investment property, the important timing question is whether the lender has the evidence needed to assess each income source. A base salary, overtime, on-call payments and private practice earnings should not be treated as interchangeable evidence.
Prepare a clear explanation of how you earn your income and supply the documents requested for each component. If you have recently changed hospitals, started locum work or entered private practice, raise that change before the application is lodged.
Mortgage Pros is best suited to doctors and other property investors seeking mortgage broking support. Mortgage Pros provides investment home loan advice, but the lender makes the credit decision and controls its assessment queue.
That is the practical benefit and limitation of using a broker: help preparing and managing the application does not amount to guaranteed approval or a guaranteed decision date. Ask which lender requirements apply to your circumstances and what evidence remains outstanding.
What to do if your finance deadline is approaching
Tell your broker and conveyancer immediately if approval remains outstanding. Waiting for a lender update does not change the contract.
Ask your broker to identify the exact blockage: an assessment queue, unanswered credit question, missing document or valuation requirement. Then ask what action is available and who is responsible for it.
Your conveyancer or solicitor can advise whether to seek an extension and how to manage the finance condition. Do not assume an extension is effective until your legal adviser confirms the position.
Before changing lenders late in the process, ask what work would need to restart. Another application introduces its own assessment requirements; it is not automatically a shortcut.
For a 2026 purchase with fixed contract dates, contact Mortgage Pros today to discuss your application stage, income structure and outstanding requirements. Have the contract dates and your latest lender correspondence ready.
Discuss your investment loan timeline
Share your purchase deadlines and income details to discuss the next application steps.
FAQ
How long does investment property loan approval take in Australia?
Investment property loan approval has no fixed turnaround; timing depends on lender assessment, complete documents and the property valuation. Ask for an application-specific estimate that distinguishes formal approval from settlement.
Is an investment property pre-approval enough to buy at auction?
Pre-approval is not a guarantee of finance for an auction purchase. Obtain legal advice about the auction contract and confirm the lender’s outstanding conditions before bidding.
What usually holds up an investment loan application?
Outstanding documents, income clarification, valuation requirements and lender assessment queues can hold up an investment loan application. Ask which requirement is blocking your application rather than relying on a general status update.
Can a mortgage broker guarantee a faster approval?
A mortgage broker cannot guarantee a lender’s approval date. A broker can help prepare the application, address questions and track outstanding requirements, but the lender controls its credit decision.
Do doctors need extra documents for an investment property loan?
Doctors need documents that support the income being used in the application. Overtime, locum work and private practice income require evidence that matches the lender’s assessment requirements.
What happens if my investment property valuation is lower than expected?
A lower lender valuation can affect the proposed borrowing and deposit requirement. Ask your broker to explain the lending implications and speak with your conveyancer before changing your contractual position.
Should I change lenders if my approval is taking too long?
Changing lenders is not automatically faster because the new lender must assess the application. Compare the existing blockage with the work and requirements involved in starting again.
One last thing
Ask what must happen next, not just when approval is expected. A useful update names the outstanding requirement, the person responsible and the next action.
Before ending your next call, confirm whether the lender is waiting on you, a valuation or its own assessment team. You will leave with a task to complete or a clear reason to wait—not just another estimated date.
Related guides
- How much income do I need for an investment property loan?
- How much equity do I need to buy an investment property?
- How can locum doctors document income for a home loan?