Yes, self-employed borrowers can get a home loan without tax returns in Australia in 2026 if a lender accepts alternative evidence of income. You still need to demonstrate that you can afford repayments; business activity statements, bank statements or an accountant’s declaration are not a way around that assessment.
- Can self-employed borrowers get a home loan without tax returns? Yes, where lenders accept alternative income evidence.
- Low-doc home loans still require income verification, expense checks and a repayment assessment.
- Mortgage Pros provides home loan advice for self-employed borrowers, including doctors with private-practice income.
- Check the lender’s document requirements before submitting an application or committing to a purchase.
Can self-employed borrowers get a home loan without tax returns?
Yes, but alternative documentation must satisfy the lender’s income assessment. Some lenders assess self-employed applications using records other than completed tax returns. The acceptable documents, trading history and assessment method depend on the lender and your circumstances.
The decision is not simply whether a lender offers a low-doc loan. It is whether your available records support the income you need for the proposed borrowing. Start with the document requirements when comparing lenders for self-employed home loans, rather than assuming every lender assesses business income the same way.
| Application route | Best for | Main advantage | Main limitation |
|---|---|---|---|
| Standard documentation | Borrowers with completed tax returns and supporting financial records | Gives the lender an established record of declared income | Historical results might not reflect current trading |
| Alternative documentation | Borrowers whose income can be supported without completed tax returns | Allows consideration of other business records | Accepted evidence and eligibility differ between lenders |
| Wait for updated records | Borrowers whose current evidence does not support the application | Creates time to resolve gaps or inconsistencies | Delays the purchase or refinance application |
These are application approaches, not approval promises. A lender can accept your document type and still decline the loan because of affordability, credit history or the property offered as security.
Why this matters
A missing tax return and an unaffordable loan are different problems. Alternative documentation can address the first; it cannot solve the second.
For your 2026 application, establish why the tax returns are unavailable before choosing a lender. Recently completed trading, an accountant finalising accounts and overdue lodgements require different conversations. Do not treat a low-doc application as a substitute for meeting your tax obligations.
What documents can replace tax returns?
No single document replaces tax returns across every lender. Your broker needs to identify an acceptable evidence package, then check whether the figures tell a consistent story about your business and personal income.
Business activity statements
Business activity statements, or BAS, help show reported business activity over the periods covered. A lender that accepts BAS can use them as part of its assessment, alongside other required records.
The limitation is important: turnover is not your take-home income. Wages, rent, supplies and other operating expenses affect what remains available to service a home loan. Strong sales alone do not establish borrowing capacity.
Business bank statements
Business bank statements show money entering and leaving an account. They can help explain trading patterns, recurring receipts and business expenses where the lender accepts this evidence.
Account deposits need context. Transfers between your own accounts, borrowed funds and one-off receipts are not automatically recurring trading income. Keep explanations and supporting records for transactions that would otherwise distort the picture.
Accountant’s declaration
Some alternative-documentation pathways accept an accountant’s declaration as part of the income evidence. The lender determines the required wording, supporting information and accountant eligibility.
An accountant’s letter is not an approval certificate. Your accountant must be comfortable supporting the declared figures, and the lender still assesses your commitments and repayment capacity. Ask for the lender’s requirements before requesting a letter.
Current financial records
Profit-and-loss statements, balance sheets and other current records can help explain how the business is performing. Whether they are sufficient without tax returns depends on the lender’s policy.
Check that reporting periods align before drawing conclusions. Comparing a partial period with a complete financial year without explanation can create a misleading impression of growth or decline.
How do you apply without tax returns?
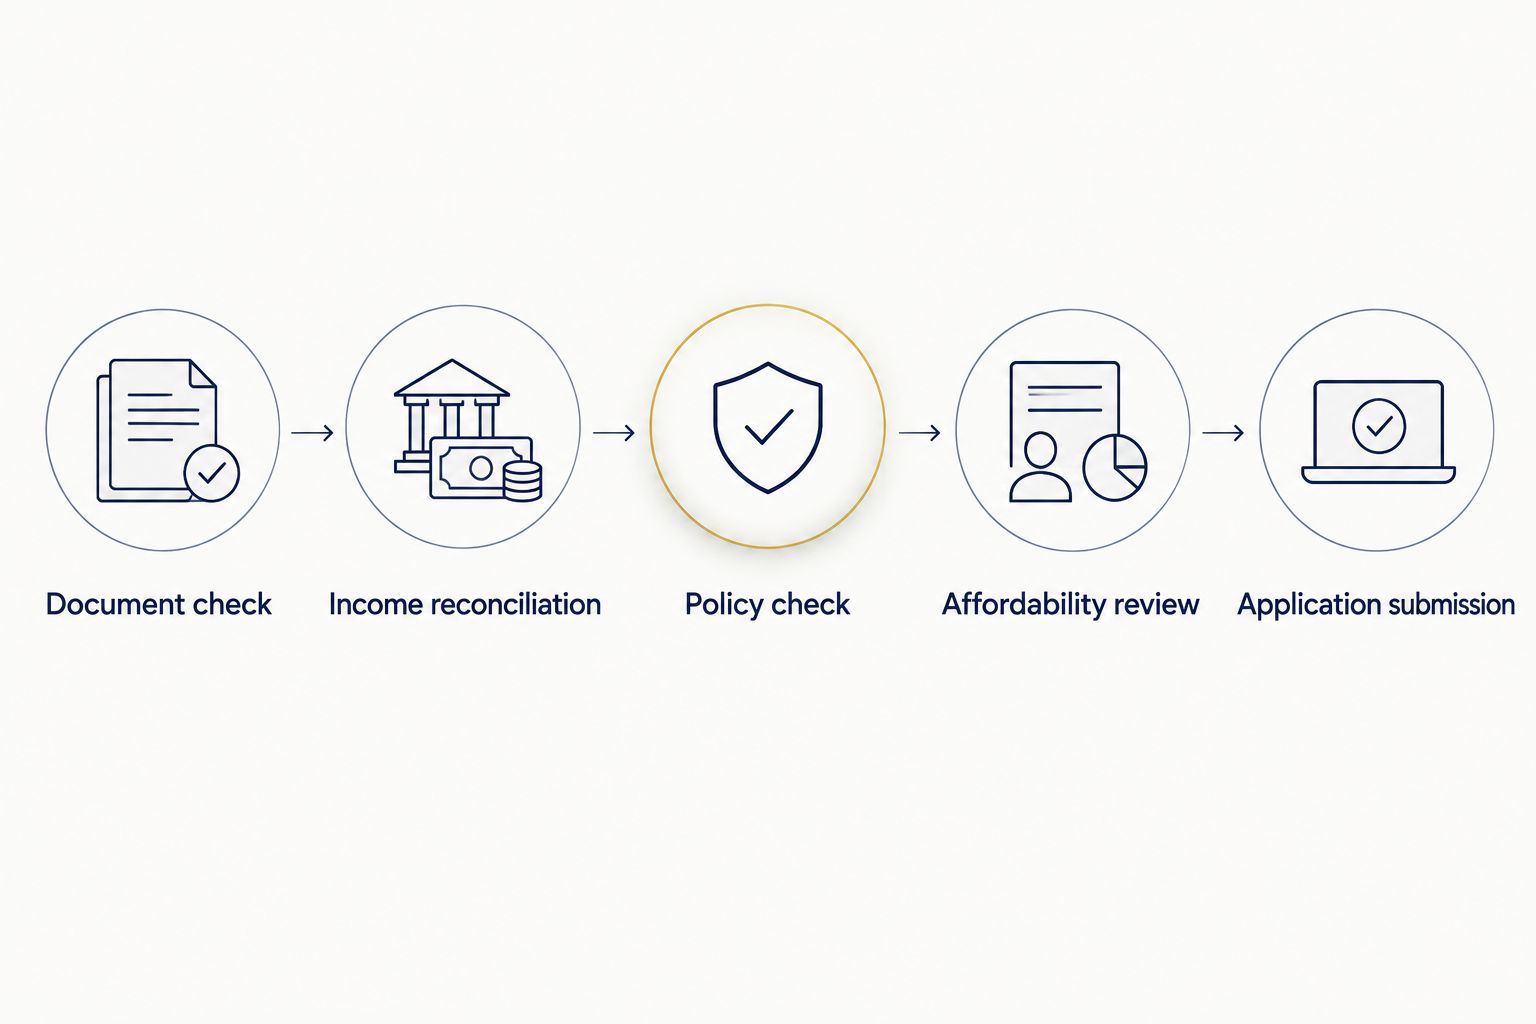
For a 2026 application, use this sequence before submitting a formal loan application. Confirm the evidence pathway first, then assess the borrowing amount. Reversing that order risks building your purchase plans around income the lender will not accept.
- Document check. List the tax returns, BAS, bank statements and financial records you actually have. Identify missing periods and explain why the tax returns are unavailable.
- Income reconciliation. Ask your accountant to explain how business receipts, expenses, profit and personal drawings connect. Flag unusual transactions rather than leaving the assessor to interpret them.
- Policy check. Have your broker confirm whether a lender accepts your evidence, business structure and trading history. Ask what additional documents would trigger further assessment.
- Affordability review. Include personal living expenses, existing repayments, business commitments and dependants. Assess the proposed loan against the income the lender accepts, not gross turnover.
- Application submission. Submit consistent documents and respond to requests for clarification. Keep your broker informed about changes to income, liabilities or the purchase timeline.
This sequence separates document eligibility from borrowing capacity. Passing the policy check means there is a potential assessment route; it does not mean the requested loan amount is approved.
Why approval requirements vary
Different lenders use different policies to decide whether alternative income evidence is acceptable. The same business records do not necessarily produce the same assessment everywhere.
- Available evidence: BAS, statements and financial accounts show different aspects of the business. The lender decides which combination it accepts.
- Trading history: A recently established business provides a different evidence base from an established business with consistent records.
- Business structure: Sole-trader, company and trust arrangements affect how business earnings reach the borrower and which documents explain that relationship.
- Income consistency: Seasonal trading, a major contract ending or a recent expansion requires explanation when assessing ongoing income.
- Existing commitments: Personal debts, business liabilities and living expenses affect the income available for home loan repayments.
- Deposit and security: The amount borrowed relative to the property’s assessed value forms part of the lender’s risk assessment.
Ask your broker to identify the specific policy issue affecting your application. “Self-employed” is too broad a diagnosis to tell you what needs fixing.
What if you are a self-employed doctor or medical professional?
Medical income needs to be separated by source. Hospital salary, private-practice receipts and locum contracting are not interchangeable, even when they all relate to the same profession.
For private-practice income, explain whether receipts belong to you personally or to a separate business entity. Practice expenses, service fees and the way you receive income affect the supporting records needed. A large amount billed does not necessarily equal the income available for your mortgage.
Mortgage Pros is best suited to borrowers seeking home loan advice, particularly doctors with private-practice income. Mortgage Pros provides mortgage broking services; the lender makes the credit decision. Specialist advice does not remove the need for acceptable income evidence or guarantee approval.
For a medical home loan application in 2026, prepare an explanation of each income stream and the documents supporting it. Keep employment income separate from business turnover, then show how the business contributes to your personal finances.
Should you apply now or wait for tax returns?
Apply when the evidence supports the application, not simply because a lender accepts alternative documents. The reason for missing returns matters as much as the proposed application date.
An application now deserves consideration when your records are current, internally consistent and acceptable under a lender’s policy. You also need a clear explanation of your income, expenses and existing commitments.
Waiting deserves consideration when records are incomplete, business and personal transactions are difficult to separate, or your accountant cannot support the income figure. Updated returns might also make it easier to explain your position, although they do not guarantee a better assessment.
Before choosing, ask your broker to compare both pathways using your actual records. If your purchase has a deadline, discuss finance conditions with your conveyancer or solicitor rather than assuming the application will finish in time.
Can I get a home loan with no proof of income?
A home loan without tax returns is not the same as a home loan without proof of income. A lender needs enough information to assess your ability to repay, even when it accepts a different form of evidence.
Treat any suggestion that income does not matter as a warning. A property deposit does not establish that repayments are affordable.
Will an accountant’s letter be enough on its own?
An accountant’s letter is enough only where the lender’s policy accepts it as sufficient income evidence for your application. Other documents and checks can still be required, including evidence of liabilities, expenses and the proposed security.
Obtain the lender’s requirements before asking your accountant to prepare anything. This avoids paying for work that does not answer the lender’s questions.
Does a larger deposit remove the need for tax returns?
A larger deposit does not remove the need to demonstrate repayment capacity. It changes the amount you need to borrow relative to the property value, but it does not explain your ongoing income.
Consider deposit strength and income evidence separately. A strong position in one area does not automatically resolve a weakness in the other.
What should you prepare before speaking with a broker?
Bring a description of your business structure, how long you have traded, your income sources and why tax returns are unavailable. Add the records already available rather than delaying the conversation until every document is perfect.
Your initial checklist should include:
- Business and personal bank statements relevant to the assessment.
- Available BAS and current financial accounts.
- Details of personal and business debts, including repayment obligations.
- Deposit evidence and an estimate of your regular living expenses.
- Your accountant’s contact details and any explanation of unusual trading results.
- Your intended purchase or refinance timing.
Ask Mortgage Pros which self-employed home loan evidence pathway fits your circumstances before making a formal application. Contact us today to discuss your available records and the next steps.
Discuss your income evidence today
Ask which documents support your self-employed home loan application before you apply.
FAQ
Can self-employed borrowers get a home loan without tax returns in 2026?
Yes, self-employed borrowers can get a home loan without tax returns in 2026 where a lender accepts alternative income evidence. Approval still depends on affordability, credit assessment and the lender’s other requirements.
What is the difference between a low-doc loan and a no-doc loan?
A low-doc loan uses alternative income evidence rather than the standard documentation required for that application. Do not interpret the label as permission to borrow without demonstrating repayment capacity.
Can I use business bank statements instead of tax returns?
Some lenders accept business bank statements as part of an alternative-documentation assessment. The statements must support the income assessment, and additional records can be required.
Can a self-employed doctor apply without completed tax returns?
A self-employed doctor can be considered where a lender accepts the available alternative evidence. Private-practice income still needs to be explained after relevant business expenses and commitments.
Can I refinance without providing tax returns?
Refinancing without tax returns is possible where the new lender accepts alternative documentation and you meet its criteria. A record of repayments on your existing loan does not automatically satisfy the new lender’s assessment.
Does being self-employed mean I need a low-doc home loan?
No, being self-employed does not automatically mean you need a low-doc home loan. If your tax returns and supporting financial records meet the lender’s requirements, a standard-documentation application can be appropriate.
Should I lodge overdue tax returns before applying?
Discuss overdue lodgements with your accountant and explain the position to your broker before applying. Alternative loan documentation does not remove your tax obligations or make unresolved records irrelevant.
One last thing
The most useful figure is not the largest amount on your bank statement. It is the income the lender accepts after understanding the business behind it.
Before applying in 2026, ask for a document checklist matched to your circumstances. Resolve the evidence question before relying on a borrowing estimate or committing to a property.
Related guides
- How locum doctors can document income for a home loan
- How self-employed dentist income is assessed for a home loan
- How surgeons combine hospital and private income for a home loan