Instead of comparing loan offers one at a time, organise your doctor home loan refinance to standard loan around equity, income assessment and the total cost of switching. Use this 2026 workflow to compare staying with your lender against refinancing, then ask Mortgage Pros to assess the options before you apply.
- A doctor home loan refinance to standard loan requires fresh assessment; an existing medical-professional concession does not automatically transfer.
- Compare a standard home loan with retaining your current arrangement, including lenders mortgage insurance and switching costs.
- Mortgage Pros provides home loan advice for doctors assessing refinancing, equity and approval requirements.
- Keep the remaining loan term consistent when comparing repayments, and confirm discharge arrangements before settlement.
Why this matters
A doctor home loan is not necessarily a separate legal category of mortgage. The description can refer to a home loan offered with medical-professional eligibility criteria or concessions, including a lenders mortgage insurance waiver where available.
Refinancing means the replacement lender assesses your current circumstances. Your original approval does not establish eligibility for a standard loan, and a previous insurance waiver does not automatically follow you.
Mortgage Pros is best suited to doctors seeking home loan advice and approval support. For a 2026 refinance, the useful question is not whether a standard loan sounds simpler; it is whether the replacement improves your position after costs, features and repayment obligations are considered.
Before you start
- Collect your loan records. Gather statements, your remaining term, fixed-rate expiry details, offset and redraw balances, and information about every property securing the debt. Request a current payout estimate from your lender.
- Prepare your borrower evidence. Have identification, payslips or business financials, employment details, living expenses, liabilities and property information ready. Confirm document requirements with the proposed lender before ordering or submitting anything.
- Check the insurance trap first. A medical-professional lenders mortgage insurance waiver is lender-specific. Moving to a standard loan without enough equity can introduce insurance requirements, even when your original loan did not require insurance.
Use current documents for your 2026 application. Changed employment, private-practice income, parental leave or new debts belong in the assessment from the start, not after you have selected a lender.
Establish your position
Current loan
- Record the outstanding balance, remaining term, repayment type and whether the loan is fixed, variable or split.
- Ask your lender for the payout amount and an explanation of discharge requirements. For a fixed-rate portion, request information about any applicable break costs rather than assuming the statement balance is the settlement amount.
- List the features you actually use: an offset account, redraw, extra repayments or separate loan splits. Record how each feature supports your cash management.
Expected result: you have a clear baseline for comparing a replacement loan, including what you would lose by leaving.
Do not compare offers using repayments alone. A lower repayment can result from extending the term rather than improving the loan's underlying terms.
Equity position
- Identify the proposed refinance amount, including any additional borrowing you intend to request.
- Ask how the proposed lender will value the property. An online estimate or selling-agent appraisal is not a substitute for the lender's accepted valuation.
- Calculate loan-to-value ratio: proposed borrowing divided by the lender-accepted property value, multiplied by 100.
- Check the lender's insurance and lending criteria at that ratio before progressing.
An 80% loan-to-value ratio is a common reference point for standard lending without lenders mortgage insurance, but it is not a universal approval rule. Property type, borrower circumstances and lender policy still matter.
Expected result: you know whether the proposed standard loan fits the lender's equity requirements, rather than relying on the concessions attached to your existing arrangement.
Compare your pathways
Income assessment
- Separate base salary, overtime, on-call payments, locum earnings and private-practice income in your evidence.
- Confirm which income sources the proposed lender accepts and what supporting history it requires. Do not assume all earnings receive identical treatment.
- Declare existing debts, credit limits, dependants and regular expenses accurately. Include liabilities held outside the home loan.
- Check whether your intended borrowing depends on income that the lender has not yet accepted.
For doctors with mixed employment arrangements, lender selection starts with evidence, not the advertised offer. Ask for an assessment of your income structure before making several applications.
Expected result: the proposed loan amount is supported by the lender's assessment of your circumstances, not just by the property's equity.
Loan comparison
Compare these pathways before choosing a standard loan in 2026. No option wins solely because it carries, or removes, a medical-professional label.
| Pathway | Best for | Main advantage | Main limitation |
|---|---|---|---|
| Reprice or restructure the existing loan | Borrowers whose current lender can meet their needs | Keeps the review focused on the existing arrangement | Does not test every alternative lender's assessment or features |
| Refinance to a standard home loan | Borrowers who meet ordinary lending criteria without needing medical concessions | Allows comparison beyond medical-professional offers | Requires fresh assessment and can introduce insurance or switching costs |
| Refinance under medical-professional criteria | Eligible doctors whose position benefits from profession-specific treatment | Keeps relevant medical concessions in the comparison | Eligibility and concessions differ between lenders |
- Request comparable proposals using the same borrowing amount, repayment type and remaining term.
- Compare interest charges, required fees, insurance, exit costs and features across the period you expect to hold the loan.
- Identify any benefits you would surrender, including existing concessions or useful account features.
- Ask the current lender to review its offer, then compare that response with the replacement proposals.
Expected result: you can explain why one pathway suits your circumstances without relying on a headline repayment.
For example, compare a loan with 20 years remaining against another 20-year term before considering a 30-year replacement term. These are comparison examples, not recommended terms: extending repayment over a longer period can increase total interest even when the required repayment falls.
Complete the refinance
Application evidence
- Select the preferred pathway after reviewing the valuation position, accepted income and written loan terms.
- Submit the requested evidence through the broker's or lender's nominated secure process. Check names, liabilities, income figures and property details before submission.
- Respond to assessment questions with documents that explain the issue directly. For mixed medical income, keep employment and business evidence clearly separated.
- Read any approval conditions before treating the application as ready for settlement.
Expected result: you have an assessed application with a clear list of conditions, rather than an assumption that a preliminary discussion equals approval.
Avoid applying to several lenders merely to see who responds first. Begin with a documented comparison and clarify how any credit enquiries will be handled.
Settlement arrangements
- Review the loan contract, repayment instructions, account structure and any conditions attached to the offer. Obtain legal or tax advice where your circumstances require it.
- Confirm who will arrange discharge with the existing lender and what you must sign. Keep making required repayments until the existing lender confirms the payout.
- Agree how offset funds and any available redraw will be handled. Redraw is not a separate deposit account, so do not assume it transfers like cash in an offset account.
- After settlement, check the old loan payout, new loan balance, repayment date and linked accounts. Update direct debits that relied on an account being closed.
Expected result: the old debt is paid out, the replacement loan operates as intended, and you know where your funds and repayments sit.
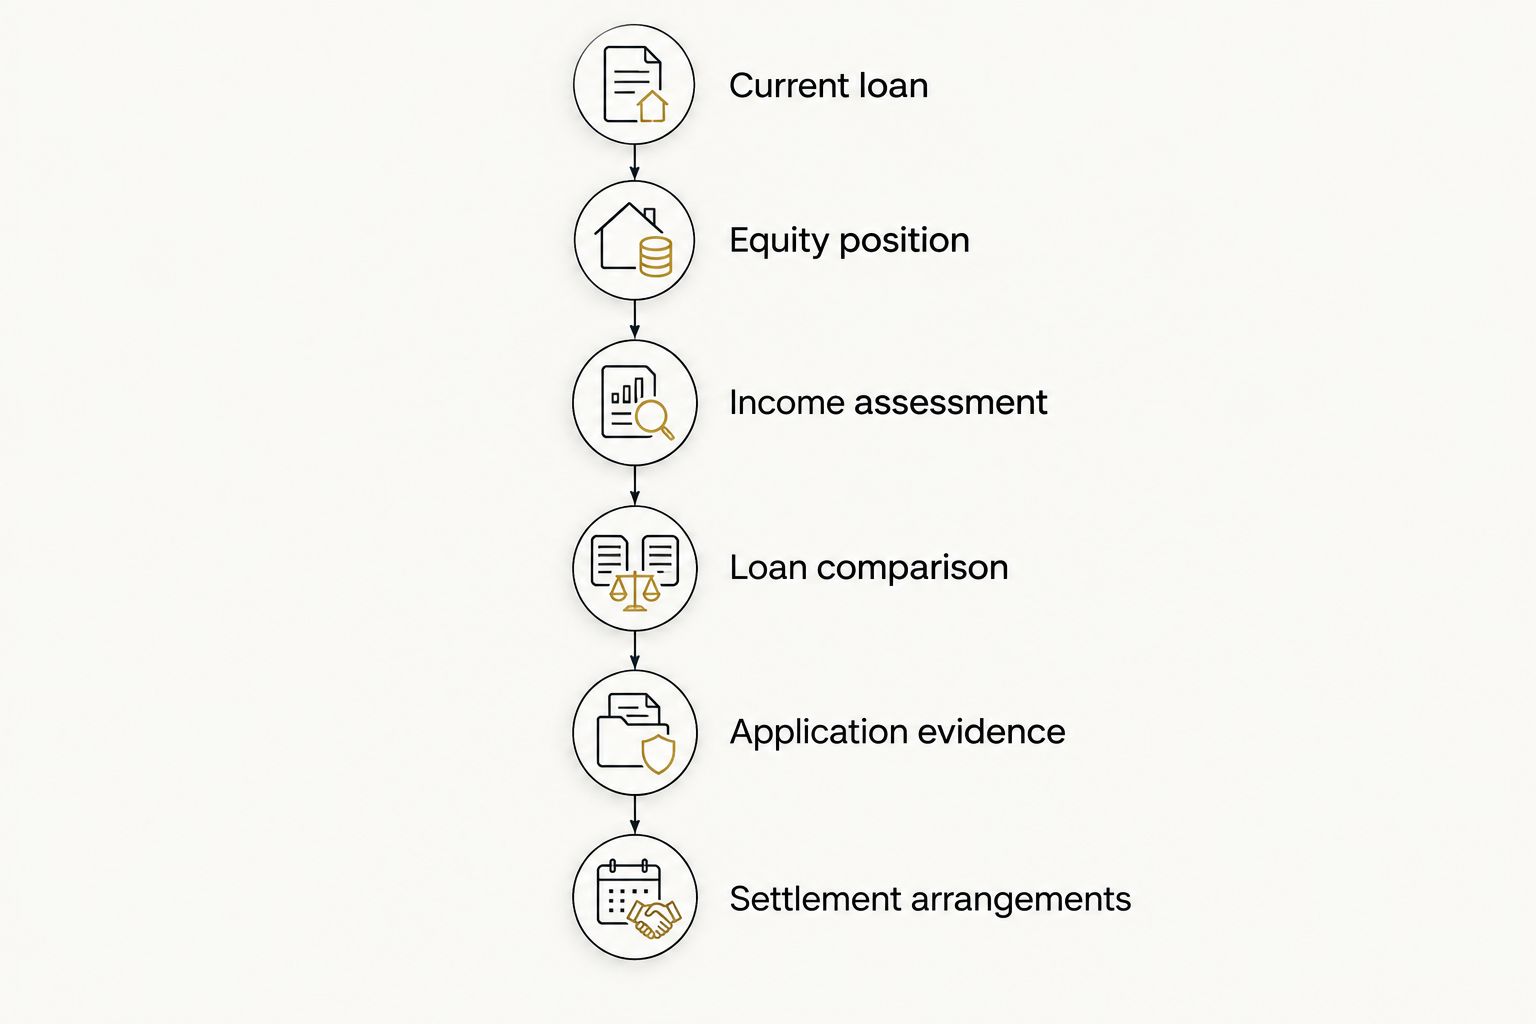
The refinance sequence is Current loan, Equity position, Income assessment, Loan comparison, Application evidence, then Settlement arrangements. Resolve the assessment questions before committing to the replacement.
A second workflow: keep your lender, change the arrangement
A standard-loan review does not always require an external refinance. Ask your existing lender whether it can change the product, review the rate or restructure the loan to meet your needs.
- Explain the change you want, such as different repayment arrangements or a review of features you no longer use.
- Ask whether the change requires a new application, valuation or credit assessment. Confirm whether any medical-professional concession remains relevant.
- Obtain the revised terms in writing, including applicable costs and any features being removed.
- Compare the internal change with the external refinance using the same remaining term and borrowing amount.
Expected result: you know whether an internal change meets your objective without replacing the lender.
The advantage is a narrower change to the existing arrangement. The limitation is that staying does not establish that the current lender is the strongest fit; the external comparison still matters.
Troubleshooting your refinance
The valuation leaves insufficient equity
Ask the lender or broker to explain the accepted valuation and resulting loan-to-value ratio. Recalculate the proposed borrowing before proceeding; options to assess include reducing the requested amount, retaining the existing loan or checking eligibility under medical-professional criteria.
Do not assume another lender will return a higher valuation. Any alternative needs its own assessment.
Overtime or private income is not fully accepted
Confirm the evidence requirement and the reason the income was excluded or reduced. Supply the requested history or supporting documents, then have borrowing capacity reassessed.
A different lender's policy warrants investigation, not an assumption of approval. If your income structure has changed, explain the change before selecting the next pathway.
Fixed-rate break costs change the decision
Request an updated break-cost estimate and check when it applies. Compare refinancing now with reviewing the loan closer to fixed-rate expiry, including the cost of keeping the current arrangement during that period.
Do not proceed using an old estimate. Confirm the figures relevant to the intended payout timing.
The new repayment is lower, but the term is longer
Re-run the comparison over the remaining term of the current loan. Separate any benefit from the loan terms from the effect of stretching repayments over more years.
If a longer term serves a genuine cash-flow need, make that trade-off explicit. A smaller required repayment is not proof of lower total interest.
Offset or redraw funds are unclear
Ask for written instructions covering each balance before settlement. Confirm the destination of offset funds and how the payout calculation treats redraw.
If the property has investment use or mixed-purpose borrowing, obtain tax advice before moving funds or changing loan splits. Refinancing does not erase the history of how borrowed money was used.
Customise your workflow
Make the comparison fit your next decision. If your 2026 refinance also involves equity release, a change to investment use or a move into private practice, disclose that purpose before the lender assesses the application.
Ask Mortgage Pros to compare the standard-loan pathway with retaining relevant doctor home loan concessions. The service provides advice and approval support; the lender still decides whether the application meets its criteria.
Prepare a short enquiry summary: current balance, property details, remaining term, income sources and the reason for refinancing. That gives the discussion a clear starting point.
Discuss your refinance today
Ask for an assessment of your equity, medical income and standard-loan options.
FAQ
Can I refinance a doctor home loan to a standard loan?
Yes, provided you meet the replacement lender’s eligibility and assessment requirements. The lender assesses your current income, debts, property and proposed borrowing; your original doctor-loan approval does not transfer.
Do I need 20% equity to refinance to a standard loan?
Not in every case, but equity affects lender eligibility and potential lenders mortgage insurance requirements. An 80% loan-to-value ratio is a common reference point, not a universal approval threshold.
Will my existing lenders mortgage insurance waiver transfer?
An existing waiver does not automatically transfer to a new lender. Confirm whether the proposed standard loan requires insurance and compare that outcome with any medical-professional pathway you remain eligible for.
Can doctors refinance using overtime and on-call income?
Doctors can present overtime and on-call income for assessment, but the lender determines how much it accepts. Confirm the required evidence and income history before relying on those earnings for borrowing capacity.
Should I refinance my fixed-rate doctor home loan in 2026?
Base the decision on the replacement terms, applicable break costs and your circumstances. Compare switching now with retaining the fixed portion until expiry rather than assuming an immediate refinance is better.
Is a lower monthly repayment enough reason to switch?
No, a lower monthly repayment alone does not establish that refinancing improves your position. Compare the remaining term, total interest, switching costs and features on a consistent basis.
Can Mortgage Pros help me compare standard and doctor home loans?
Yes, Mortgage Pros provides home loan advice and approval support for doctors, including refinancing. Ask for a comparison based on your equity, income structure and reasons for changing loans.
One last thing
Do not discard a useful concession just to remove the doctor-loan label. Equally, do not retain an arrangement solely because it was suitable when you first borrowed. Contact Mortgage Pros today with your current loan details and ask which pathway fits your position now.
Related guides
- How to choose a doctor mortgage broker for complex income
- Can doctors use overtime and on-call pay for a home loan?
- Is a no-LMI loan better for doctors than saving a bigger deposit?