Best overall for eligible buyers with suitable family support: a limited-guarantee home loan. Best without family property security: a gifted-deposit home loan. Best low-deposit alternative: a government-guarantee pathway. The best no deposit home loans for first home buyers in 2026 depend on where your deposit support comes from, not the lender's headline; Mortgage Pros helps individual borrowers with home loan advice and approval support.
- The best no deposit home loans for first home buyers depend on family support, deposit funds and repayment capacity.
- Guarantor home loans suit eligible buyers with suitable family property security, but expose the guarantor to financial risk.
- Gifted deposits avoid family property security, but the lender must accept the gift and your application.
- Government-guarantee pathways are low-deposit options, not a substitute for all purchase funds.
- Mortgage Pros provides home loan advice for borrowers comparing guarantor arrangements and other purchase pathways.
Why this matters
No deposit does not mean no savings, no costs or automatic approval. You still need to establish how you will meet purchase expenses and repay the loan. A guarantee addresses the lender's security requirements; it does not replace income assessment.
Separate these questions before comparing options in 2026:
- Do you lack personal savings, or do you lack any source of deposit funds?
- Can someone provide a cash gift, property security or neither?
- Can you afford repayments without depending on future wage increases?
- What money remains after settlement for unexpected expenses?
A buyer with no personal savings but a genuine cash gift has a different application from a buyer seeking to borrow the entire purchase amount. Treating both as the same situation leads to the wrong shortlist.
What makes the best no deposit home loan?
Judge each pathway against these criteria before choosing a lender:
- Deposit source: Identify whether the application relies on your savings, a gift or additional property security.
- Repayment capacity: Check income, ongoing commitments and living expenses independently of deposit support.
- Family exposure: Understand who puts money or property at risk and the limits of that support.
- Purchase expenses: Account for legal work, inspections, government charges where applicable and moving expenses.
- Exit conditions: Establish how a guarantee ends, or how the loan remains manageable after your circumstances change.
- Loan features: Assess repayment flexibility and account features after eligibility is established, not before.
Mortgage Pros is best for first home buyers seeking mortgage broking advice on guarantor arrangements and home loan approval. Advice helps you distinguish a workable borrowing structure from an attractive headline; lender approval remains a separate decision.
No deposit home loan options at a glance
The ranking below compares borrowing pathways, not named lender products. Each option solves a different deposit problem, and each still requires a suitable loan assessment.
| Rank and option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| 1. Guarantor home loan | Buyers with suitable family property security | Additional security can support borrowing without a cash deposit | The guarantor's property is exposed to the guarantee |
| 2. Gifted-deposit home loan | Buyers whose family can contribute cash | Deposit funds without securing the loan against family property | The gift must be documented and accepted by the lender |
| 3. Government-guarantee pathway | Eligible buyers with a small deposit but no family security | Government-backed support for eligible low-deposit borrowing | A deposit and scheme eligibility are still required |
| 4. Save-first, low-deposit pathway | Buyers without a guarantor or cash gift | A route based on the borrower's own funds | You need time to build the required deposit and purchase funds |
1. Guarantor home loan: best for family property support
A guarantor home loan uses additional security, commonly a family member's property, to support your borrowing. Depending on the lender's assessment and the security available, this structure can support a purchase without a cash deposit. It does not remove your responsibility to make repayments.
Best for: First home buyers with sufficient repayment capacity and a willing guarantor whose property meets the lender's requirements.
A limited guarantee defines the portion of the debt supported by the guarantor. Read the actual guarantee terms rather than assuming that every family-supported loan has the same boundaries.
Guarantor home loan pros:
- Provides a pathway where personal deposit savings are insufficient.
- Uses property security rather than requiring a family cash gift.
- Allows the guarantee's scope to be assessed separately from the borrower's repayment obligations.
- Provides a release question to plan for before settlement.
Guarantor home loan cons:
- Exposes the guarantor to financial loss if the borrower defaults.
- Requires assessment of both the borrower and the supporting security.
- Does not guarantee approval or an automatic release date.
For a guarantor home loan in 2026, ask what debt the guarantee covers, what events allow enforcement and what evidence is required for release. The guarantor should obtain independent legal advice before signing.
Verdict: Choose a guarantor home loan only when both parties understand and accept the property risk.
2. Gifted-deposit home loan: best for cash support without a guarantee
A gifted deposit is money contributed towards your purchase without an obligation to repay the donor. The home loan then uses those funds as part of the deposit, subject to the lender's rules. You have no personally saved deposit, but the purchase itself is not deposit-free.
Best for: Buyers whose family can contribute cash but does not want to offer property as loan security.
Tell the lender whether the contribution is a gift or a loan. Repayable family money is not interchangeable with a genuine gift because it adds an obligation to your finances.
Gifted-deposit home loan pros:
- Supplies deposit funds without a property guarantee from the donor.
- Keeps the donor outside the mortgage security arrangement where no guarantee is given.
- Reduces the borrowing required compared with funding the same purchase entirely through debt.
Gifted-deposit home loan cons:
- Requires someone able and willing to contribute money.
- Does not automatically satisfy a lender's genuine-savings requirements.
- Requires clear evidence about the funds and any repayment expectations.
Document the arrangement before applying. If the donor expects repayments, disclose them and assess affordability with that commitment included.
Verdict: Choose a gifted-deposit home loan when the contribution is genuinely non-repayable and the lender accepts it.
3. Government-guarantee pathway: best for eligible low-deposit buyers
A government-guarantee pathway supports eligible buyers purchasing with a smaller deposit. It is not a cash gift and does not pay your mortgage repayments. You still need the required deposit, purchase funds and lender approval.
Best for: Eligible first home buyers who have some savings but cannot provide family property security.
Check the Australian Government's current home guarantee scheme rules for your circumstances in 2026. Confirm the applicable deposit requirement, property limit, ownership conditions and participating lender requirements before relying on the pathway.
Government-guarantee pathway pros:
- Offers a low-deposit route without a family property guarantee.
- Can address lenders mortgage insurance requirements within the scheme's rules.
- Gives eligible buyers an alternative to waiting for a larger deposit.
Government-guarantee pathway cons:
- Does not solve a complete absence of deposit funds.
- Restricts eligibility and eligible purchases through scheme rules.
- Leaves repayment affordability and lender credit assessment unchanged.
Do not confuse a government guarantee with a first home owner grant or a stamp duty concession. They serve different purposes, and eligibility for one does not establish eligibility for another.
Verdict: Choose a government-guarantee pathway when you meet the current rules and already have the required funds.
4. Save-first pathway: best without family financial support
The save-first pathway postpones the purchase while you build deposit funds and a cash buffer. It is not a no-deposit loan. It belongs in this comparison because it is the alternative when neither a guarantee nor a gift is available.
Best for: Buyers without suitable family support, or buyers whose current budget cannot safely carry the proposed mortgage.
Separate your deposit savings from purchase expenses. A balance that covers the deposit alone does not establish that you are ready to settle.
Save-first pathway pros:
- Avoids exposing a family member's property to your mortgage.
- Gives you time to reduce debts and clarify your borrowing position.
- Creates room to plan for expenses beyond the deposit.
Save-first pathway cons:
- Delays the purchase while you accumulate funds.
- Leaves you exposed to changes in property values and borrowing conditions.
- Does not guarantee that a future application will be approved.
Set a savings target against the purchase you intend to make, then revisit it as your circumstances change. Avoid using a personal loan to make a deposit look stronger without first assessing the additional repayments.
Verdict: Wait and save when buying now would depend on support you do not have or repayments you cannot sustain.
Understand deposit, LVR and guarantee exposure
Loan-to-value ratio, or LVR, compares the loan amount with the lender's assessed property value. A purchase loan equal to that value has a 100% LVR before considering any additional security. A 0% cash deposit does not tell you whether a guarantor supports the application or how purchase expenses are funded.
An 80% LVR means the loan represents four-fifths of the assessed value. The remaining 20% of value is the difference between that value and the loan amount; it is not necessarily cash you originally saved.
Keep these distinctions clear:
- A lender valuation is not automatically the same as your agreed purchase amount.
- Additional guarantor security changes the security assessment, not your household income.
- A smaller loan relative to value does not automatically trigger guarantee release.
- Repaying principal and changes in property value affect equity differently.
Do not plan around an assumed increase in property value. Ask for the actual release conditions and assess a route based on repayments you can make.
How to choose your pathway in 2026
Confirm funds
List your savings, any proposed gift and the money reserved for purchase expenses. Identify which funds are certain rather than promised or dependent on another transaction.
Check support
Establish whether family help is a cash contribution or a property guarantee. For a guarantee, discuss the scope of risk and independent advice before progressing to an application.
Assess repayments
Review income, debts and regular expenses against the proposed borrowing. Deposit assistance does not make an unaffordable repayment affordable.
Verify eligibility
Check the lender's deposit-source requirements and any government scheme conditions that apply. Confirm the property also meets the relevant requirements before committing to a purchase.
Compare loans
Compare loan features and obligations only after identifying an eligible structure. Ask Mortgage Pros to help assess your home loan position rather than choosing from a no-deposit headline alone.
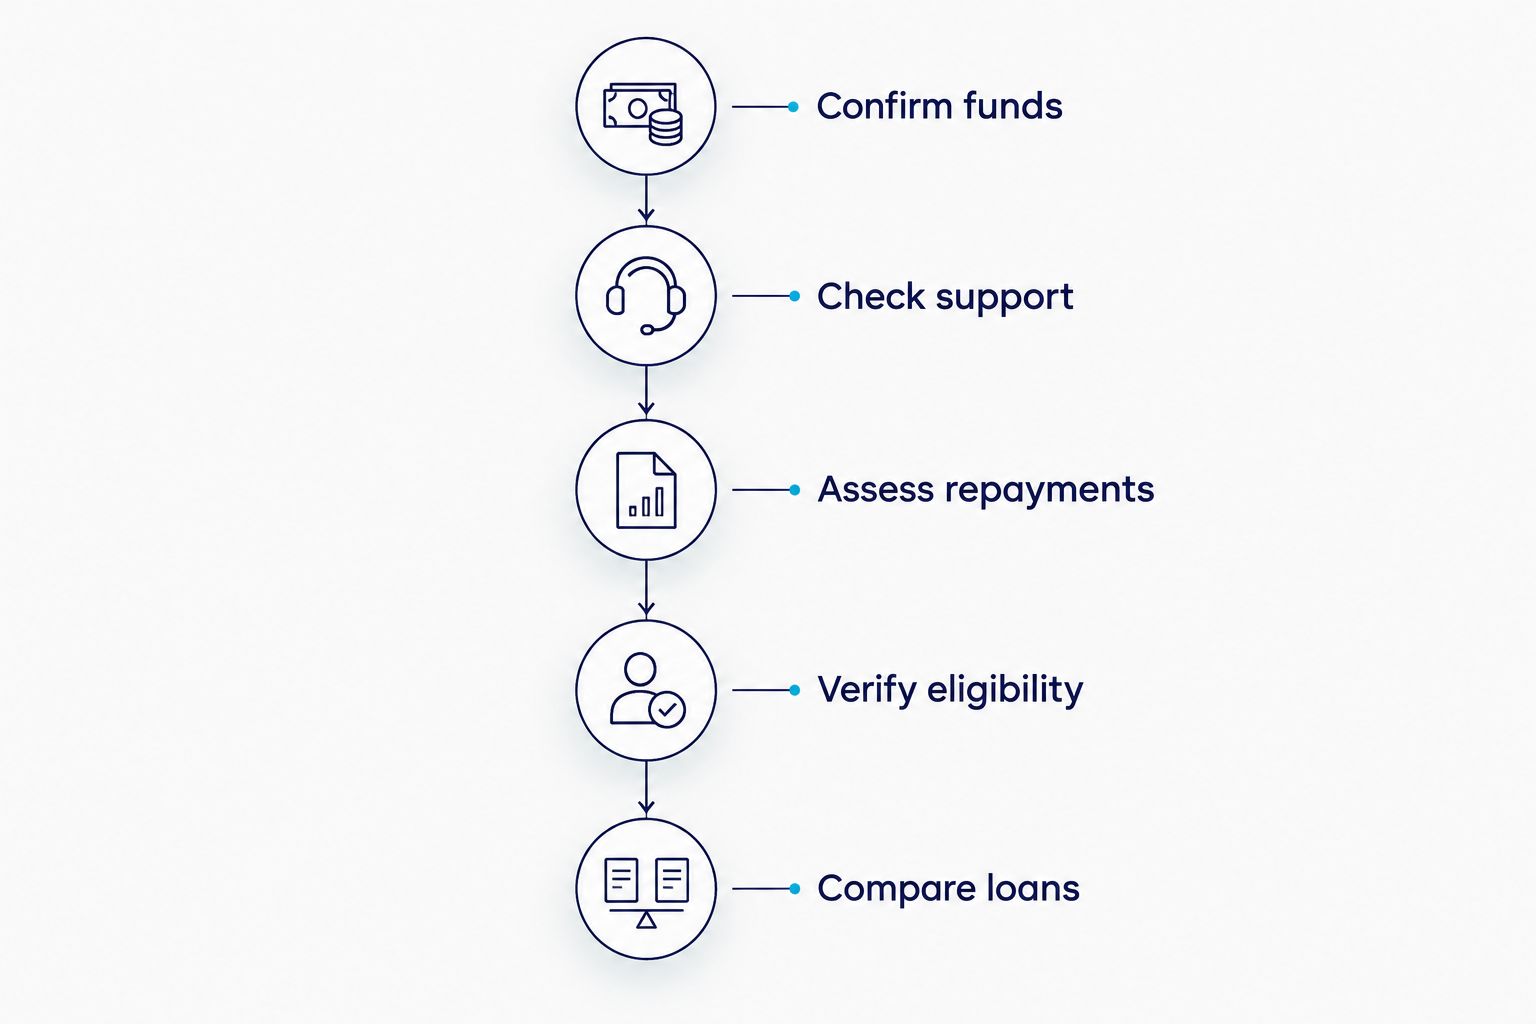
A useful loan comparison starts with a structure you can qualify for and manage. Keep the deposit decision, family risk and repayment assessment visible throughout the process.
Assess your first home loan options
Discuss deposit support, guarantor arrangements and your home loan application.
How the options are ranked
This ranking prioritises the source of deposit support, repayment capacity, family exposure and the ability to understand the arrangement's exit conditions. Guarantor borrowing ranks first only for buyers with suitable family security; gifted deposits rank first when cash support is available instead.
Government-guarantee and save-first pathways address buyers without family security. They are included as alternatives, not presented as genuine zero-deposit products.
Which no deposit home loan should you choose?
For a buyer with no cash deposit, suitable family property support and sufficient income, a limited-guarantee home loan is the starting point. Without family property support, establish whether a genuine gift can fund the deposit.
If neither is available, assess low-deposit eligibility or build savings before purchasing. In 2026, the right answer remains the structure you can qualify for without concealing debt or transferring unexplained risk to family.
FAQ
What’s the best no deposit home loan for a first home buyer?
A limited-guarantee home loan is a starting point for an eligible buyer with suitable family property support and sufficient repayment capacity. A gifted-deposit loan serves buyers with cash support instead. Neither structure guarantees approval.
Can I buy a home with no savings in Australia?
Buying without personal savings requires an accepted source of deposit support or additional security. A genuine gift or guarantor arrangement can address that issue, but you still need to fund purchase expenses and meet the lender’s assessment.
Is a government-guarantee home loan a no-deposit loan?
A government-guarantee pathway is a low-deposit arrangement, not a substitute for all purchase funds. You must meet the applicable scheme conditions and lender requirements.
Is a gifted deposit better than a guarantor home loan?
A gifted deposit avoids placing the donor’s property into a mortgage guarantee when no guarantee is given. A guarantor arrangement instead uses additional security and exposes the guarantor to financial risk. The suitable choice depends on the support available and lender acceptance.
Does a guarantor have to make my mortgage repayments?
The borrower remains responsible for the mortgage repayments. If the borrower defaults, the lender can seek payment under the guarantee according to its terms, which puts the guarantor at risk.
When can a guarantor be released from a home loan?
A guarantor is released when the lender approves removal of the guarantee under its requirements. Loan balance, property valuation and the borrower’s circumstances can affect that assessment; elapsed time alone does not establish release.
Can I use a personal loan as my home loan deposit?
A personal loan creates an additional repayment obligation that must be disclosed to the mortgage lender. It does not replace genuine savings automatically and can reduce your capacity to service the home loan.
What should I prepare before asking a broker about a no-deposit loan?
Prepare evidence of income, debts, expenses, savings and any proposed family contribution. Mortgage Pros can discuss home loan advice and guarantor arrangements, while the lender determines approval.
One last thing
Plan the end of a guarantee before signing the beginning. Ask what must happen for the family property to be released, who requests that assessment and what documents are needed. A no-deposit purchase solves the entry problem; a clear release plan addresses the continuing family obligation.
Related guides
- Low-deposit home loan options
- Comparing offset home loan accounts
- Home loan lenders for self-employed borrowers