Choose Mortgage Pros if you want home loan advice and application support, particularly as a doctor; choose Canstar if you want to research and compare home loans yourself. This 2026 comparison separates personalised mortgage broking from online product research so you can choose the right next step.
- Mortgage Pros vs Canstar is a choice between personalised mortgage broking and self-directed home loan comparison.
- Choose the broker for doctor home loan advice and application support; choose Canstar for independent browsing.
- Neither a comparison result nor a broker recommendation guarantees lender approval.
- Check lender coverage, commercial disclosures and loan conditions before committing to an application.
Why this matters
A home loan comparison and a home loan assessment answer different questions. A comparison helps you identify products to investigate; an assessment considers whether a lender and loan suit your circumstances.
That distinction matters when your income needs explanation. If you are a doctor with hospital employment, overtime or locum work, comparing advertised loan features does not establish how a lender will assess each income source.
For your 2026 decision, start with the problem you need solved. Research calls for comparison tools; questions about eligibility, documents and application preparation call for individual assistance.
At a glance
| Dimension | Mortgage Pros | Canstar |
|---|---|---|
| Best for | Borrowers seeking advice and application support | Borrowers researching home loans themselves |
| Standout feature | Mortgage broking with a doctor home loan specialisation | Online financial product comparison and ratings |
| Initial research | A discussion shaped around your borrowing needs | Self-directed exploration of listed products |
| Personalised assessment | Advice based on your circumstances | Product research does not establish individual eligibility |
| Application support | Assistance securing and managing a home loan | Comparison results are a research starting point |
| Approval control | The lender makes the credit decision | The lender makes the credit decision |
| Pricing model | Request broker remuneration and fee disclosures | Check commercial disclosures and separate lender charges |
| Comparison scope | Ask which lenders are considered | Check which lenders and products are included |
Canstar wins for self-directed initial research
Canstar is the better starting point when your immediate goal is to explore home loans without beginning an advice conversation. You can use a comparison website to build a shortlist and identify the features you want to understand.
This suits a borrower who is comfortable reading product conditions and contacting lenders. Your task at this stage is to learn the differences between loans, not to treat a ranking as a personal recommendation.
Keep your comparison consistent:
- Match owner-occupier loans with owner-occupier loans, rather than investment loans.
- Compare the same repayment type and intended borrowing amount.
- Check whether features such as offset accounts have separate conditions.
- Read the assumptions behind any repayment estimate.
The limitation is personal fit. A product can look attractive in a comparison and still be unsuitable for your income structure, deposit or intended property.
A broker conversation involves sharing circumstances and explaining goals. That is useful when you need advice, but it is a different commitment from browsing products yourself.
Mortgage Pros wins for doctor-focused home loan advice
Mortgage Pros is best for doctors who want personalised home loan advice and application support. The firm specialises in doctor home loans and also assists other borrowers, including property owners and investors.
A doctor comparing loans in 2026 should separate product features from income assessment. Your employment contract, payslips and income history help establish the questions a lender needs answered; your occupation alone does not establish approval.
For example, ask how an application should present:
- Base salary alongside overtime and on-call payments.
- Hospital employment alongside locum or private practice income.
- A recent role change or probation period.
- Existing debts and ongoing financial commitments.
The advantage of individual advice is the opportunity to discuss those details before choosing an application path. A general comparison result does not resolve them.
The trade-off is participation. You need to provide accurate information and supporting documents, rather than simply compare a list of products. Specialist advice also does not mean every doctor qualifies for the same loan conditions.
The broker wins when you need application support
Choose the broking service when your question has moved from which loan looks suitable to how you should apply. Mortgage broking and online comparison are not interchangeable services.
The firm helps borrowers secure and manage home loans, including refinancing, equity and guarantor arrangements. That makes its service relevant when you need help connecting your borrowing objective with an application.
Before engaging a broker, establish the practical scope of assistance. Ask who will explain document requirements, how outstanding questions will be handled and what happens if the lender requests further information.
Canstar remains useful for background research. Its comparison function helps you investigate products, but a comparison result is not evidence that someone has reviewed your documents or prepared your application.
The broker's limitation is equally important: assistance does not remove the lender's assessment. You remain responsible for supplying complete, accurate information, and the lender can request additional evidence.
If you prefer to manage the process yourself, online research followed by direct lender discussions is a valid route. Choose it because you want that responsibility, not because a ranked product appears to guarantee acceptance.
Neither option controls lender approval
This is a tie: the lender decides whether to approve your home loan. A product rating, borrowing estimate or broker recommendation is not a credit decision.
Keep these 3 questions separate:
- Does the loan suit your needs? Consider repayment structure, features and intended use.
- Do you meet the lender's requirements? Your income, commitments, deposit and property matter.
- Has the lender approved the application? Check the written decision and any conditions.
Do not interpret a positive early conversation as permission to make an unconditional purchase commitment. Ask your conveyancer or solicitor about your contractual obligations and confirm the status of finance with the lender or broker.
For a 2026 purchase, verify conditions against your actual transaction. General research cannot account for every property, employment change or document issue.
This shared limitation is not a reason to avoid either option. It is a reason to distinguish research, advice and approval throughout the process.
Pricing: compare disclosures, not assumptions
Neither option wins on cost without examining the relevant disclosures and loan terms. Comparing a broker with a comparison website is not the same as comparing the total cost of competing home loans.
Mortgage brokers can receive lender commissions, and some charge borrower fees. Ask for the actual arrangement before engaging a service; do not assume that the general industry model establishes this firm's terms.
For the broking route, ask:
- Will you charge me a fee, and when would it become payable?
- How are you remunerated if my loan settles?
- Which disclosures explain commissions or other commercial relationships?
- What assistance is included in the engagement?
For the comparison route, read Canstar's commercial disclosures and the explanation of how products are included or displayed. Separately check the lender's loan documentation; website research does not remove loan charges or contractual conditions.
The practical trade-off is between arranging an advice engagement and taking responsibility for research yourself. Neither route establishes a cheaper mortgage by itself.
For refinancing, compare the proposed loan with the cost and conditions of leaving your existing loan. A different repayment figure alone does not establish that switching improves your position.
Both require a check of comparison scope
This is another tie: check the scope before treating either shortlist as exhaustive. Ask a broker which lenders are considered, and check a comparison website's coverage and methodology.
Neither the length of a product list nor the strength of a recommendation proves that every possible loan has been assessed. Your shortlist needs an explanation you can understand.
Use the same questions with either route:
- Which lenders and products were considered?
- What falls outside the comparison?
- Why does the proposed loan fit my borrowing purpose?
- Which conditions still need confirmation?
For a medical borrower, add a specific question about how your income and employment circumstances were considered. A broad product comparison and an occupation-specific assessment serve different purposes.
If you cannot explain why a loan made the shortlist, pause before applying. Ask for clarification rather than filling the gap with a favourable ranking or a familiar lender name.
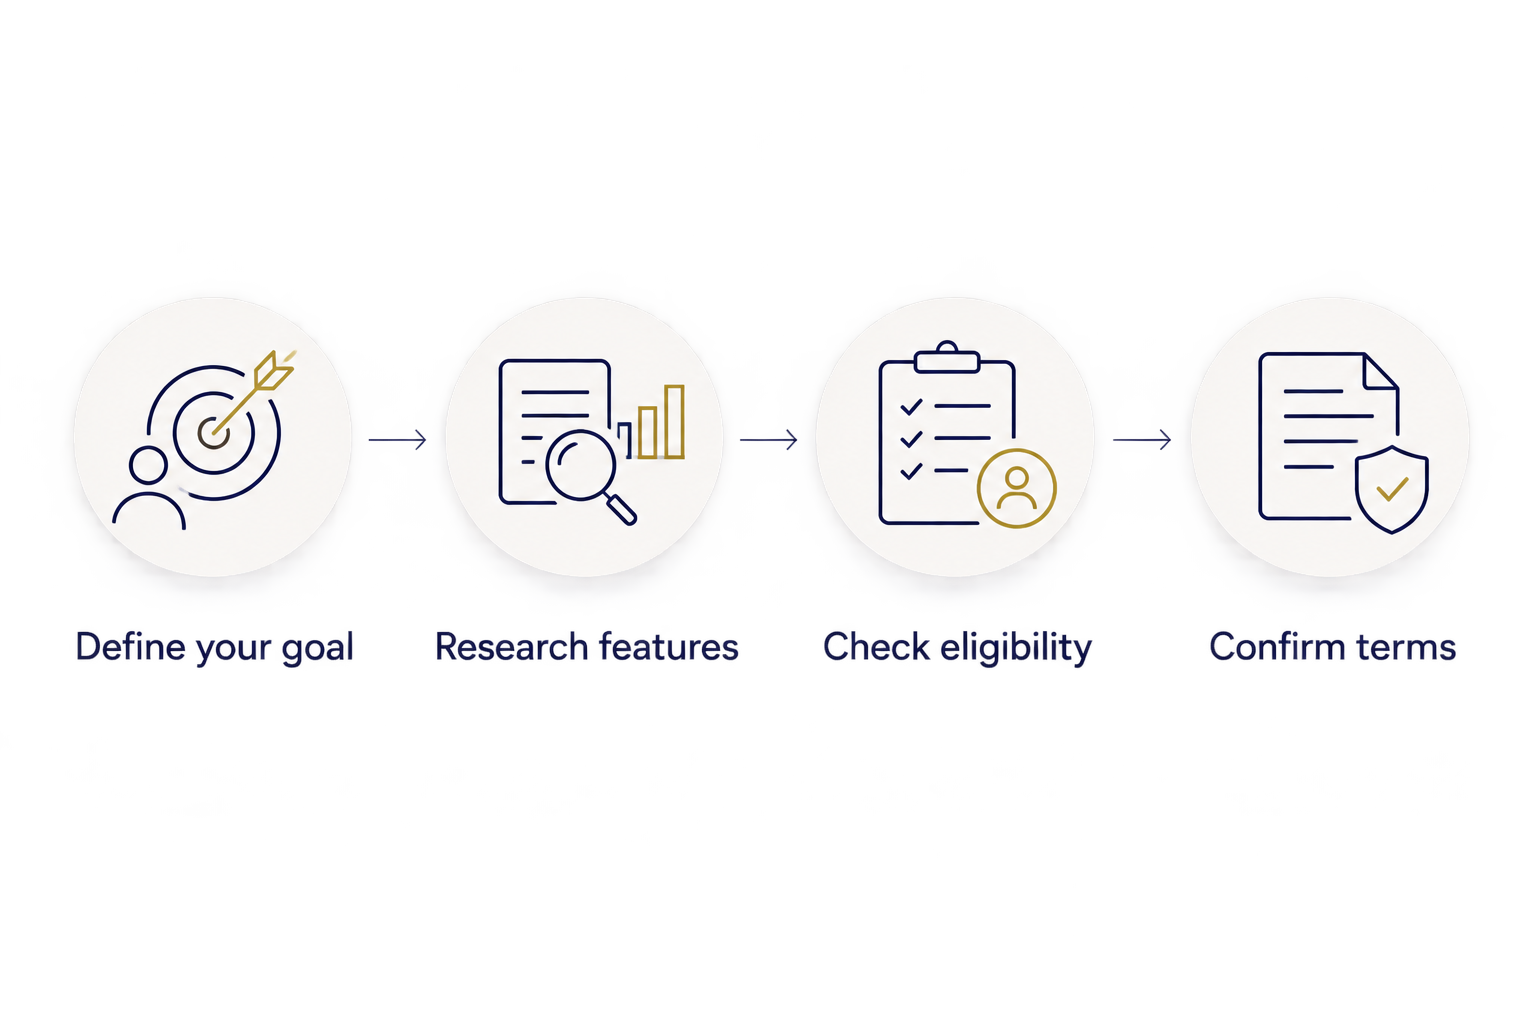
Use both in 4 steps without duplicating the work
You do not need to choose one route for every part of the process. Use comparison research to prepare better questions, then seek individual assistance where your circumstances require it.
- Define your goal. State whether you are buying, refinancing, accessing equity or considering a guarantor arrangement.
- Research features. Identify the repayment structure and loan functions you need before building a shortlist.
- Check eligibility. Discuss income evidence, deposit, commitments and property details with a broker or lender.
- Confirm terms. Read the proposed loan documents and resolve outstanding questions before committing.
For a 2026 enquiry, prepare your borrowing goal, income information, existing commitments and questions. Avoid submitting multiple applications simply to discover which lender will accept you; ask about eligibility and credit enquiries before authorising an application.
Ready to discuss your circumstances? Contact us today and explain what you want the loan to achieve.
Discuss your home loan today
Explain your borrowing goals and ask what documents are needed to assess your circumstances.
Final verdict: choose the service your next decision needs
Choose Mortgage Pros if you need individual guidance
Best for: a doctor seeking home loan advice, or a borrower wanting application support. Choose the broker when income assessment, refinancing, equity or a guarantor arrangement needs a discussion about your circumstances.
The strongest reason to enquire is not a promise of approval. It is the need to understand which borrowing approach fits your situation and what evidence an application requires.
Choose Canstar if you want to lead the research
Best for: a self-directed borrower exploring home loan features and listed products. Choose the comparison website when you want to build your understanding before speaking with a lender or broker.
Accept the responsibility that comes with that choice. You still need to verify personal eligibility, understand conditions and decide whether to obtain individual advice.
| Dimension | Winner |
|---|---|
| Self-directed initial research | Canstar |
| Doctor-focused advice | The specialist broker |
| Application support | The broker |
| Control over approval | Tie: the lender decides |
| Pricing | No winner without reviewing disclosures and loan terms |
| Comparison scope | Tie: verify coverage with either route |
FAQ
Is Mortgage Pros better than Canstar for a doctor home loan?
Mortgage Pros is the better fit when a doctor wants personalised home loan advice and application support. Canstar is better suited to self-directed product research; comparison results do not establish how a lender will assess your medical income.
Is Canstar a substitute for a mortgage broker?
Canstar’s home loan comparison function is not a substitute for individual mortgage broking advice. Use comparison research to investigate products, then ask a broker or lender to assess your circumstances.
Can I use a comparison website before speaking to a broker?
Yes, you can research home loans before speaking to a broker. Bring your shortlist and questions, but remain open to alternatives if your preferred product does not fit your circumstances.
Does a highly rated home loan mean I will be approved?
No, a product rating does not guarantee approval. The lender assesses your application, including your financial circumstances and the proposed property.
How do I compare the cost of a broker and a comparison website?
Check the broker’s fee and remuneration disclosures and the comparison website’s commercial disclosures. Separately assess the actual loan terms, because the research route alone does not determine your mortgage costs.
What should a doctor prepare before asking about a home loan?
Prepare information about your income sources, employment, deposit, debts and borrowing goal. Ask which supporting documents are required, particularly if you receive overtime, on-call, locum or private practice income.
Should I apply for the first loan that looks suitable online?
No, confirm eligibility and understand the loan conditions before applying. Ask how your income will be assessed and what credit enquiries the application involves.
One last thing
Ask what would rule the loan out, not just what makes it attractive. That question directs attention to eligibility, property restrictions, documentation and conditions before you commit to an application.
For your 2026 decision, write down your non-negotiable needs and take them to the conversation. Contact us today to discuss your circumstances and the next steps for your home loan.
This article provides general information, not a personal credit recommendation. Obtain advice based on your circumstances before making a borrowing decision.
Related guides
- How much can I borrow as a doctor in Australia?
- Can doctors use overtime and on-call pay for a home loan?
- How to choose a doctor mortgage broker for complex income