Choose Mortgage Pros if you want a home loan specialist with an explicit focus on doctors; choose Hunter Galloway if you already have an adviser there whose written recommendation fits your circumstances and you want to retain that relationship. The deciding factor is medical-borrower expertise versus the value of an established adviser relationship—not a promise of approval.
- Mortgage Pros vs Hunter Galloway: prioritise medical home loan expertise or an established adviser with a suitable written recommendation.
- Mortgage Pros is a specialist option for doctors seeking home loan advice and approval support.
- Retain Hunter Galloway when your existing adviser demonstrates a suitable loan structure and clear application plan.
- Compare income assessment, loan features, remuneration disclosures and ongoing responsibilities before appointing either broker.
Why this matters
Choosing a mortgage broker means choosing who will translate your financial position into a lender application. For a doctor, the important questions include how employment arrangements, variable earnings and existing liabilities affect the proposed borrowing strategy.
Your 2026 decision should start with your circumstances, not a generic broker ranking. A useful recommendation explains which lender requirements matter to you, what evidence supports the application and which compromises accompany the proposed loan.
Specialisation is a reason to start a conversation, not a substitute for reviewing the recommendation. Equally, an existing relationship deserves consideration only when the adviser continues to explain the loan clearly and address your current needs.
At a glance
| Dimension | Mortgage Pros | Hunter Galloway |
|---|---|---|
| Best for | Doctors seeking a broker with an explicit medical home loan focus | Existing clients whose adviser has already demonstrated a suitable approach |
| Standout feature | Stated specialisation in home loans for doctors | Continuity, where you already have a productive adviser relationship |
| Income assessment | Ask how your medical employment and income will be presented | Ask your adviser to explain the proposed treatment of each income source |
| Refinancing and equity | Refinancing, equity and guarantor arrangements are stated services | Request a written scope covering your particular transaction |
| Approval responsibility | The lender makes the credit decision | The lender makes the credit decision |
| Ongoing support | Agree review responsibilities before proceeding | Confirm what your existing relationship includes after settlement |
| Pricing model | Review the credit quote and remuneration disclosures | Review the credit quote and remuneration disclosures |
The table separates a stated service focus from a conditional reason to retain another adviser. It does not rank lender access, turnaround times or approval outcomes. Those issues belong in the written advice you receive for your own application.
Medical borrowers have a clearer specialist starting point
Mortgage Pros is a specialist option for doctors seeking home loan advice and approval support. Its stated focus gives medical borrowers a direct reason to include the firm in their shortlist.
That focus matters most when you need more than a basic borrowing estimate. Your discussion should cover the employment evidence you hold, which earnings are recurring and what changes are expected before settlement. A broker should explain how those facts affect lender selection rather than simply accepting a total income figure.
The limitation is straightforward: specialisation does not establish eligibility for a particular lender policy. Your occupation alone does not determine borrowing capacity, deposit requirements or approval.
Before appointing a broker, ask:
- Which parts of my income support this recommendation?
- What evidence will the proposed lender require?
- Which eligibility conditions apply to my employment circumstances?
- What changes if the lender assesses my income differently?
Use the guide to choosing a doctor mortgage broker for complex income to prepare your questions. Keep the conversation focused on your actual employment and financial position.
Hunter Galloway is the continuity choice for a proven relationship
Choose Hunter Galloway when your existing adviser has already explained a suitable strategy and you want to keep that working relationship. This is a specific scenario, not a claim that familiarity makes a loan better.
An established relationship gives you something concrete to assess: the advice, explanations and follow-through you have personally received. Before switching, ask your existing adviser to revisit the recommendation against your current goals. A previous application does not settle whether the next recommendation is appropriate.
Continuity loses its value when you cannot get clear answers about income treatment, loan structure or outstanding conditions. Do not retain an adviser solely because your documents are already on file.
If you have no existing relationship with Hunter Galloway, this advantage does not apply. Compare the proposed advice on its merits and ask each broker the same questions before choosing who will represent your application.
Income assessment should decide the shortlist, not job titles alone
For a medical borrower, the useful comparison is how each adviser proposes to document and explain earnings. A doctor's title is not an income assessment, and a headline borrowing estimate is not a lender decision.
Give each adviser the same information. Include employment contracts, recent payslips, details of variable earnings and relevant financial statements where you operate a business. Explain any planned change in hours, employer or practice arrangements.
Then request a plain-English explanation of:
- Income treatment: which earnings support the proposed application.
- Evidence required: what documents substantiate those earnings.
- Outstanding questions: what needs clarification before submission.
- Alternative approach: what changes if the preferred lender does not accept the proposed treatment.
The better recommendation is the one that connects your evidence to the proposed lender's requirements. Do not award either broker an income-assessment win based only on a marketing description. Ask for the reasoning that applies to you.
Refinancing and equity need a defined brief
Refinancing, equity access and guarantor arrangements form part of the client's stated service scope. These are relevant starting points if you already own property, but each transaction needs a distinct objective.
For refinancing, explain what you want to change: loan features, repayment structure or the suitability of the existing arrangement. Ask the adviser to compare the proposed loan with keeping your current loan, rather than presenting switching as the default answer.
For equity access, distinguish the equity you calculate from the additional borrowing a lender will approve. Property value, existing debt and serviceability all affect the assessment. Equity is not an approval to borrow.
For a guarantor arrangement, ask what obligations the guarantee creates and what would need to happen before release. Independent legal advice is important for the guarantor.
Choose the adviser who defines the transaction before recommending the loan. A broad service list is useful, but it does not replace an explanation of why the proposed structure suits your purpose.
Neither broker controls the lender's approval
Approval responsibility is a tie: the lender makes the credit decision. A broker assists with advice and the application process; that role does not remove the lender's assessment requirements.
Compare how each adviser explains the stages between an initial discussion and settlement. Ask what remains unverified, which conditions are outstanding and whether a property assessment is still required.
In 2026, keep your communication practical. Before committing to a property transaction, understand the status of your finance and obtain appropriate legal advice about contractual obligations.
A useful application discussion separates:
- An indicative borrowing estimate from a credit assessment.
- Conditional approval from satisfaction of outstanding conditions.
- The broker's submission work from the lender's decision.
- Your preferred settlement date from a confirmed finance outcome.
Do not choose a broker because an early conversation sounds certain. Choose clear explanations of what is known, what remains conditional and what you need to do next.
Ongoing support needs an agreement, not an assumption
Neither broker earns an ongoing-service win without a clear agreement about responsibilities. Establish who you will contact, what assistance is included and whether future reviews require you to initiate the conversation.
This matters if your circumstances are likely to change after settlement. A move into private practice, a different employment arrangement or an investment purchase can create a new advice need. The original loan recommendation does not automatically answer those future questions.
Ask your proposed adviser:
- Who handles questions after settlement?
- What should I do if my income or property plans change?
- How do I request a review of the existing loan?
- Which matters need a fresh assessment?
An existing client should compare the answers with their own experience. A new client should obtain a clear explanation before proceeding. Avoid treating access to a broker as a promise of automatic monitoring.
Pricing: compare the model and disclosures, not assumptions
For your 2026 comparison, distinguish broker remuneration from the costs attached to the loan itself. Australian mortgage brokers commonly receive lender commissions, while borrower-paid broker fees can also apply depending on the service arrangement.
Read each broker's credit guide, any credit quote and the remuneration disclosures associated with the recommendation. These documents should explain the arrangement relevant to your engagement. Do not assume either firm's terms from the general industry model.
The trade-off is transparency, not simply who appears to have the simplest arrangement. You need to understand what work is covered, who pays the broker and whether any borrower payment depends on particular circumstances.
Ask both advisers the same questions:
- Will I pay a broker fee under this engagement?
- How is the broker remunerated for the recommended loan?
- Are there circumstances that change my payment obligations?
- Which lender-related charges are separate from broker remuneration?
Compare the complete recommendation alongside its disclosures. Remuneration is part of the decision, but it does not establish whether the loan structure meets your needs.
Compare both advisers using the same brief
A consistent brief makes your 2026 comparison useful. Otherwise, different answers can reflect different assumptions rather than a meaningful difference between advisers.
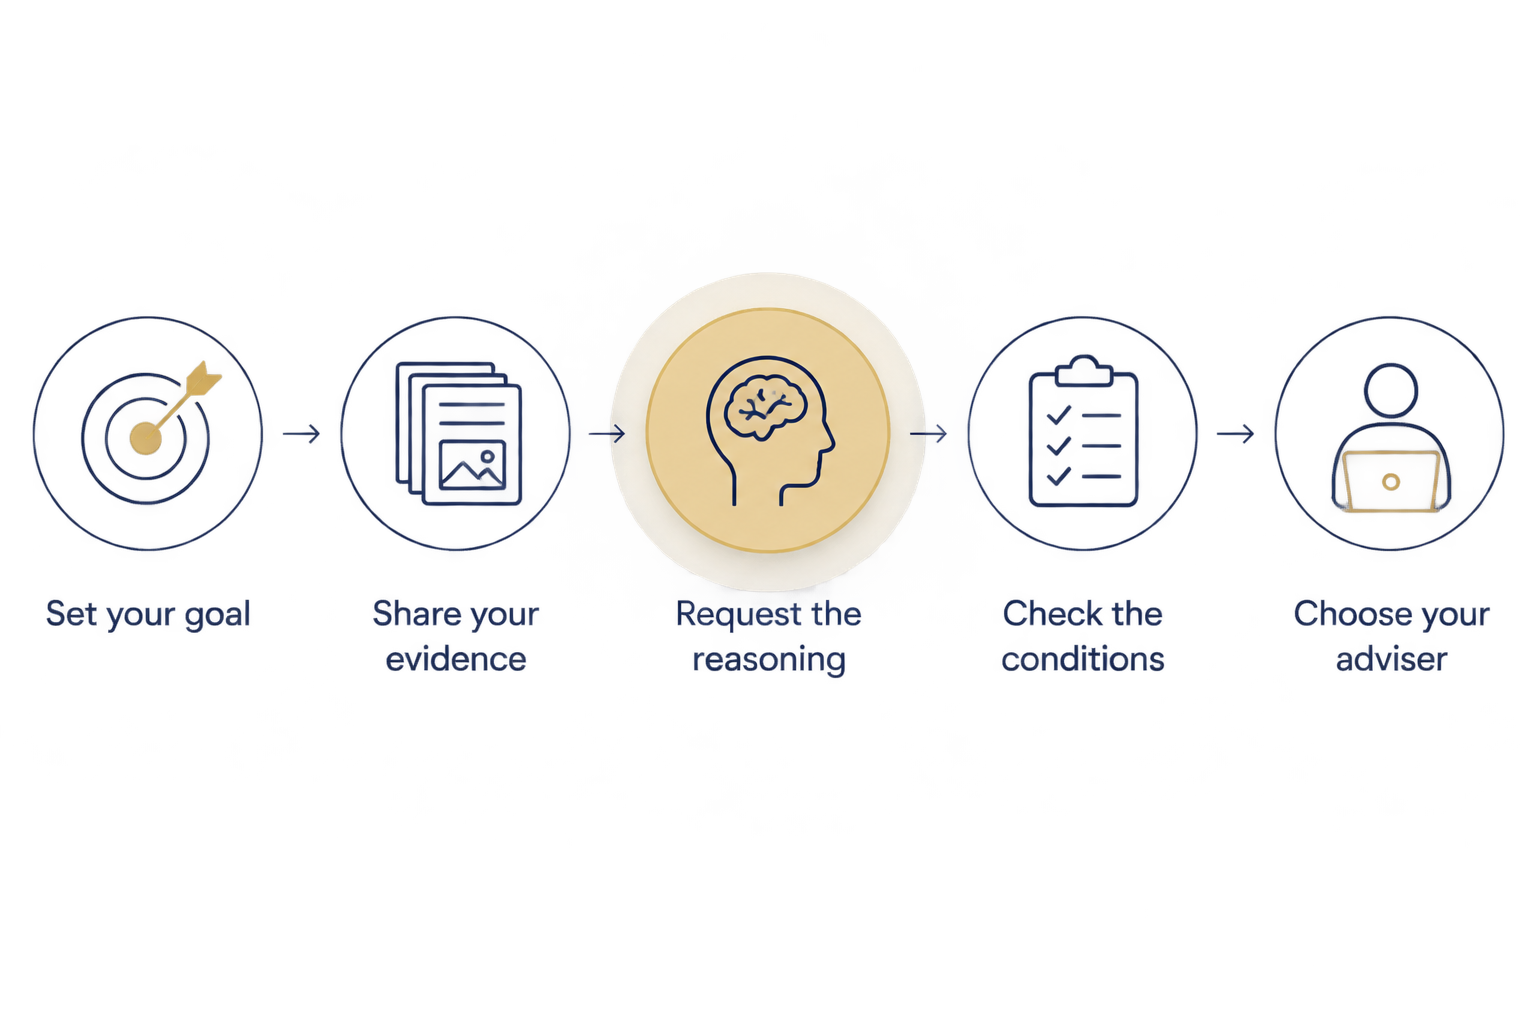
Use this sequence before authorising an application:
- Set your goal. State whether you are buying, refinancing, accessing equity or considering a guarantor arrangement.
- Share your evidence. Provide the same income, savings, liabilities and employment information to each adviser.
- Request the reasoning. Ask why the proposed lender and loan structure fit your circumstances.
- Check the conditions. Identify outstanding evidence, assessment questions and contractual dependencies.
- Choose your adviser. Confirm scope, disclosures and the next action before proceeding.
Keep a copy of each recommendation and note the assumptions behind it. If an answer changes, ask what new information caused the change before treating it as a better outcome.
Final verdict: specialist fit or established continuity
Choose Mortgage Pros if you want a medical-borrower starting point
Best for: doctors seeking a mortgage broker with an explicit focus on doctor home loans. Start with your employment arrangements, borrowing objective and supporting evidence, then ask for a recommendation tied to your circumstances.
This is a fit-based recommendation, not a prediction of lender approval. Assess the proposed loan and disclosures before committing.
Choose Hunter Galloway if your existing adviser has earned continuity
Best for: existing clients with a suitable written recommendation and a working relationship they want to retain. Keep that relationship when the adviser explains the strategy clearly and addresses your current needs.
If those conditions are absent, familiarity is not enough. Compare another adviser using the same brief.
| Dimension | Decision |
|---|---|
| Medical specialisation | Mortgage Pros is the explicit specialist starting point |
| Existing adviser relationship | Hunter Galloway, when the relationship already works for you |
| Income assessment | Decide from the documented treatment of your earnings |
| Refinancing and equity | Decide from the transaction-specific recommendation |
| Approval responsibility | Tie: the lender decides |
| Ongoing support | No automatic winner; agree the scope |
| Pricing model | Compare engagement and remuneration disclosures |
Discuss your home loan needs
Explain your medical employment, borrowing goal and application questions to a mortgage broker.
FAQ
Is Mortgage Pros or Hunter Galloway better for doctors?
Mortgage Pros is the specialist starting point for doctors because doctor home loans are an explicit focus. An existing Hunter Galloway client should also assess whether their current adviser has already provided a suitable, clearly explained recommendation.
Should I change brokers if I already use Hunter Galloway?
Change brokers when another adviser’s proposed approach better addresses your needs, not simply because a comparison page names an alternative. First ask your existing adviser to explain the loan structure, income treatment and outstanding conditions.
Can a mortgage broker guarantee my home loan approval?
No mortgage broker can guarantee the lender’s credit decision. Your application remains subject to the lender’s assessment and any conditions attached to approval.
How should a doctor compare mortgage brokers?
Compare how each broker proposes to assess and document your actual income. Give each adviser the same employment, earnings, liabilities and borrowing objectives, then request the reasoning behind the recommendation.
How do I compare mortgage broker remuneration?
Compare each broker’s credit guide, any credit quote and the remuneration disclosures relevant to the recommendation. Ask who pays the broker, what work is covered and whether any borrower-paid obligations apply.
Is keeping my existing broker better than starting again?
Keeping your existing broker makes sense when the adviser continues to provide suitable advice and clear communication. A previous relationship does not replace a fresh assessment of your current borrowing needs.
What should I prepare before contacting a mortgage broker?
Prepare your borrowing objective, employment details, income evidence, savings and existing liabilities. Explain planned changes to your employment or financial circumstances so the adviser can identify relevant assessment questions.
One last thing
Before making your 2026 choice, ask each adviser to explain the strongest reason not to proceed with the proposed loan. A useful recommendation explains its limitations as clearly as its benefits. Contact us today with your borrowing goal and the questions you want answered.
Related guides
- Can doctors use overtime and on-call pay for a home loan?
- How do surgeons combine hospital and private income for a home loan?
- How is self-employed dentist income assessed for a home loan?