Your Mortgage provides a starting point for researching and comparing home loans, but general comparisons do not establish how a lender will assess your income or application. The best Your Mortgage alternative in 2026 is Mortgage Pros if you need doctor-focused mortgage broking; ASIC’s Moneysmart if you need independent educational guidance. For a decision on a particular lender’s loan, speak to that lender directly.
- For your mortgage alternatives, choose Mortgage Pros for doctor home loan advice and application support.
- Choose ASIC’s Moneysmart for independent home loan education and repayment calculations, not loan selection or approval.
- Go directly to a lender when you have selected its loan and want its assessment.
- Keep Your Mortgage for initial research; distinguish a product comparison from a borrowing assessment.
Why this matters
Choosing a comparison website and choosing a home loan are 2 separate decisions. A website helps you research products; your lender decides whether your application meets its requirements.
That distinction matters when you earn overtime, work as a locum, combine hospital employment with private practice, or run a dental practice. The question is not simply which advertised loan looks attractive. You need to understand which income a lender accepts, what evidence it requires and whether the proposed repayments fit your budget.
For your 2026 comparison, choose the next service according to the work you need done. Education, personalised mortgage advice and credit approval serve different purposes.
Your Mortgage alternatives at a glance
This guide compares 3 alternative routes: a mortgage broker, an independent educational resource and a direct lender. Your Mortgage remains in the table so you can compare those routes against your starting point.
| Option | Best for | Standout function | How it differs from Your Mortgage | Main limitation |
|---|---|---|---|---|
| Your Mortgage | Initial home loan research | Home loan comparison and information | The starting point for this comparison | Product research does not establish application eligibility |
| Mortgage Pros | Doctors, dentists and surgeons seeking mortgage advice | Mortgage broking and approval support | Moves from general research to advice about your borrowing circumstances | A broker cannot guarantee a lender’s approval |
| ASIC’s Moneysmart | Understanding borrowing and repayments | Independent educational resources and calculators | Focuses on financial understanding rather than selecting a loan for you | Does not arrange your mortgage |
| A direct lender | Applying for a particular lender’s loan | Assessment of an application against its lending requirements | Moves from comparing products to dealing with the credit provider | Does not compare competing lenders for you |
Choose the service that answers your next unresolved question. A second comparison page is not a substitute for checking how your income will be assessed.
1. Mortgage Pros: best for medical-borrower advice
Mortgage Pros is a Sydney-based mortgage broking firm serving borrowers across Australia, specialising in home loans for doctors, dentists and surgeons. Its services include home purchase lending, refinancing, equity and guarantor arrangements.
Best for: Medical professionals who want help connecting their income, deposit and property plans to a home loan application.
Where the service shines
- Its stated specialisation matches doctors, dentists and surgeons rather than treating medical borrowers as an incidental audience.
- Mortgage broking addresses your circumstances and application, rather than stopping at general product research.
- Support covers both purchasing and managing an existing home loan, including refinancing and equity enquiries.
For a medical borrower, the useful conversation starts with how you earn your income. Bring your employment arrangements, income records, existing liabilities and deposit position so the discussion addresses the application you actually intend to make.
Where the service falls short
- A broker is not the lender and cannot guarantee approval, a property valuation or a settlement date.
- Personalised advice requires you to provide financial information and supporting documents; it is not an anonymous comparison exercise.
- A specialisation in medical borrowers does not mean every doctor qualifies for the same lending treatment.
Head-to-head with Your Mortgage
| Dimension | Mortgage Pros | Your Mortgage |
|---|---|---|
| Main role | Mortgage broking service | Home loan research and comparison resource |
| Borrower focus | Stated specialisation in doctors, dentists and surgeons | General home loan research |
| Application stage | Advice and approval support | A starting point for researching options |
| Approval authority | The selected lender decides | A comparison does not constitute approval |
Before proceeding, ask which lenders will be considered, how the recommendation will be explained and what documents are required. Request an explanation tied to your circumstances, not just a product name.
Verdict: Buy — choose the broker route when you need medical-borrower advice and application support.
2. ASIC’s Moneysmart: best for independent home loan education
ASIC’s Moneysmart provides financial education, including information about home loans and mortgage calculators. It is useful when you want to understand repayments, borrowing decisions and loan features before discussing a particular product.
Best for: Borrowers who need a clearer understanding of home loans before choosing an application route.
Where Moneysmart shines
- It provides an educational perspective rather than a recommendation to take out a particular lender’s mortgage.
- Its calculators help you explore how loan inputs affect estimated repayments.
- Its explanations support more informed questions about borrowing and loan features.
Where Moneysmart falls short
- It does not select a home loan for your circumstances or arrange an application.
- Calculator results depend on your inputs and assumptions; they are not a lender’s borrowing assessment.
- General education does not resolve how a lender will treat locum earnings, practice income or variable allowances.
Head-to-head with Your Mortgage
| Dimension | ASIC’s Moneysmart | Your Mortgage |
|---|---|---|
| Main purpose | Financial education | Home loan research and comparison |
| Best next question | What does this loan feature mean for my finances? | Which products should I investigate? |
| Application outcome | Does not arrange approval | Comparison research does not establish approval |
Use Moneysmart to understand the decision, then seek an assessment where your circumstances require one. For a 2026 purchase, keep the figures in any calculator consistent with the loan you are considering.
Verdict: Hold — use Moneysmart to prepare, not as a replacement for loan selection or assessment.
3. A direct lender: best for assessing a loan you have selected
Going directly to a lender makes sense when you already have a particular loan in mind and want that lender to assess your application. The lender can explain its own requirements and decide whether to approve the credit.
Best for: Borrowers who understand the alternatives and want to proceed with a specific lender.
Where a direct lender shines
- You discuss the application with the organisation providing the loan.
- You can ask about that lender’s documentation requirements and assessment process.
- The lender can explain the conditions attached to its own approval.
Where a direct lender falls short
- A lender does not compare competing lenders on your behalf.
- Acceptance by one lender does not establish that its loan is the best fit across the market.
- You need to evaluate competing options yourself if you want a wider comparison.
| Dimension | Direct lender | Your Mortgage |
|---|---|---|
| Scope | Its own lending products | Product research and comparison |
| Main task | Assessing an application | Helping you investigate options |
| Key limitation | No competing-lender comparison on your behalf | No approval from browsing a comparison |
Verdict: Buy — choose direct lending when you have made an informed lender choice and need its assessment.
Why people switch from Your Mortgage
The practical reason to move beyond a comparison resource is a change in the question you need answered. Research helps you identify options; an application requires evidence about you and the property.
You need an income assessment
An advertised product does not tell a hospital doctor whether overtime will count towards borrowing capacity. It also does not establish how a lender will assess a dentist’s business income or a surgeon’s combination of employment and private earnings.
Ask which income components will be used, what documents support them and whether the assessment depends on employment history. Do not treat an online borrowing estimate as confirmation.
You need to distinguish eligibility from suitability
A loan can look attractive without meeting your needs. You still need to consider repayment type, access to money, intended ownership structure and your plans for the property.
For medical professionals, professional status is a reason to ask about relevant lending policies, not a reason to assume an exception applies. Confirm the conditions for your application in 2026.
You need help completing an application
Research does not organise your supporting evidence or resolve questions raised during assessment. If that is your next obstacle, choose application support rather than continuing to collect product comparisons.
There is no need to abandon Your Mortgage to take that step. You can retain it as a research resource while using a broker or lender for a different task.
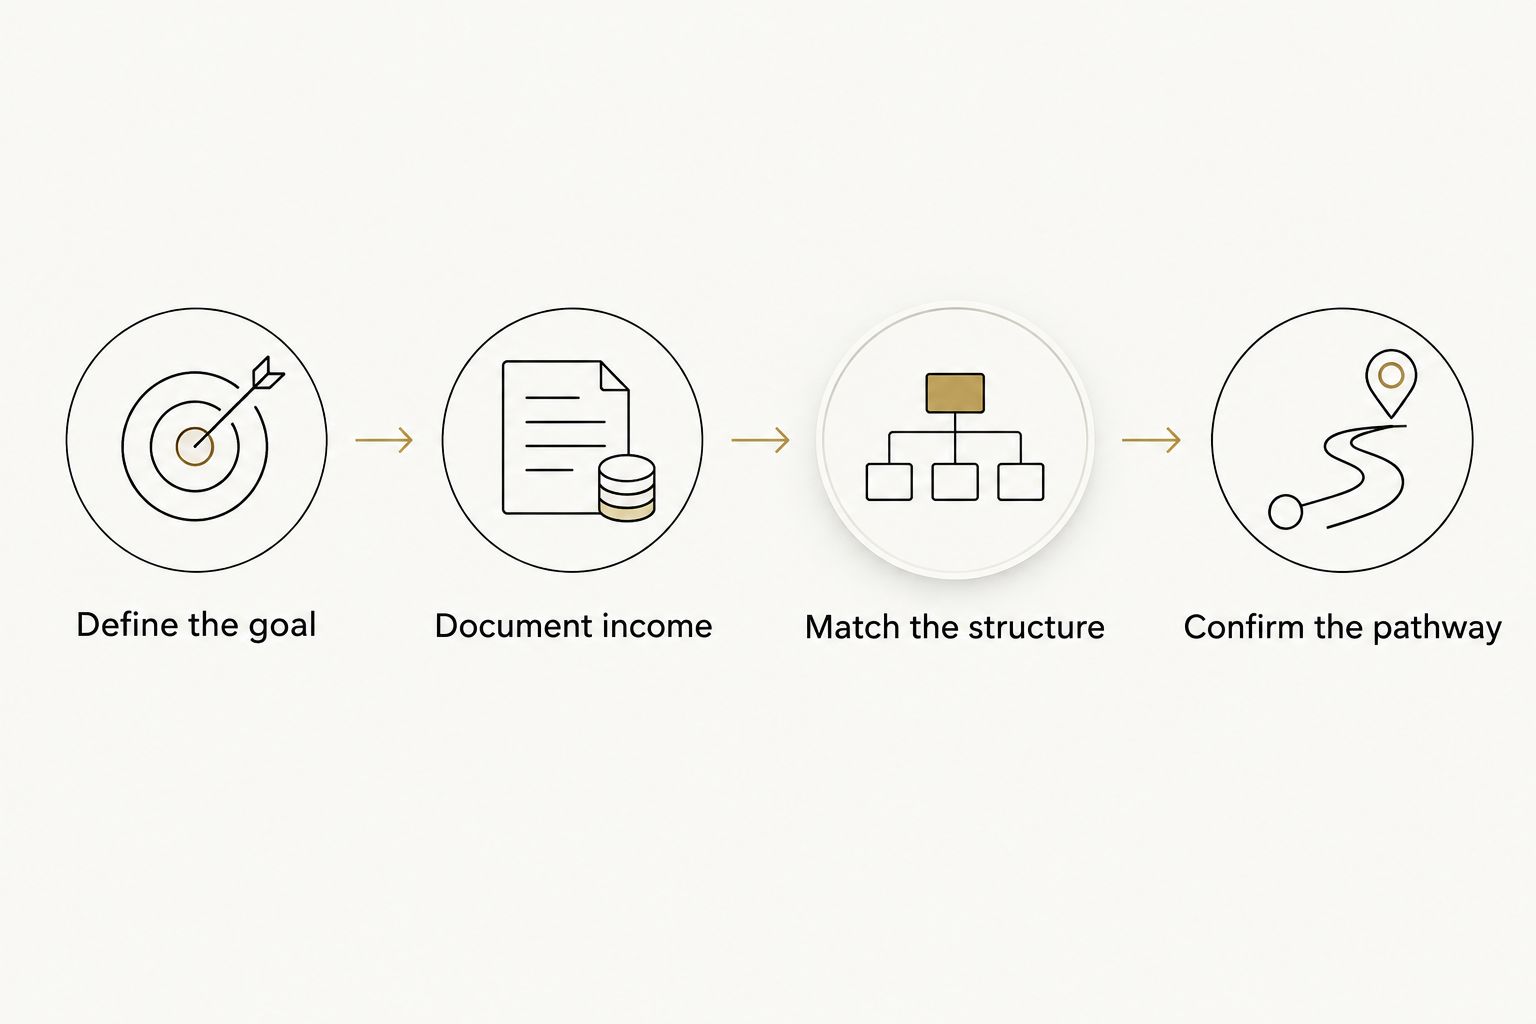
Make a useful comparison in 4 steps
Define the goal
Write down whether you are purchasing, refinancing, releasing equity or considering a guarantor arrangement. Include the intended property use and any contractual deadline.
A clear goal keeps the conversation focused. A first-home purchase and a refinance do not require the same decision process.
Document income
Separate salary, overtime, allowances, contract earnings and business income where relevant. Gather supporting records before asking for a borrowing assessment.
Describe changes plainly. A move between hospitals, a new locum arrangement or a transition into private practice deserves explanation rather than an assumed treatment.
Match the structure
Consider how you intend to repay the loan and use its features. Ask what an offset account or redraw facility would mean for the particular loan, rather than assuming the labels are interchangeable.
Compare alternatives using the same loan amount, term and repayment assumptions. Otherwise, an apparent difference can reflect different inputs rather than a better fit.
Confirm the pathway
Ask what remains outstanding, who will submit the application and which conditions still need to be met. Distinguish an estimate, an indicative discussion and a formal lending decision.
Do not commit to a property purchase on the assumption that an online comparison establishes finance approval. Obtain appropriate legal advice about your purchase obligations.
Before you act, ask 3 questions: Why does this option suit my circumstances? What evidence supports the assessment? What still needs confirmation? A useful answer should distinguish facts already established from conditions still outstanding.
Discuss your medical home loan
Talk through your income, deposit and application goals with a mortgage broker.
When staying with Your Mortgage is the right call
Stay with Your Mortgage when you are still learning the market and want a starting point for home loan comparisons. You do not need personalised advice merely to read about loan features or investigate products.
The boundary is the decision you are making. In 2026, use comparison research to build questions and identify options; use a broker or lender when you need an assessment of your own borrowing circumstances.
Keep the research resource if it remains useful. Change the next step when your question changes.
FAQ
What is the best Your Mortgage alternative for doctors?
Mortgage Pros is the best fit in this comparison for doctors seeking mortgage broking and application support. Its stated specialisation includes doctors, dentists and surgeons, but the lender still decides whether to approve an application.
Is Your Mortgage the same as a mortgage broker?
A home loan comparison resource and a mortgage broking service perform different tasks. Comparing products helps with research; a broker provides advice and application support based on your circumstances.
Can a comparison website tell me whether my home loan will be approved?
No, a product comparison does not establish home loan approval. The lender must assess your application, supporting documents and the property against its requirements.
Should I use Moneysmart or a mortgage broker?
Use ASIC’s Moneysmart for financial education and a mortgage broker for personalised loan advice and application support. The services are complementary rather than interchangeable.
Is going directly to a bank better than using a comparison website?
Going directly to a bank is more appropriate when you want that bank to assess a particular loan application. A comparison website is more useful earlier, when you are researching options rather than seeking a lending decision.
What should a doctor prepare before speaking to a mortgage broker?
Prepare details of your income, employment arrangements, deposit, liabilities and property plans. Identify overtime, on-call payments, locum work or private practice income separately so you can ask how each component will be assessed.
Do medical professionals automatically qualify for special home loan treatment?
No, being a medical professional does not establish eligibility for a particular lending policy. Ask the broker or lender to confirm the requirements and conditions applying to your occupation and circumstances.
One last thing
A better comparison does not always produce a longer shortlist. It can rule out a loan that looks attractive but does not fit your income evidence or borrowing plans.
Before submitting an application, ask for the reasoning behind the recommendation. Contact Mortgage Pros today to discuss your medical home loan goals and the next step towards an assessment.
Related guides
- How to choose a doctor mortgage broker for complex income
- Can doctors use overtime and on-call pay for a home loan?
- How do surgeons combine hospital and private income for a home loan?