There is no fixed amount you can borrow as a doctor in Australia in 2026: your limit depends on the income a lender accepts, your expenses, existing debts, deposit and proposed loan. Doctor-specific lending eligibility does not replace the assessment of whether you can afford repayments. To set a useful buying budget, separate your borrowing capacity from your deposit and the funds needed to complete the purchase.
- How much can I borrow as a doctor? Your assessed income and commitments determine the answer, not your profession alone.
- Doctor home loans still require an affordability assessment; a smaller deposit does not guarantee greater borrowing capacity.
- Compare how lenders assess overtime, on-call payments, locum work and private-practice income.
- Mortgage Pros provides mortgage-broking support for doctors seeking home loan advice and approval assistance.
How much can I borrow as a doctor in Australia?
Your borrowing capacity is the loan amount a lender assesses you can repay, not a fixed multiple of your medical salary. A useful assessment starts with your documented earnings and commitments, then applies the lender's income and affordability policies.
If your pay includes hospital employment, locum shifts or private billings, start with guidance on choosing a doctor mortgage broker for complex income. The central question is which earnings the lender will accept and what evidence supports them.
Keep these separate when discussing your limit:
| Measure | What it tells you | Main limitation |
|---|---|---|
| Borrowing capacity | The loan amount supported by an affordability assessment | It does not establish your total purchase budget |
| Deposit | The funds you contribute towards the purchase | A deposit alone does not demonstrate repayment capacity |
| Loan-to-value ratio | The loan amount relative to the lender's property valuation | It measures the security position, not affordability |
| Comfortable repayment budget | The repayment you can accommodate alongside other priorities | Your preferred budget can be below a lender's maximum |
Ask for both the assessed maximum and the repayments associated with the amount you actually intend to borrow. Those answers serve different purposes.
Why this matters
A doctor with substantial earnings can still have a borrowing limit constrained by existing loans, household spending or income that needs further evidence. Equally, an estimate based only on base salary can leave relevant income out of the discussion.
For a purchase in 2026, assess your current circumstances rather than a future specialist salary or expected practice growth. A planned promotion is not the same as income a lender has agreed to accept.
Use the lender's ceiling as a boundary, not a spending target. Your budget also needs room for the expenses and savings priorities that matter to your household.
How your medical income affects the assessment
Your job title helps explain your work, but the structure and evidence of your earnings determine how a lender assesses them. Give your broker a clear breakdown instead of a single total that combines salary, variable payments and business revenue.
Salaried hospital doctors
For salaried doctors, employment documents and payslips establish the starting point. Distinguish your ordinary salary from overtime, on-call payments, allowances and salary-packaging arrangements.
Best for: doctors whose main earnings come from employment. The advantage is a documented salary; the limitation is that a payslip total does not automatically show which components a lender will accept.
Explain any recent change in role, hours or employment terms. That lets the assessment address the change directly rather than treating a higher payslip as a permanent increase without supporting context.
Locum and contract doctors
Locum earnings need to be understood alongside the pattern of work and the documents supporting it. Contracts, payment records and tax documents help explain how your income is earned.
Best for: doctors working across contracts or placements. The advantage is that the assessment can consider your actual work pattern; the limitation is that a strong recent period does not, by itself, establish sustainable annual income.
Identify gaps, changes in hours and contracts that have ended. Ask which evidence the proposed lender needs before relying on an estimate.
Private-practice and mixed-income doctors
Private-practice revenue is not the same as personal income available for mortgage repayments. Business expenses, ownership structure and existing business commitments need to be understood before a borrowing estimate becomes useful.
Best for: doctors combining employment with practice income, or working through a business. The advantage is that the assessment can account for multiple income sources; the limitation is the additional work needed to establish what is available to you personally.
Provide a clear explanation of the business structure. Avoid counting the same earnings twice through both business profit and payments drawn from the business.
Why borrowing capacity varies between doctors
Two doctors with similar gross earnings do not necessarily receive the same borrowing assessment. These factors explain why:
- Accepted income: lenders assess the evidence and treatment of salary, variable earnings and self-employed income rather than relying on a headline total.
- Household expenses: dependants, childcare, school fees and other recurring spending affect the income available for repayments.
- Existing commitments: personal loans, car finance, investment loans, HELP obligations and credit facilities form part of the assessment.
- Loan structure: the term, repayment type and purpose of the proposed loan affect the repayment calculation.
- Deposit and property: your contribution and the lender's valuation affect the loan-to-value ratio and available lending options.
- Lender policy: differences in income treatment and assessment methods can produce different results from the same borrower information.
For a 2026 application, ask your broker to identify the constraint that matters most in your case. A general instruction to save more is not useful if the immediate issue is proving an income component.
Does a larger deposit let you borrow more?
A larger deposit reduces the loan needed for the same purchase; it does not automatically increase your assessed repayment capacity. It can improve your security position while leaving the affordability limit unchanged.
Loan-to-value ratio, or LVR, is calculated as the loan amount divided by the lender's property valuation, multiplied by 100%. A loan equal to 80% of that valuation has an 80% LVR; the remaining 20% represents the equity contribution before purchase costs and valuation differences.
At 90% LVR, the loan represents 90% of the valuation and the remaining share is 10%. These are ratio illustrations, not lending offers or statements about your eligibility.
| Position | Best for understanding | Benefit | Limitation |
|---|---|---|---|
| Larger deposit | How your own funds reduce the required loan | Less borrowing for the same property value | Does not resolve an income-based affordability shortfall |
| Smaller deposit | How a higher loan share changes the application | Less of the property value comes from your contribution | More borrowing still needs to pass affordability assessment |
| Doctor-specific lending eligibility | Whether your profession affects available options | Gives your broker a relevant policy question to investigate | Does not guarantee approval or a particular borrowing limit |
Ask separately about lenders mortgage insurance eligibility and affordability. A favourable answer on insurance does not answer whether you can service the loan.
How to get a useful borrowing assessment
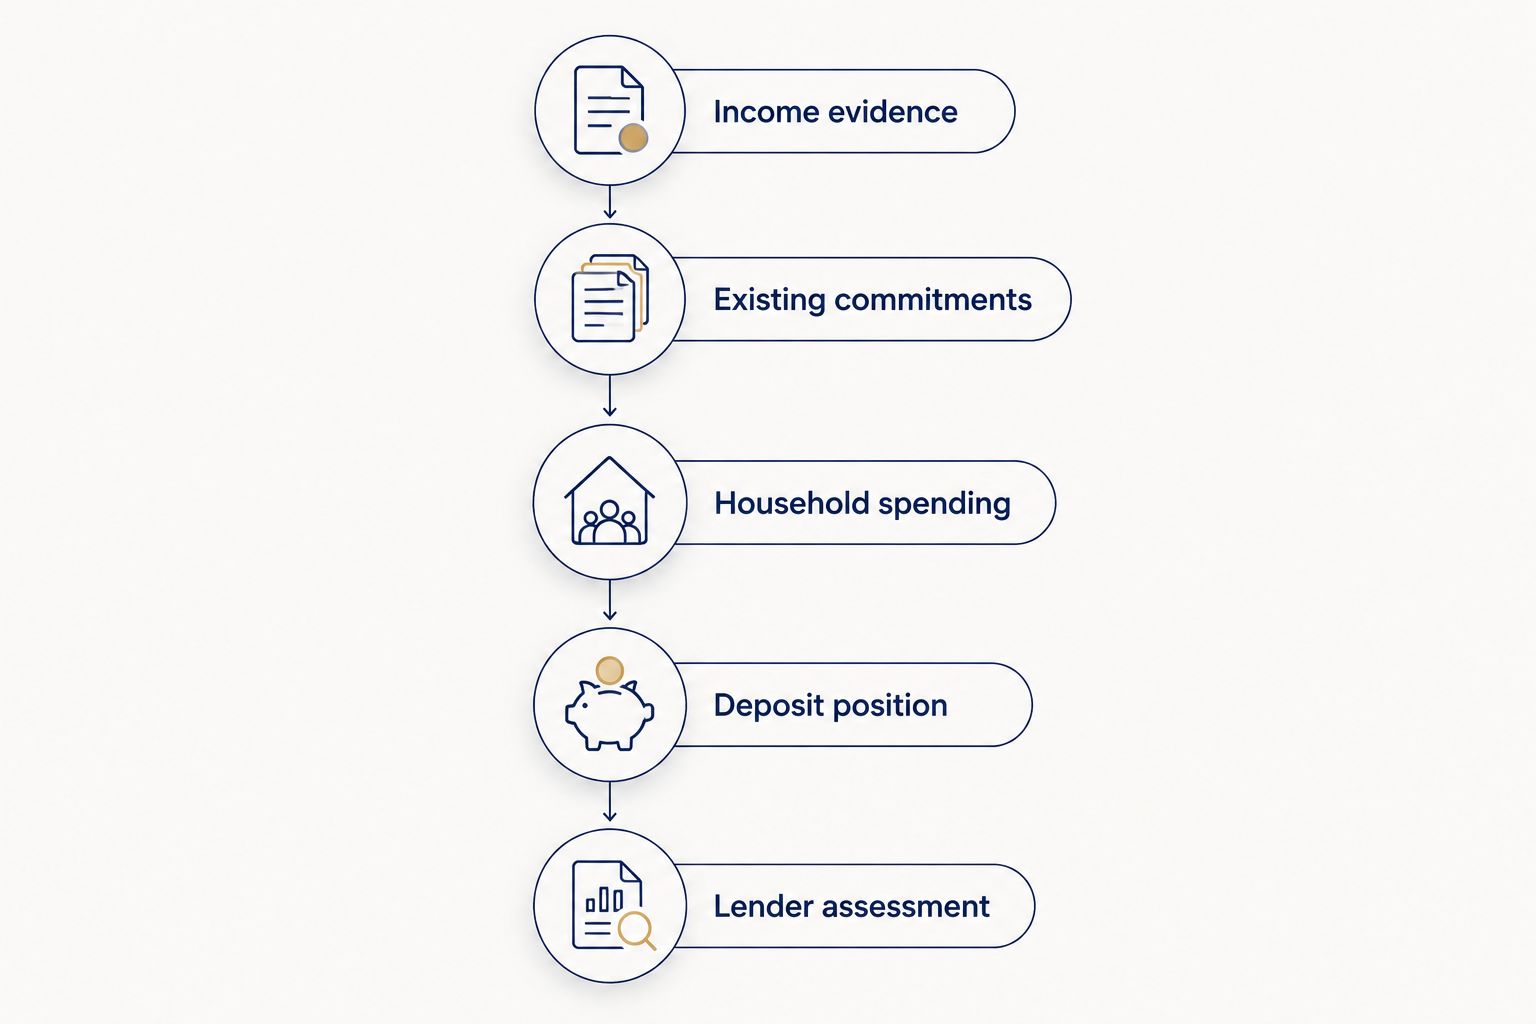
An online calculator can provide a starting estimate, but it cannot confirm how a particular lender will treat your medical income. Follow this sequence before using a figure to guide property offers.
- Income evidence: collect employment documents, payslips and records supporting variable or business income. Explain changes rather than leaving the assessor to infer them.
- Existing commitments: list debts, credit limits, repayments and relevant study-loan obligations. Include facilities you hold even if you rarely use them.
- Household spending: prepare an honest account of recurring expenses. Include known changes that will affect the household after purchase.
- Deposit position: identify available savings, equity or other proposed contributions. Keep purchase costs separate from the contribution towards the property.
- Lender assessment: ask which income is accepted, what remains conditional and what repayment accompanies the proposed amount.
This sequence makes the estimate easier to explain and check. It also helps distinguish an evidence gap from a genuine affordability limit.
When you receive the result, request the assumptions behind it in plain language. Check whether the figure depends on closing a credit facility, supplying further income evidence or meeting another condition.
Mortgage Pros is best suited to doctors seeking mortgage-broking support rather than a direct lender. Its doctor home loan focus is relevant when you need help presenting medical earnings and understanding the approval process; the lender still makes the lending decision.
Discuss your doctor borrowing capacity
Ask Mortgage Pros about your income evidence, borrowing assessment and home loan application.
Can overtime and on-call pay increase my borrowing capacity?
Overtime and on-call pay can contribute to a borrowing assessment when the lender accepts the income and its supporting evidence. Do not assume every payment receives the same treatment as ordinary salary.
Ask whether the assessment includes these earnings, what history supports them and whether a recent roster change matters. A lower estimate caused by excluded income needs a different response from one caused by existing debt.
For your 2026 application, use records that explain the pattern rather than selecting only your highest-earning payslip. The objective is an accurate assessment of sustainable earnings, not the largest annualised figure.
Will my borrowing limit rise when I become a specialist?
A future specialist role does not automatically increase your current borrowing limit. The relevant question is whether a lender accepts the employment and income evidence available when you apply.
If you have a signed contract, provide it and ask how its terms affect the assessment. Keep any estimate based on future employment separate from an assessment based on your present position.
Can I improve my borrowing capacity before applying?
You can address inaccurate information, incomplete income evidence and commitments that no longer suit your needs before applying. Ask for a reassessment of the specific change rather than assuming it will increase your limit.
Review unused credit facilities and discretionary debt, but do not make changes solely to chase a larger mortgage without understanding the consequences. Retain enough funds for the purchase process and your household needs.
FAQ
How much can I borrow as a doctor in Australia in 2026?
There is no fixed borrowing amount for doctors in Australia in 2026. A lender assesses accepted income, expenses, existing commitments, the proposed loan and supporting evidence.
Can I borrow a fixed multiple of my doctor salary?
A salary multiple does not establish your approved borrowing limit. Your expenses, debts, income structure and the lender’s assessment all affect the result.
Does being a doctor guarantee a bigger home loan?
Being a doctor does not guarantee a bigger home loan. Doctor-specific eligibility and repayment affordability are separate questions.
Will a lender count my overtime and on-call payments?
A lender’s acceptance of overtime and on-call payments depends on its policy and your supporting evidence. Ask which components are included before relying on a borrowing estimate.
Does a larger deposit increase my borrowing capacity?
A larger deposit reduces the loan required for the same purchase, but does not automatically increase repayment capacity. It changes the loan-to-value ratio rather than your earnings.
Can I use private-practice revenue as my personal income?
Private-practice revenue is not automatically personal income available for mortgage repayments. Business expenses, ownership arrangements and financial records need to be assessed.
Can Mortgage Pros help assess doctor home loan options?
Mortgage Pros provides mortgage-broking services for doctors seeking home loan advice and approval support. Ask for an assessment based on your documented income, commitments and purchase plans.
One last thing
Ask what limits your borrowing figure before asking how to increase it. An income-evidence issue, a deposit constraint and a repayment shortfall require different next steps.
For a 2026 purchase, write down both your assessed loan limit and your preferred repayment budget. If those point to different purchase targets, use the budget you can sustain rather than treating approval as an instruction to borrow more. Contact us today to discuss your doctor home loan assessment with Mortgage Pros.
Related guides
- Can doctors use overtime and on-call pay for a home loan?
- How can locum doctors document income for a home loan?
- Can doctors get a home loan during probation?