Choose Mortgage Pros if you want mortgage broking support, especially as a doctor, dentist or surgeon; choose Money.com.au if your immediate task is researching and comparing home loans online. In 2026, the practical distinction is personalised application support versus a comparison-led starting point—not a guarantee of a better loan.
- Mortgage Pros vs Money.com.au comes down to specialist mortgage broking support versus online home loan comparison.
- Medical borrowers should prioritise income assessment and eligibility over an advertised interest rate.
- Money.com.au suits initial research; a comparison result is not a lending decision.
- Compare written recommendations, remuneration disclosures and loan conditions before committing.
Why this matters
A home loan comparison and a home loan assessment answer different questions. A comparison helps you identify options; an assessment examines whether a lender will accept your income, deposit, liabilities and proposed property.
That distinction matters when your earnings include hospital employment, private practice, overtime or locum work. The loan that looks attractive on screen still needs to fit your circumstances and the lender’s criteria.
Mortgage Pros provides mortgage broking services for home buyers and property owners, including refinancing, equity and guarantor arrangements. Its specialisation in medical borrowers makes that service particularly relevant when your question is about qualifying for a loan, rather than simply finding products to investigate.
Choose the service that solves your next problem, not the website with the most appealing headline.
At a glance
Use this 2026 comparison to separate the research task from the application task. Neither a broker discussion nor a website comparison replaces the lender’s final assessment.
| Dimension | Mortgage Pros | Money.com.au |
|---|---|---|
| Best for | Medical borrowers seeking mortgage broking support | Borrowers starting with online research |
| Research workflow | Discuss your circumstances and borrowing objective | Start with home loan information and comparison |
| Medical income | Specialisation in doctors, dentists and surgeons | Check medical-income suitability beyond comparison results |
| Application support | Home loan advice and approval support | Confirm the scope of assistance before proceeding |
| Standout feature | A medical-borrower focus within mortgage broking | A comparison-led starting point |
| Pricing model | Request written fee and remuneration disclosures | Check comparison, referral and assistance disclosures |
| Approval authority | The lender makes the lending decision | The lender makes the lending decision |
Specialist broking wins for medical-borrower fit
Mortgage Pros is the better fit for medical borrowers seeking specialist home loan broking support. Its stated specialisation covers doctors, dentists and surgeons, rather than treating medical lending as an incidental topic.
That is a service-fit verdict, not a promise of approval or preferential terms. Your occupation does not remove the need for a lender to assess affordability, credit history, deposit and the property offered as security.
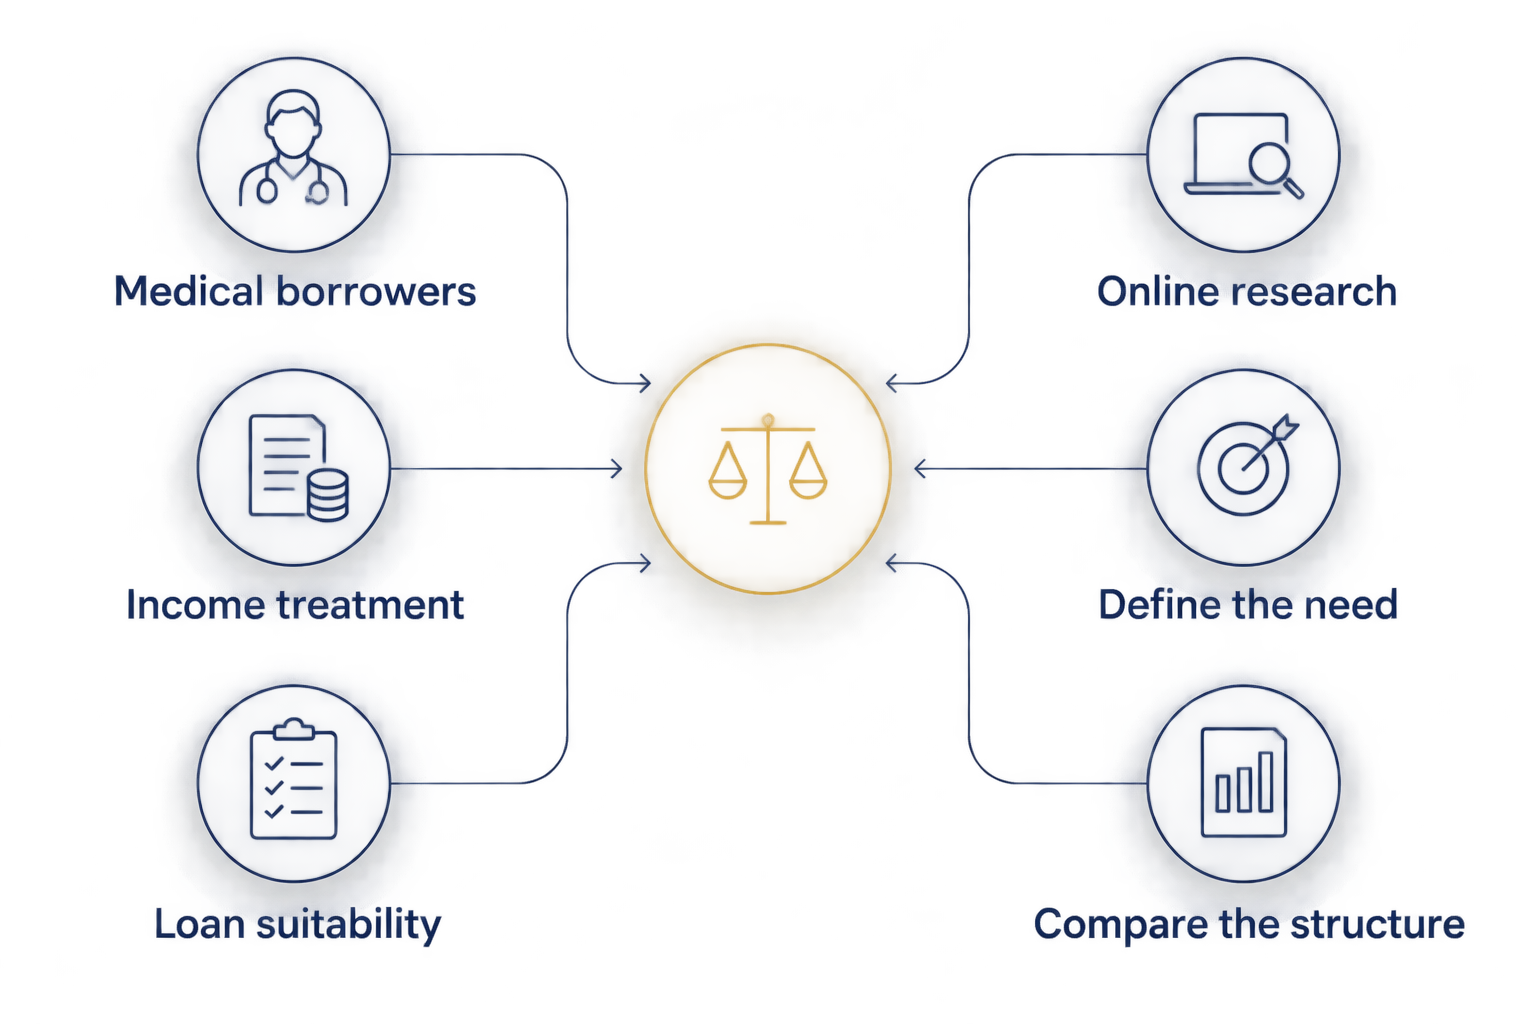
Before choosing a doctor mortgage broker in 2026, ask these 3 questions:
- Income treatment: Which parts of my earnings will the proposed lender assess, and what evidence supports them?
- Eligibility: Which conditions apply to any medical-professional lending policy being considered?
- Loan suitability: Why does this loan suit my circumstances beyond its interest rate?
A useful answer connects a lender’s requirements to your documents. It does not stop at describing a product as suitable for doctors.
The limitation of a specialist-broker route is that you still need to examine the recommendation. Specialisation is a reason to start the conversation, not a substitute for checking the loan’s conditions and the alternatives considered.
Money.com.au wins for an online-first research task
Money.com.au is the better starting point when you want to research home loan options online before discussing an application. You can use comparison-led research to develop questions about loan types, repayment structures and features.
This suits a borrower whose immediate objective is understanding the market, rather than resolving an income-assessment problem. You do not need an application recommendation merely to learn the difference between an offset account and redraw.
The advantage is control over the research process. You decide which questions to explore before sharing your circumstances with a broker or lender.
The limitation is equally important: a comparison result does not establish your eligibility. Check which lenders are represented, how results are ordered and whether commercial relationships affect what you see.
Do not interpret this research verdict as a judgement about every service available through the website. Before enquiring, establish who will handle your enquiry and exactly what assistance that person provides.
Specialist broking wins when the application needs explanation
A borrower with straightforward salary income and a settled deposit has a different preparation task from a surgeon combining hospital and private income. The latter needs more than a shortlist of loan features: the application must explain how the income is earned and evidenced.
A mortgage broking service is the stronger starting point when you want advice and approval support around that task. The client’s stated service includes helping individual borrowers and investors secure and manage home loans across Australia.
Bring a clear account of your position:
- Your employment and practice arrangements.
- Each income source and the documents available to support it.
- Existing loans, credit commitments and regular expenses.
- Your deposit source and intended property use.
- Any purchase deadline or upcoming change in employment.
Ask the broker to distinguish between what has been checked and what remains subject to lender assessment. A proposed approach is not the same as a credit decision.
The trade-off is involvement: tailored advice requires you to explain your circumstances and provide evidence. If you only want an initial understanding of loan features, that depth of engagement is not yet necessary.
Money.com.au wins when your next decision is what to compare
Online research is most useful when you have not yet defined the loan you need. Starting with a comparison-led approach lets you identify the features that deserve attention before requesting an individual recommendation.
Separate your research into 2 stages:
- Define the need: Decide whether you are buying, refinancing, investing or accessing equity.
- Compare the structure: Examine repayment type, fixed or variable arrangements, offset access and restrictions on extra repayments.
This prevents a common comparison error: treating unlike loans as interchangeable because their advertised rates look similar. An interest-only investment loan and a principal-and-interest owner-occupier loan address different borrowing circumstances.
The limitation is that understanding a feature does not establish its value for you. An offset account, for example, needs to be assessed alongside the loan’s costs and the cash you expect to retain.
Use online research to sharpen your brief. Once the question becomes whether a lender will accept your circumstances, move from browsing to a documented assessment rather than repeatedly changing comparison filters.
The standout difference is the starting point, not a guaranteed result
The clearest distinction in this comparison is the entry point. One starts with a mortgage broking service that specialises in medical borrowers; the other suits a comparison-led research task.
For a doctor buying in 2026, the important sequence is to understand the income position, identify relevant lender criteria and then compare suitable loan structures. Starting with the lowest displayed rate reverses that sequence if the lender will not accept the application.
For an early-stage researcher, the sequence is different. Learn the terminology, identify the features you need and prepare questions before requesting advice.
Neither route deserves credit for an outcome before the lender has assessed the application. Judge the service by whether it answers the question you actually need resolved.
Use research and advice for different jobs
You do not have to treat the choice as exclusive. Online comparison can establish your questions; a broker discussion can examine how those questions apply to your financial position.
The distinction between lenders versus mortgage comparison sites is also about decision-making authority: a website comparison does not commit a lender to approve your application. The lender’s assessment remains separate from the information used to begin your search.
Keep that separation clear when moving between services. Ask whether you are receiving general information, a personalised credit recommendation or a lender’s decision, and retain the documents that explain the answer.
Before providing application documents, confirm:
- Who handles it: Identify the business and person receiving your enquiry.
- What happens next: Establish whether the next step is a discussion, assessment or application.
- What is shared: Read the consent and privacy information before submitting personal documents.
- What is recommended: Request the reasons for a proposed loan and the relevant disclosures.
This approach makes each service accountable for its actual role. It also gives you a cleaner basis for deciding whether to continue.
Pricing is a disclosure check, not a declared winner
For a 2026 decision, separate the cost of the home loan from the way a broker, comparison service or referral arrangement is remunerated. They are different parts of the transaction.
Mortgage broking can involve lender-paid commission, borrower-paid fees or a combination. Comparison businesses can operate through referral or other commercial arrangements. These are category models, not a statement of either business’s specific terms.
For both options, request the applicable written disclosures before proceeding. Ask whether you will pay a service fee, whether a lender or referral partner pays remuneration, and whether commercial relationships affect the options presented.
The practical trade-off is transparency rather than a presumed cheaper channel. A clearly explained arrangement lets you assess the recommendation; an unexplained arrangement leaves you unable to judge the incentives behind it.
Neither option wins on cost without a like-for-like loan assessment and its associated disclosures. Compare the same loan amount, repayment basis and relevant features, rather than assuming that one route automatically produces a better financial outcome.
Neither route can guarantee home loan approval
Both routes ultimately meet the same boundary: the lender decides whether to approve the loan. Broking support and comparison research serve different purposes, but neither overrides lending criteria.
Keep 3 decisions separate: choosing an adviser or research service, selecting a proposed loan, and receiving formal approval. Progress through one does not establish the next.
For medical borrowers, ask whether any professional eligibility condition has actually been checked. For every borrower, confirm which conditions remain outstanding before relying on an approval status when making property decisions.
Approval certainty is a tie: neither a comparison result nor a broker recommendation is unconditional approval.
Final verdict: choose by borrower profile
Choose Mortgage Pros if you need medical home loan support
Best for: doctors, dentists and surgeons seeking mortgage broking advice and application support. Choose this route when your priority is explaining income, assessing eligibility and preparing a suitable application—not simply researching features.
Ask for a clear explanation of the proposed lender, supporting evidence, loan structure and remuneration before proceeding.
Choose Money.com.au if you are researching first
Best for: borrowers building an initial understanding of home loan options online. Choose this starting point when you want to define your requirements and prepare comparison questions before seeking individual assistance.
Confirm the scope of any subsequent service separately. The research starting point does not establish what happens after you enquire.
| Dimension | Winner |
|---|---|
| Medical-borrower fit | Specialist mortgage broking |
| Online-first research | Money.com.au |
| Application explanation | Specialist mortgage broking |
| Defining comparison questions | Money.com.au |
| Standout approach | Match the starting point to your task |
| Pricing and remuneration | No winner without disclosures |
| Approval authority | Tie: the lender decides |
Discuss your home loan today
Explain your income, deposit and borrowing plans before deciding on your next application step.
FAQ
Is Mortgage Pros or Money.com.au better for doctors?
Mortgage Pros is the stronger service fit for doctors seeking specialist mortgage broking support. Money.com.au suits an initial online research task; neither route guarantees approval or professional lending concessions.
Can I use an online comparison site before speaking to a broker?
Yes, online comparison can help you identify loan features and prepare questions before speaking to a broker. Treat the results as research, not confirmation that a lender will accept your circumstances.
Does a lower advertised rate mean a better home loan?
No, a lower advertised rate does not by itself establish that a loan is better for you. Assess eligibility, fees, repayment structure, features and restrictions alongside the rate.
Will a doctor automatically qualify for special home loan terms?
No, being a doctor does not automatically establish eligibility for special lending terms. Ask which professional, income and other conditions apply to the proposed lender and have them checked against your circumstances.
What should I ask about mortgage broker fees?
Ask whether you pay a fee, whether the lender pays commission and which written disclosures explain the arrangement. Also ask how the broker selects the options presented to you.
Who actually approves my home loan application?
The lender makes the lending decision. A comparison website, broker discussion or proposed loan recommendation does not replace the lender’s assessment or satisfy outstanding approval conditions.
One last thing
Before choosing a service in 2026, write down the question you need answered. If it is about loan features, start with research; if it is about whether your income supports an application, request an assessment.
A useful next step resolves uncertainty—not just produces another shortlist. Contact us today to discuss your borrowing plans and the evidence needed to assess them.
Related guides
- How to choose a doctor mortgage broker for complex income
- How locum doctors can document income for a home loan
- How surgeons combine hospital and private income for a home loan