Choose Mortgage Pros if you want a mortgage broker with an explicit focus on doctor home loans; choose Loan Market if you already have a trusted adviser there whose experience matches your application. This 2026 comparison separates medical-borrower expertise from the value of an established broker relationship.
- Mortgage Pros vs Loan Market: prioritise doctor home loan expertise or a proven relationship with your existing broker.
- For medical borrowers, compare how each adviser documents overtime, contracts and private-practice income.
- Loan Market suits borrowers who already have a trusted adviser with relevant experience.
- Request written lender reasoning, remuneration disclosures and application responsibilities before choosing.
Why this matters
A brokerage name does not tell you how a lender will assess your income, whether a proposed loan suits your plans, or who will resolve an application problem. The person preparing your application matters. So does the evidence behind their recommendation.
For a doctor, the useful comparison starts with your employment and income structure rather than a generic list of loan features. A hospital employee receiving overtime needs different preparation from a practitioner combining employment with private-practice earnings.
Mortgage Pros is the stronger starting point for doctors seeking a mortgage broker with a stated medical-lending focus. That is a positioning advantage, not a promise of approval, a lower rate or a larger borrowing limit.
Use this 2026 comparison to choose whom to interview first. Then judge the actual advice against your circumstances.
At a glance
| Dimension | Mortgage Pros | Loan Market |
|---|---|---|
| Best for | Doctors seeking a brokerage with an explicit medical home-loan focus | Borrowers with an established, trusted Loan Market adviser |
| Standout feature | Stated specialisation in doctor home loans | Broker network offering a choice of individual advisers |
| Existing relationship | A fresh assessment if you are changing advisers | Continuity if your existing adviser already understands your finances |
| Income assessment | Assess the proposed treatment of each income source | Assess the proposed treatment of each income source |
| Lender selection | Require reasons tied to your eligibility and objectives | Require reasons tied to your eligibility and objectives |
| Pricing model | Obtain written fee and commission disclosures | Obtain written fee and commission disclosures |
The table identifies where each option makes sense; it does not rank individual advisers who have not assessed your application. Neither a specialist label nor a familiar brand replaces a written explanation of the recommended loan.
Medical specialisation favours the doctor-focused option
For a doctor choosing a new broker, an explicit medical home-loan focus is a relevant starting advantage. It gives you a clear reason to ask about the lending issues attached to your work, rather than beginning with a general property discussion.
Bring your actual circumstances to the first conversation. Explain whether you are employed, contracting, working as a locum, operating a practice, or combining income sources. Identify any upcoming change in employment before discussing a borrowing estimate.
Ask these 3 questions:
- Income treatment: Which parts of my earnings will support the proposed assessment, and what evidence is needed?
- Employment changes: How will a new contract, probation period or change in work pattern affect the application?
- Lender reasoning: Why does the recommended lender suit this employment and income structure?
The limitation is straightforward: a stated specialisation does not establish your eligibility for any particular lender policy. Registration, employment, liabilities, deposit and property details still need assessment.
A Loan Market adviser with relevant medical-borrower experience remains a credible alternative. Ask for an explanation of the approach to your circumstances, without requesting another client's confidential information. Choose demonstrated reasoning over a broad claim of expertise.
Network choice favours borrowers choosing an individual adviser
Loan Market operates as a broker network, so your decision includes selecting the individual adviser you want to work with. This suits borrowers who place particular value on the person handling their application rather than choosing primarily by a brokerage's stated specialisation.
That distinction matters when you already know an adviser through a previous transaction or a trusted introduction. You can assess their communication directly: do they answer your questions clearly, explain trade-offs and identify what needs checking?
The benefit is adviser choice. The limitation is that a network name alone does not establish the experience, service arrangements or suitability of a particular broker for your loan.
Ask who will conduct the assessment, who will prepare the application and who will communicate with you. If several people are involved, request a clear point of contact. A familiar name on the introduction is less useful if you do not understand who takes responsibility afterwards.
Loan Market wins on continuity with a trusted existing adviser
Choose Loan Market if your existing adviser has served you well and can explain the next loan decision clearly. Continuity is a genuine reason to stay, especially when the adviser already understands your ownership structure, previous applications and longer-term plans.
An established relationship does not remove the need for a fresh assessment. Your income, debts, property goals and loan requirements can change. Ask the adviser to update the recommendation rather than simply repeat the previous structure.
Switching advisers also has a practical cost: you need to explain your circumstances again and establish a new working relationship. That effort is justified when you need a different area of expertise or clearer advice, not merely a different logo.
For an existing customer, the useful question is not whether another brand sounds more specialised. Ask whether your current adviser can address the specific issue in front of you. If the explanation is clear and supported, continuity has value; if it is not, seek another assessment before authorising an application.
Income assessment is a tie until the reasoning is clear
Neither brokerage name determines which earnings a lender accepts. The useful comparison is how the adviser documents your income and matches it to the proposed lender's requirements.
For medical borrowers, separate the income sources before discussing a headline borrowing figure:
- Employment income: Your salary, employment terms and supporting payslips.
- Variable income: Overtime, on-call payments and other earnings that need separate explanation.
- Practice income: Business records and the distinction between business receipts and personal income.
- Other commitments: Existing loans, credit facilities and financial obligations relevant to the assessment.
Ask each adviser to distinguish confirmed information from assumptions requiring lender review. An estimate built on unconfirmed income treatment is not equivalent to an assessment supported by appropriate evidence.
For your 2026 application, request a written explanation of any income excluded from the assessment. That discussion is more useful than choosing whichever adviser initially presents the largest borrowing figure.
Neither side wins this dimension before assessing your documents. A clear explanation of accepted income, required evidence and unresolved questions is the standard both must meet.
Lender selection is a tie without an application-specific case
A lender recommendation should answer a practical question: why does this loan suit your circumstances better than the alternatives considered? A recognisable lender name is not the answer.
Ask each adviser to explain the recommendation across these areas:
- Eligibility: How your employment, deposit and property fit the proposed lender's requirements.
- Loan structure: Why fixed, variable or split borrowing suits your stated priorities.
- Features: Whether you need an offset account, redraw or flexibility to make additional repayments.
- Trade-offs: What you give up by choosing the recommended structure.
Do not assume a larger lender selection automatically produces a better recommendation. What matters is whether the adviser considers suitable options and explains the choice clearly.
Compare the same brief with each broker. If one assessment assumes an owner-occupied purchase and another assumes an investment purchase, the resulting recommendations do not answer the same question. Correct the brief before comparing the outcome.
Pricing: compare the remuneration model, not assumptions
Mortgage broking remuneration can involve lender commissions, borrower-paid fees or a combination. Ask each adviser to explain the arrangements that apply to your engagement before you authorise work or submit an application.
Lender-paid remuneration and a borrower-paid service create different questions. For lender-paid remuneration, ask how the adviser manages conflicts and explains the recommendation. For a borrower-paid service, ask what work the fee covers and when the payment obligation arises.
Request written answers covering:
- Whether you will pay a broker fee and what triggers it.
- How the broker receives lender commissions.
- Whether an agreement creates any payment obligation if your circumstances change.
- Which lender, legal or other transaction expenses sit outside the broker's service.
Do not treat the broker's remuneration and the loan's expenses as interchangeable. They are separate parts of your decision.
For a 2026 comparison, obtain current disclosures from the individual adviser. There is no responsible pricing winner without comparing the terms offered for your engagement. Read the scope of service alongside the payment arrangements so you understand what happens before and after settlement.
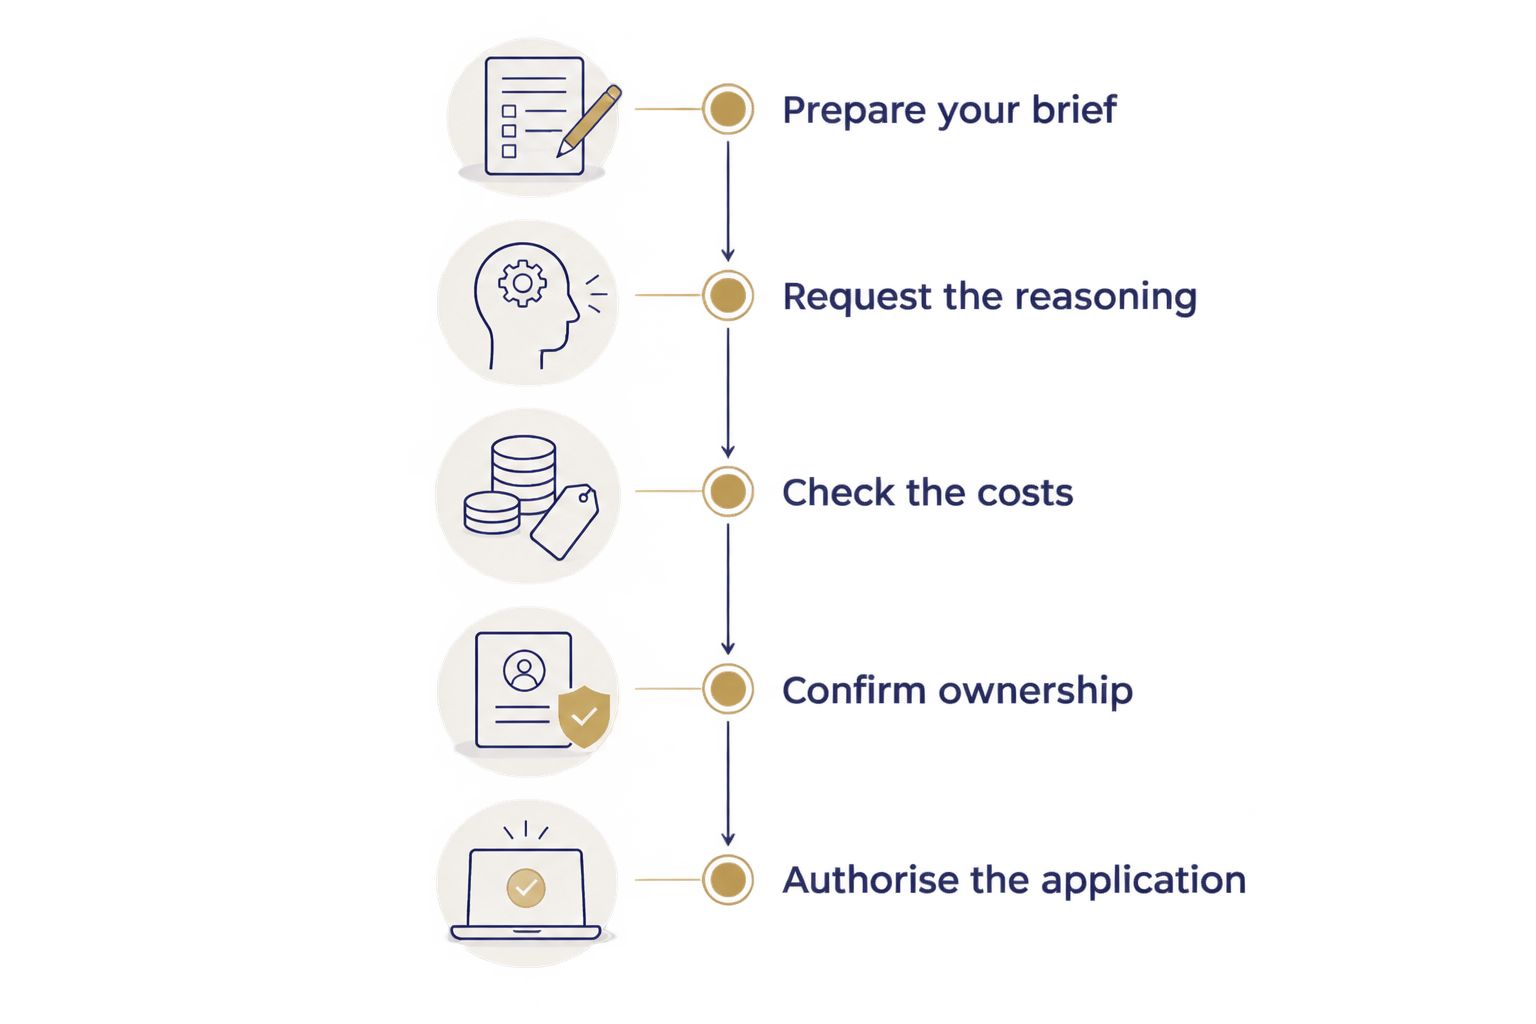
Compare 2 written assessments before choosing 1 broker
Use the same facts for both conversations, then select one adviser to coordinate the application you decide to pursue. Comparing advice is different from authorising overlapping submissions.
Prepare your brief
Write down the property purpose, deposit position, employment arrangements, existing debts and relevant deadlines. Include expected changes rather than presenting only your current position. A clear brief makes differences in advice easier to identify.
Request the reasoning
Ask for the proposed income treatment, lender rationale, loan structure and unresolved questions. You need enough explanation to understand why the recommendation suits you, not simply a list of lenders.
Check the costs
Read the fee agreement and remuneration disclosures. Separate the broker's engagement terms from the loan and transaction expenses. Ask for clarification before agreeing to anything you do not understand.
Confirm ownership
Identify who manages documents, lender questions and settlement coordination. Ask how you will receive updates and whom you should contact if a deadline changes.
Authorise the application
Confirm the lender and application approach before giving instructions to proceed. Make sure the adviser has addressed material questions about income, liabilities and the property.
This process gives you a more useful comparison than a score based on brand recognition. Keep the written brief and responses together so you can check that the final recommendation still reflects your instructions.
A clear brief also makes the first enquiry more productive. If you are a medical borrower, include your role and income structure when requesting an assessment rather than asking only for a rate.
Discuss your medical home loan
Explain your role, income structure and property plans before choosing an application approach.
Final verdict: choose by medical focus or proven continuity
Choose Mortgage Pros if you are a doctor seeking specialist focus
You are choosing a new broker and want the discussion to start with medical employment, income evidence and home-loan suitability. The stated doctor home-loan specialisation makes this the stronger first enquiry for that profile.
Keep the decision evidence-led. Ask the adviser to translate that focus into a clear assessment of your documents, lender options and next steps.
Choose Loan Market if your trusted adviser already fits the task
You already have a Loan Market broker who communicates clearly, understands your financial structure and can explain the proposed loan. Staying preserves that relationship without requiring you to start again elsewhere.
Do not stay solely through habit. Request an updated recommendation and judge whether the adviser addresses your current needs.
For either profile, your 2026 decision should rest on the advice you receive, not an assumed brand-wide advantage in rates, approval speed or borrowing power.
| Dimension | Winner |
|---|---|
| Starting point for a doctor seeking specialist focus | Doctor-focused brokerage |
| Choosing among individual network advisers | Loan Market |
| Continuity with a trusted existing Loan Market broker | Loan Market |
| Income assessment | Tie until document-based assessment |
| Lender selection | Tie until written lender reasoning |
| Pricing model | Tie until engagement terms are compared |
FAQ
Is Mortgage Pros better than Loan Market for doctors?
Mortgage Pros is the stronger starting point for doctors who want a brokerage with an explicit doctor home-loan focus. A Loan Market adviser with relevant experience remains an option; compare how each adviser assesses your actual employment and income.
Should I stay with my existing Loan Market broker?
Stay if your existing Loan Market broker understands your circumstances, communicates clearly and explains a suitable recommendation. Ask for a fresh assessment when your income, property plans or financial commitments change.
Will a specialist mortgage broker guarantee my approval?
No mortgage broker can guarantee a lender’s approval. Your application still needs to satisfy the lender’s assessment, including relevant income, liability and property requirements.
Which broker will get me a lower home loan rate?
A brokerage name alone does not establish which adviser will recommend the lower rate for your circumstances. Compare current written loan recommendations, including features, expenses and eligibility, rather than the rate alone.
How much does it cost to use either mortgage broker?
Ask the individual adviser for written fee and remuneration disclosures before proceeding. Confirm any borrower-paid fee, lender commission and separate transaction expenses that apply to your engagement.
Can I compare two mortgage brokers before applying?
Yes, you can compare advice before choosing whom to authorise. Give both advisers the same brief and make clear that you are seeking an assessment rather than instructing overlapping applications.
What should a doctor ask at the first mortgage appointment?
Ask how the proposed lender will assess your salary, overtime, on-call payments and any practice income. Also request the supporting-document requirements and an explanation of any assumptions that need confirmation.
One last thing
Ask each adviser: What would make you recommend against submitting my application now? A useful answer identifies unresolved issues and tells you what needs to happen next.
That question tests the quality of the advice without relying on a sales promise. To discuss your circumstances with Mortgage Pros, contact us today and explain your role, income sources and property plans.
Related guides
- How to choose a doctor mortgage broker for complex income
- Can doctors use overtime and on-call pay for a home loan?
- How do surgeons combine hospital and private income for a home loan?